


Due to AH's double slump, the market value has shrunk sharply by more than 70% in the past five months. Amidst this wave of AI valuations, CNC (03200), a leading global PCB equipment leader that has maintained high performance, continues to bottom out.
The Zhitong Finance App learned that AI computing power has brought special PCB equipment to the forefront, yet it has also caused Dazu CNC to suffer an “AH double kill.” From June 2025 to June 2026, benefiting from AI, the company's A-share market value nearly doubled tenfold. In February 2026, the company landed on the Hong Kong Stock Exchange, and the four-month increase was as high as 60%. The AI-related sector was fully adjusted after June, and the company's AH shares also continued to rise. Its Hong Kong stock fell from a high of HK$205.8 to HK$53.65, and the market value shrank by 74%, but the AH premium was still over 150%.
However, the company's performance was not affected by the valuation. According to its financial reports for the first three quarters, it achieved operating income of 7.841 billion yuan, an increase of 100.90% over the previous year, and net shareholders' profit of 1,544 billion yuan, an increase of 214.03% over the previous year, and maintained three-digit growth in revenue and profit.
In order to boost market confidence, on November 9, Dazu CNC issued the “Notice on the Company's A Share Repurchase Plan”. It plans to use its own funds or self-raised funds to repurchase A-shares through centralized bidding. The repurchase amount is 2-3 billion yuan, with a price cap of 214 yuan/share, showing optimism about the company's long-term development. Stimulated by buyback news, the company's AH shares both bottomed out and rebounded. Among them, H shares rose 10.5% in three trading days, but fell back to their original shape in the next two trading days.
Performance is the anchor of valuation, and revenue and profit remain high
Performance is the anchor of valuation. Although the market value of Dazu CNC has declined sharply due to AI valuation killings, the high growth in revenue and profit has provided strong support for the bottom of the valuation.
The main products of Dazu CNC are mechanical drilling equipment. Customers are concentrated in the PCB field, aiming to “become the most respected and trusted PCB equipment service provider in the world” and provide core process processing solutions for PCB companies. Judging from the company's development history, the phased phase is very obvious. The rapid development of AI PCBs in 2024 puts forward structural upgrade requirements for processing technology, which brings market opportunities to people with technical advantages.
Looking at the timeline, the company's 2024 performance began to grow. Revenue growth in the first three quarters of 2024 to 2026 was 104.56%, 72.68%, and 100.9%, respectively. As the two core products, drilling equipment and inspection equipment continued to increase in revenue. Among them, drilling equipment was the largest revenue and had the most impressive performance. The first half of 2026 increased by 101.4%, with a revenue share of 72.61%, and the combined revenue share of the two major products was 81%.
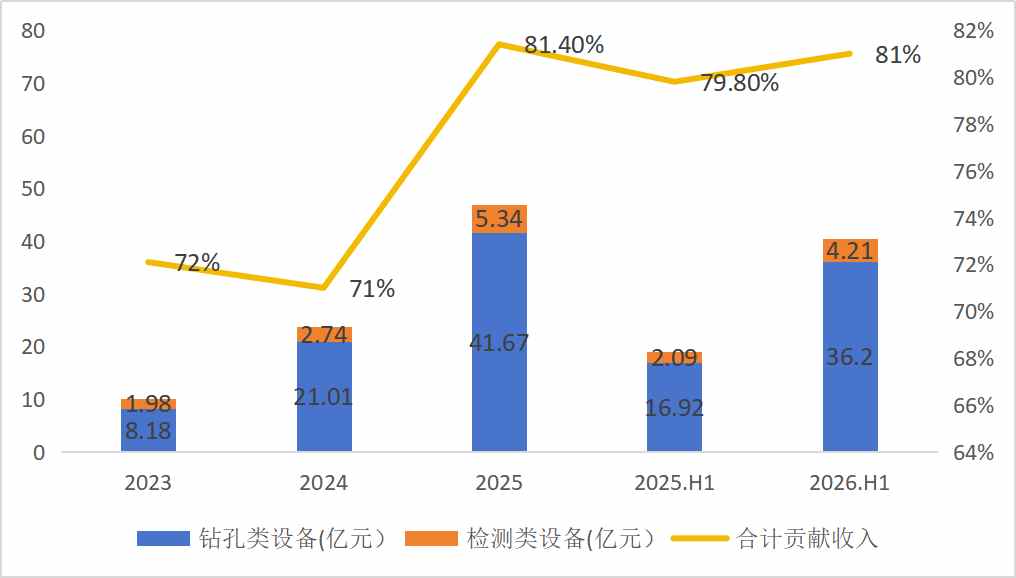
Data source: Company financial report
On the profit side, the growth rate was even more rapid. From 2024 to the first three quarters of 2026, shareholders' net profit was 302 million yuan, 824 million yuan and 1,548 million yuan respectively, up 122.13%, 173.16% and 214.91% year-on-year respectively. Shareholders' net interest rate rose all the way to 19.74%, and the annualized ROE increased to 16.65%.
Dazu CNC's performance is growing strongly. Thanks to the comprehensive strategic transformation of AI, the company strategically positions “ALL IN AI”. Facing the opportunities brought about by the iteration of AI computing power chips and data center technology to make PCB processing more difficult, the company refined product development and consolidated the technical moat in core processes such as drilling. In 2026, the company seized the market opportunity of downstream customers to expand production and upgrade, and orders for all products grew dramatically. Among them, demand for high-end AiPCBs such as next-generation rack server computing power and switching unit high-multi-layer HDI boards, N+N high-layer boards, and 800g and 1.6t high-speed optical module MSAP carrier boards increased significantly. In the first three quarters, contract debt was 498 million yuan, an increase of more than 10 times over the previous year.
It is worth noting that strong demand for the company's products can also be further supported by accounts receivable and inventory. As of September 2026, the company had accounts receivable of $5.118 billion and notes receivable of $810 million, up 98.93% and 66.45% respectively from the beginning of the year, and inventory of $2,844 billion, up 50.2% from the beginning of the year. Due to increased stocking and the receivable model, the net operating cash flow outflow was 800 million yuan, but the cash flow was still abundant, with monetary capital of 4.931 billion yuan.
AI PCB continues to be booming, and the valuation has fully declined
The continued growth of Dazu CNC's performance depends on downstream demand, and AI PCBs remain booming. According to research estimates released by Citi during the year, the global AI PCB market will reach 152 billion yuan in 2026, an increase of 86% over the previous year. Judging from the performance of industry participants, the PCB industry achieved revenue of 332.46 billion yuan in the first three quarters of 2026, an increase of 45.09%, and net profit to mother of 45.832 billion yuan, an increase of 108.42%, which fully indicates that the downstream is in an upward cycle.
However, Dazu CNC has an industry-leading advantage in PCB drilling technology and continues to break through. Its mechanical through-hole and 3D back drilling solutions have achieved mass production processing of 31.5. 5:1 and above thickness diameter ratio and high-precision back drilling. The cold laser solution can stably process 50 μm dense microholes, adapting to the processing needs of AI servers and high-speed optical modules. At the same time, for advanced packaging, the company cooperated with leading customers to develop it. Its new laser equipment for BT/ABF material processing and special mechanical drilling equipment for the Core layer have received official orders, and are expected to release results in 2027.
Under the long-term partnership of scale advantage+technical advantage+leading PCB customers, the company may be one of the biggest beneficiaries of the rapid development of the industry, and the sustainability of performance growth is highly certain.
As mentioned above, performance is the valuation anchor. The company's performance began explosive growth in 2024, but the market capitalization later realized that it only started in September of that year. In July 2025, under the hot wave of AI investment, it began a wild model. It rose all the way to a high level of 395.36 yuan in June 2026, and the increase was as high as 13 times during the period. In fact, this is also a full reflection of the performance. After the valuation fell back, the PE (TTM) of A-shares was 35 times, while Hong Kong stocks were only 10 times higher.
However, the company's performance has maintained high growth. The 10-fold price-earnings ratio of Hong Kong stocks is clearly underestimated, and the AH premium is high, which provides a safety cushion for Hong Kong stock investors. In addition, Citi has lowered its target price for Hong Kong stocks several times. The most recent (October) target price was HK$105. There is still room for the premium to double. The bank is still optimistic about the company and raised Dazu CNC's profit forecast for 2026 by 11% to reflect better-than-expected results for the first nine months of 2026.
During the period of sharp valuation withdrawal, Dazu CNC mainly did two things: one was to stabilize market confidence, launch a large-scale repurchase, and develop an A-share repurchase plan of 2-3 billion yuan; the second was to bind cutting-edge talents and implement an equity incentive policy. The second was to grant 12.23 million restricted shares. A total of 536 people were awarded for the first time. Linked to performance, the target value of the net profit growth rate for 2027/2028/2029 was not less than 30%/70%/120%, respectively. This also injected strength into the market. In addition, the company pays dividends every year, continuously improving shareholder returns. The dividends for 2023-2025 are 8.5 yuan for 10 shares, 4 yuan for 10 shares, and 6 yuan for 10 shares, respectively. The dividend rate for Hong Kong stocks is 1.4%.
Overall, Dazu CNC's AH double kill was mainly due to the full-sector valuation loss brought about by the AI bubble, but the company's performance is impressive. Revenue and profit will all maintain three-digit growth in 2026. The AI PCB industry has high prospects and is in an upward cycle. The company's advantages in scale and technology will fully benefit. Combined with product orders, contract liabilities, and downstream demand, there is a high degree of certainty that the company's performance will continue to grow.
Moreover, the company's valuation has fallen back to the bottom, and the overvalued portion has been absorbed, compounded by the high AH premium and the investment bank's target price which is far higher than the current price, so there is plenty of room for repair.