


Erie Indemnity (ERIE) drew fresh attention after Erie Strategic Ventures, linked to Erie Insurance, funded AI startups Blitzy and HiddenLayer, signaling a push into infrastructure modernization and AI security partnerships.
For investors watching Erie Indemnity, recent trading has been mixed. The share price is up 19.39% over the past 30 days and 7.32% over 90 days, yet the year to date share price return is slightly down 1.11% and the 1 year total shareholder return is down 1.87%. This suggests short term momentum is building even as longer term results remain more muted.
Scan how Erie Indemnity compares to other insurers pushing into AI and infrastructure by reviewing our curated list of 38 AI small caps.
After a 19.39% jump in 30 days but softer longer-term returns, Erie Indemnity now sits at a crossroads. Has most of the easy upside already played out, or does valuation still leave meaningful room ahead?
Price-to-Earnings of 24.9x: Is it justified?
Erie Indemnity currently trades on a P/E of 24.9x, while our DCF estimate of future cash flow value sits at $267.66 versus a last close of $274.73. That combination points to a rich price tag next to both intrinsic value modelling and peers.
The P/E multiple compares what investors are paying today for each dollar of earnings. For an insurer like Erie Indemnity, this ratio often reflects how the market views the resilience of its profit stream, the reliability of underwriting results, and the perceived strength of its fee based model as managing attorney in fact for the Erie Insurance Exchange.
At 24.9x earnings, ERIE trades at more than double the US Insurance industry average P/E of 11.5x and well above the peer group average of 12.9x. The stock also sits materially above an estimated fair P/E of 15.4x, a level the market could move towards if expectations cool or sector valuations compress.
Explore the SWS fair ratio for Erie Indemnity.
Result: Price-to-Earnings of 24.9x (OVERVALUED)
Still, the Erie Indemnity story could change quickly if underwriting conditions tighten for the Erie Insurance Exchange or if AI investments fail to deliver clear cost efficiencies.
Find out about the key risks to this Erie Indemnity narrative.
Another View on Erie Indemnity’s Valuation
On a discounted cash flow view, the SWS DCF model pegs Erie Indemnity’s future cash flow value at $267.66 a share, slightly below the current $274.73 price. That flags a mild premium rather than a bargain, which raises a simple question for you as an investor: Is that modest gap acceptable given the quality metrics, or does it cap your appetite for risk?
Look into how the SWS DCF model arrives at its fair value.
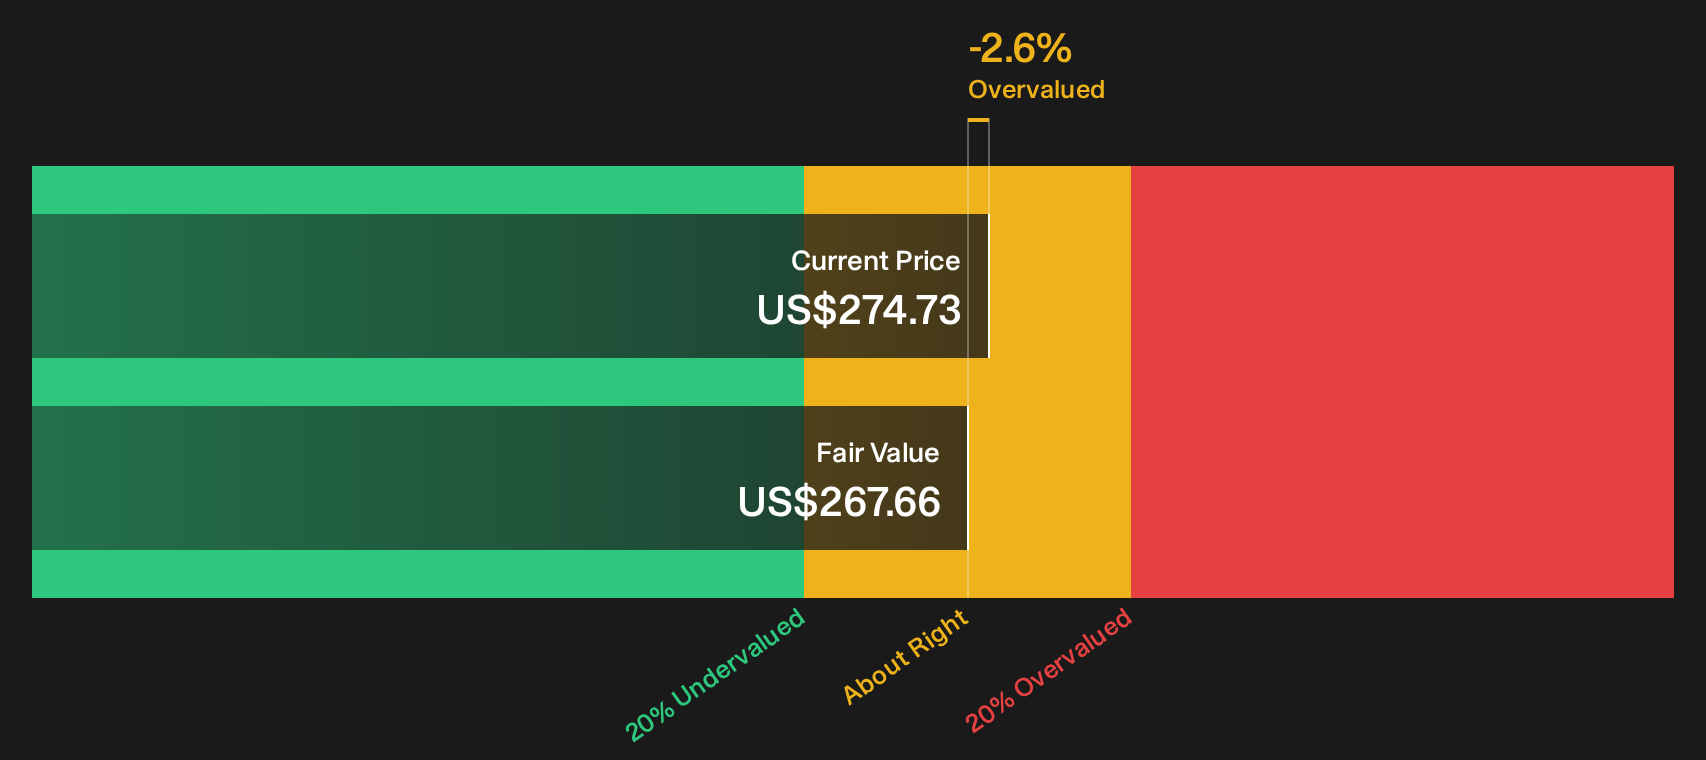
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Erie Indemnity for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Reading this, you can sense the mixed mood around Erie Indemnity, with valuation questions sitting beside at least one potential bright spot. Act quickly, review the numbers carefully, and weigh up the 2 key rewards.
Looking for more investment ideas beyond Erie Indemnity?
If Erie Indemnity feels fully priced to you, do not stop here. Broader opportunities across other sectors could fit your risk profile and return goals.
- Target stronger value plays by scanning companies that currently screen as 32 high quality undervalued stocks.
- Strengthen your income focus by reviewing stocks that qualify as 6 dividend fortresses.
- Prioritise resilience by checking companies that appear in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com