


Lemonade (LMND) just hit a key operating milestone, rolling out its renters insurance to all 50 states and Washington, D.C., while pairing that expansion with fresh third quarter results and new revenue guidance.
Lemonade’s recent renters insurance rollout and upbeat guidance have landed alongside a sharp swing in market sentiment, with the 1-day and 7-day share price returns of 2.86% and 11.73% contrasting with a year-to-date share price decline of 41.82% and a 1-year total shareholder return that is down 37.31%. The 3-year total shareholder return remains very large at roughly 17x, so momentum has cooled in the short term even as long-term holders still sit on sizeable gains.
Compare Lemonade’s rollout and guidance with a curated group of insurers and adjacent financials by scanning the list of solid balance sheet and fundamentals (24 results) for potential alternatives or complements to your watchlist.
After a sharp short term rebound and steep declines over the past year, Lemonade’s fresh guidance and renters milestone raise a simple question: Does the risk now justify paying today’s price for that growth story?
Most Popular Narrative: 9.7% Undervalued
Lemonade closed at $44.19, while the leading narrative estimates fair value at $48.95, so the current tag lines up close to that view. According to rcb9, an investor in the Simply Wall St Community who wrote the narrative, the real hinge is how reinsurance and underwriting quality interact rather than the headline revenue number.
Ignore the 79%. In-force premium, the measure of how much insurance Lemonade actually has on the books, grew 32.4% to $1.43 billion. Revenue grew 79% because ceded premiums fell roughly 49% as the company retained a larger share of its own risk. The company says as much in its letter.
See why 5 investors see Lemonade as 10% undervalued.
Result: Fair Value of $48.95 (UNDERVALUED)
Still, the Lemonade narrative hinges on a loss ratio that has only been seen in relatively calm periods and on reinsurance terms that could shift again.
Find out about the key risks to this Lemonade narrative.
Another View On Lemonade’s Valuation
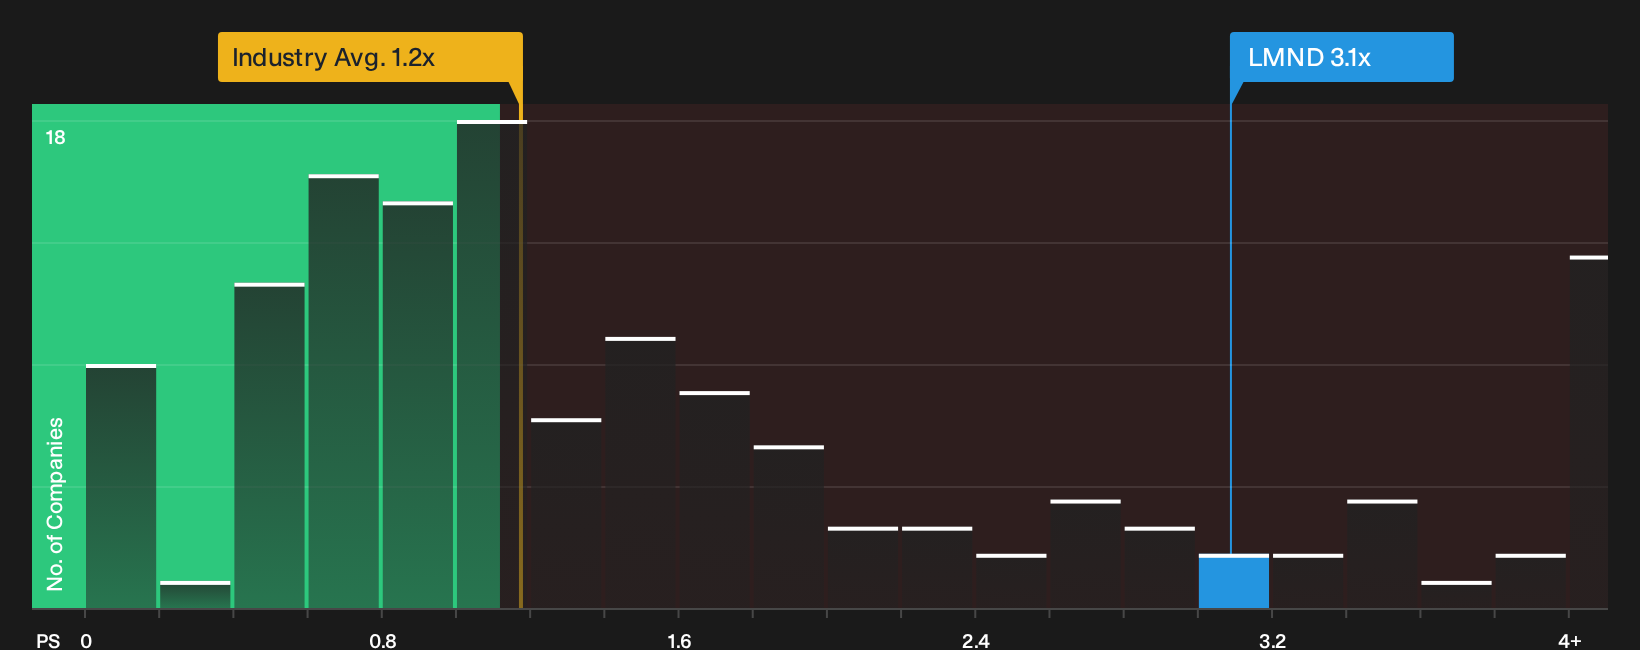
The narrative says Lemonade looks roughly 10% undervalued at $48.95 fair value, yet the current P/S ratio of 3.1x tells a different story. The broader US Insurance group sits near 1.2x and peers are around 2x, while the fair ratio is 1.6x. That gap points to a richer price tag than the sector, so the real question is whether the growth story and loss-ratio progress justify paying that premium.
For a closer look at how those sales multiples stack up against industry norms and peer levels, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around Lemonade leaves you unsure, spend a few minutes with the numbers yourself and stress test both sides of the story. To help frame that view, weigh the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Lemonade?
If Lemonade has sharpened your thinking, broaden the opportunity set and let a few well focused searches surface companies that better fit your investing checklist.
- Target quality at a discount by scanning our 32 high quality undervalued stocks that highlights companies with strong fundamentals at lower implied prices.
- Prioritise resilience first and hunt through the 31 resilient stocks with low risk scores to spot businesses with steadier risk profiles when volatility spikes.
- Zero in on dependable income streams and review the 6 dividend fortresses to find payout-focused companies with higher yielding distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com