


Kimbell Royalty Partners has nearly doubled investors' money over the past 5 years, which puts a spotlight on whether the current price is still in line with what its earnings can justify. With recent acquisitions, record production and a fresh distribution, the question is how much of that story is already embedded in the valuation.
- A 95.3% total return over 5 years raises the stakes for anyone asking if Kimbell Royalty Partners' earnings power can keep backing up this share price.
- Record production, a larger rig footprint and recent US$367m of acquisitions may support expectations for stronger cash generation that feeds directly into earnings over time.
- The analysts covering Kimbell Royalty Partners have run their own numbers. See what analysts think Kimbell Royalty Partners's shares could be worth.
The stock's next move may depend on whether today's valuation is adequately supported by Kimbell Royalty Partners' earnings profile.
If you want a reference point for Kimbell Royalty Partners' earnings story, it helps to compare it with other income focused plays by scanning 6 dividend fortresses.
Does Kimbell Royalty Partners Look Pricey on Earnings?
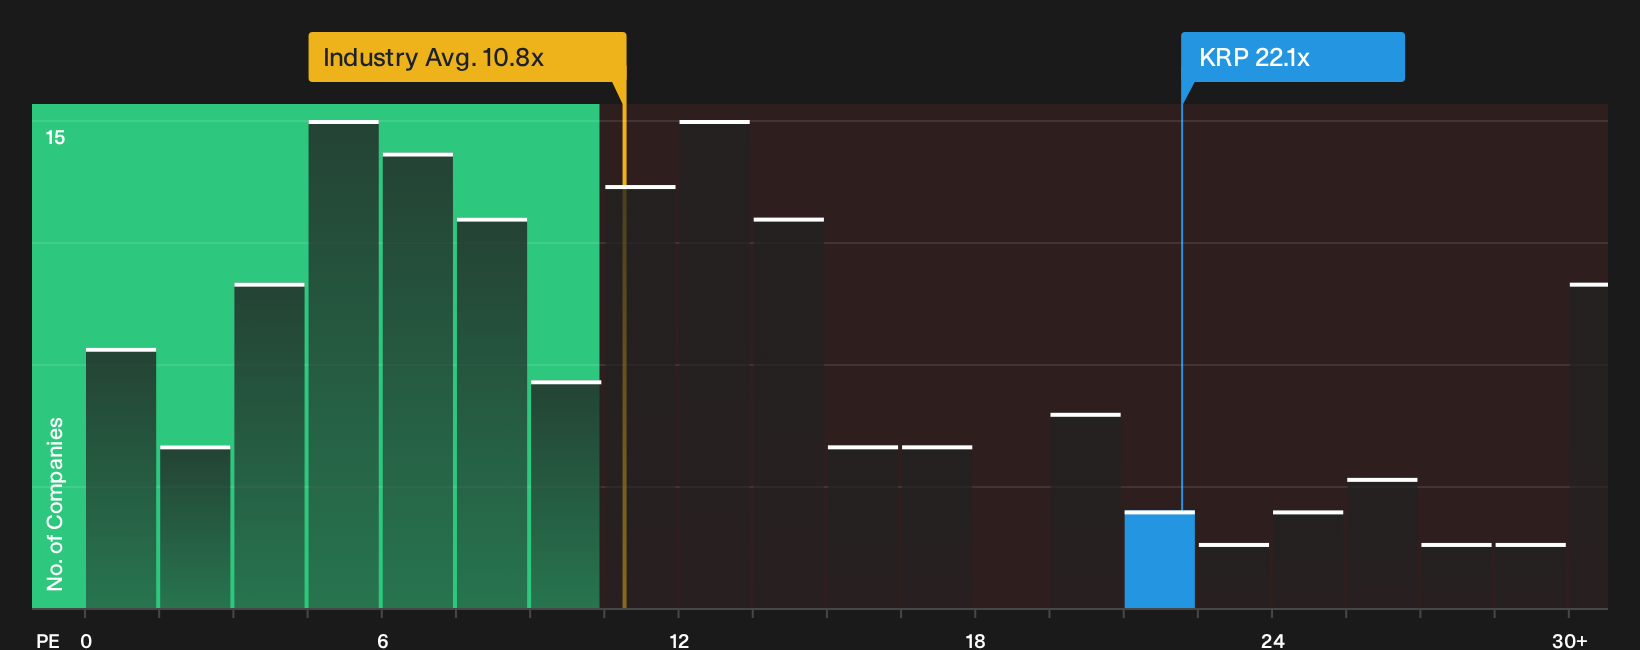
The P/E ratio fits Kimbell Royalty Partners because investors often look at earnings relative to price for income focused oil and gas partnerships. At around 22.1x earnings, the stock trades at roughly double the broader oil and gas industry average of 10.8x and also sits well above the peer group near 10.1x. That kind of premium asks you to assume the current earnings stream is relatively durable and that the partnership can keep turning its asset base into consistent profits.
The fair value model, which blends factors such as growth outlook, profitability, sector norms and risk profile, implies a lower P/E than where Kimbell Royalty Partners is currently priced, so the units screen as overvalued on this metric. Because record production and the recent US$367m of acquisitions have raised expectations around future cash generation, the current multiple already bakes in a lot of optimism about how those barrels convert into earnings over time. Explore the numbers behind Kimbell Royalty Partners's P/E valuation.
The Kimbell Royalty Partners Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for Kimbell Royalty Partners' P/E leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the units to be worth materially more or materially less than the current price. They sit on the stock's Community page for you to track over time. Each narrative treats fair value as a thesis about how Kimbell Royalty Partners' business might play out so you can watch how that story holds up against reality.
One of the top narratives on Kimbell Royalty Partners: 19% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main thing that has to go right is that Kimbell Royalty Partners continues to source accretive deals and manage leverage around its stated target..."
Discover why this Narrative puts Kimbell Royalty Partners at 19% undervalued.
One more angle on Kimbell Royalty Partners that could shift your view
Everything so far has focused on what Kimbell Royalty Partners looks like today, but analyst models sketch out where they think this partnership could be a few years from now and how that lines up with the current unit price. Explore where analysts expect Kimbell Royalty Partners to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com