


Dolby Laboratories has been a long-term underperformer on the chart, yet the business continues to be judged heavily on what its earnings can support. With the share price around US$63.61, the key question is whether that level still lines up with what the company is currently earning.
- The stock has fallen 23.0% over the past 5 years, which puts extra weight on the question of how much earnings power the current valuation is assuming.
- The company’s model of monetising audio and visual technologies through licensing and products means future earnings can hinge on how effectively it converts that intellectual property into steady cash flow.
- The analysts covering Dolby Laboratories have run their own numbers. See what analysts think Dolby Laboratories's shares could be worth.
The issue now is whether Dolby Laboratories’ present share price is properly supported by the earnings investors can reasonably expect from the business.
If you want to test the same earnings question that hangs over Dolby Laboratories against a wider field, scan a set of 32 high quality undervalued stocks for comparison.
Does Dolby Laboratories Look Fairly Valued on Earnings?
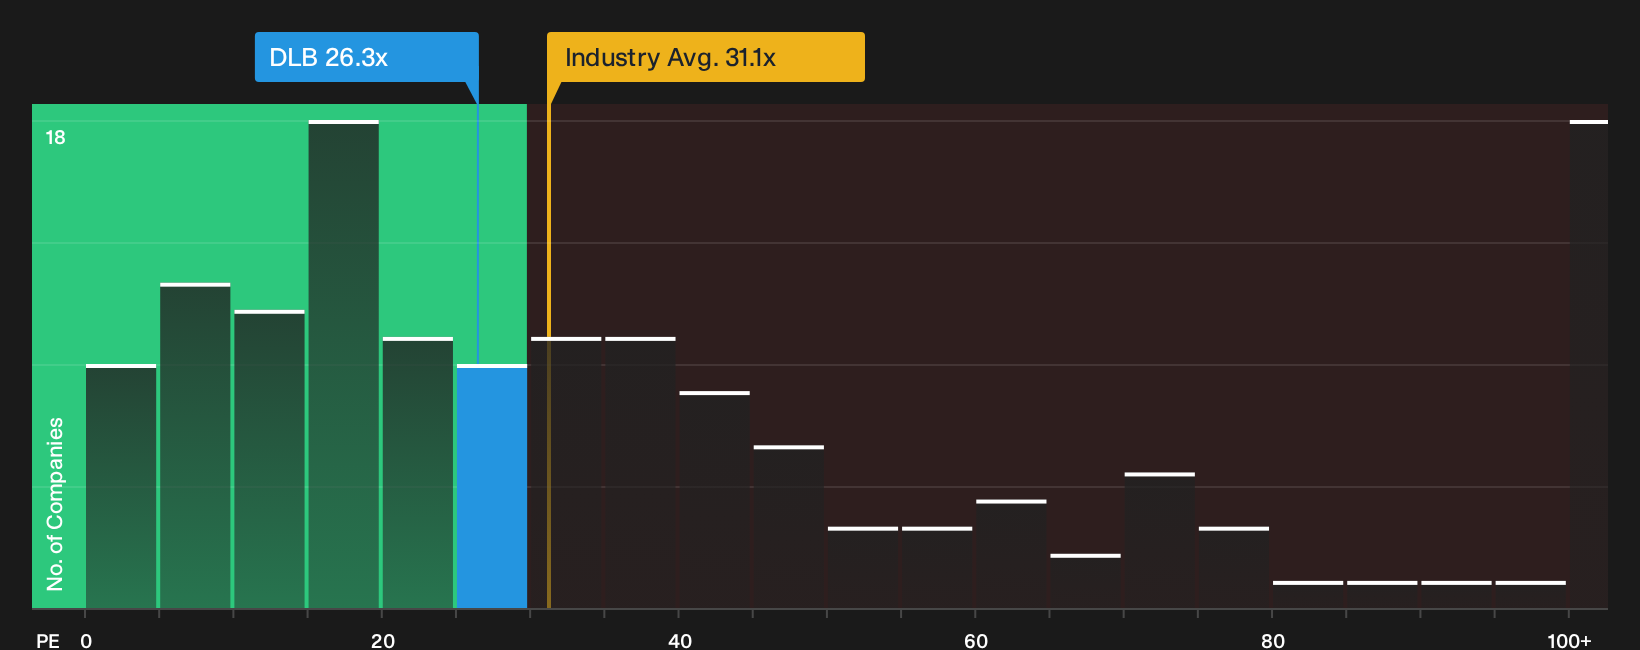
The P/E ratio fits Dolby Laboratories because earnings remain the main lens investors use to judge the licensing model. At roughly 26.3x earnings, the stock trades below both the wider software industry on about 31.1x and the peer group near 32.4x. That gap indicates the market is not assigning a premium multiple to Dolby even though it relies on a relatively asset light, royalty heavy structure.
The tailored fair multiple for Dolby Laboratories sits close to where the shares trade today, so the current P/E looks in line with this model rather than clearly cheap or expensive. For a holder, the useful question is whether the licensing pipeline, margins and cash conversion justify the market paying a mid 20s earnings multiple for the long haul. Explore the numbers behind Dolby Laboratories's P/E valuation.
The Dolby Laboratories Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/E puzzle for Dolby Laboratories leaves off. They spell out which paths for earnings, profitability and cash generation would need to play out for the current share price to look too low or too high. Each narrative links its number to a specific view on how Dolby Laboratories' growth, margins and key risks might evolve, giving you a reference point you can return to as fresh information comes through.
Bullish and bearish Narratives on Dolby Laboratories focus on the same products and patents but reach different conclusions about how much they are worth today.
Bull case: 29% undervalued
This view comes from the bullish analyst Narrative on Simply Wall St, which leans heavily on newer formats and content partnerships.
"The build out of the video distribution patent pool to 45 licensors with major platforms such as Meta, Alibaba, ByteDance, Roku and Tencent signed..."
Discover why this Narrative puts Dolby Laboratories at 29% undervalued.
Bear case: roughly fairly valued
This angle reflects the bearish analyst Narrative on Simply Wall St, which worries more about pricing power and licensing stability.
"Bearish analysts expect rising component costs, open codecs, and vertically integrated tech ecosystems to keep pressuring Dolby Laboratories' licensing terms..."
Explore why this Narrative puts Dolby Laboratories at roughly fairly valued.
Dolby Laboratories is more than just today's share price
Price and current earnings only tell part of the Dolby Laboratories story, since analysts also map out where they think the business could be a few years from now. This gives you another lens to compare with the current valuation. Explore where analysts expect Dolby Laboratories to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com