


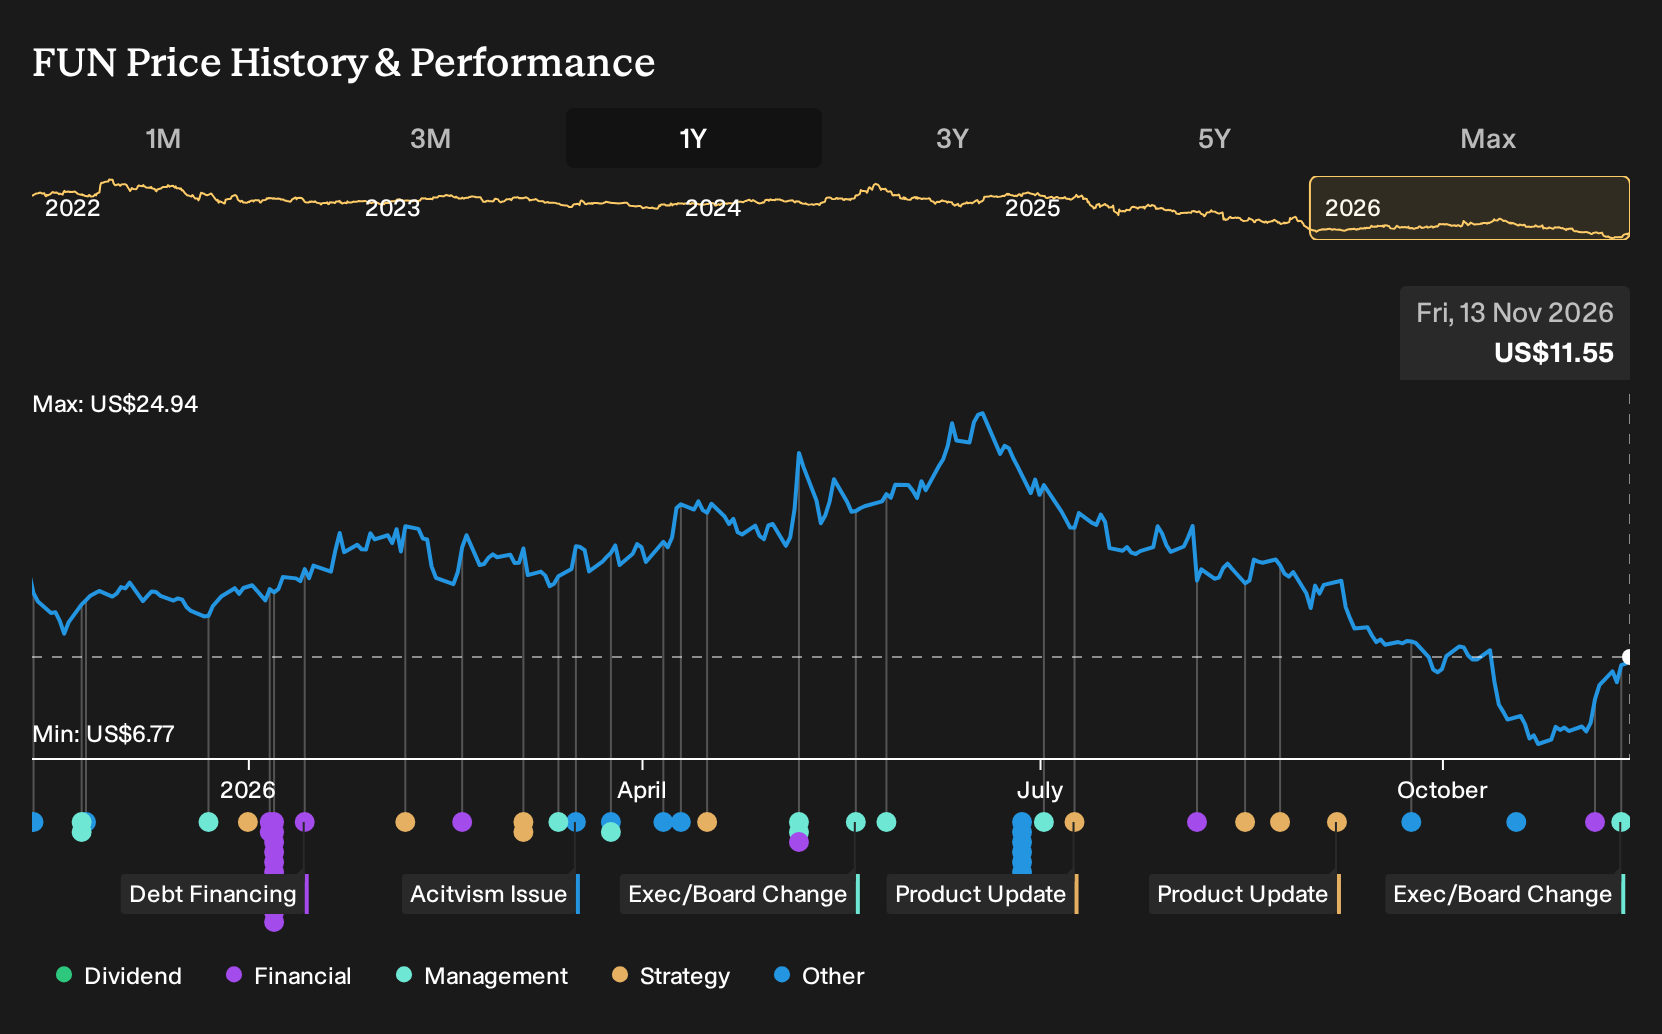
- Six Flags Entertainment reported third quarter 2026 revenue of US$195.55 million and a net loss of US$366.12 million, while also appointing experienced procurement leader Adam Boal as chief procurement officer and facing a legal investigation after a fatal roller coaster accident that led to nine ride closures.
- The combination of continued operating losses, a new procurement executive focused on large scale spending and supplier management, and heightened safety scrutiny points to pressure on Six Flags Entertainment to control costs, manage risk, and maintain park operations under closer public and legal attention.
- This article examines how Six Flags Entertainment's investment narrative is affected by the accident-driven safety review and the related legal investigation.
Compare how Six Flags Entertainment's risk profile stacks up against other businesses facing legal, safety or operational pressure by scanning our curated 31 resilient stocks with low risk scores for potential alternatives with more resilient fundamentals.
Six Flags Entertainment Investment Narrative Recap
To own Six Flags Entertainment today, you need to believe the park portfolio can produce enough cash to service its debt and still leave value for equity holders. The recent fatal accident, ride closures and securities investigation push safety, legal exposure and guest sentiment into the foreground. For now, the biggest near term swing factor is how quickly attendance and in park spending settle after this shock.
The largest risk remains the combination of operating losses, high leverage and negative shareholders' equity. Third quarter revenue of US$195.55 million and a net loss of US$366.12 million keep the focus on cash generation rather than headline valuation. According to FRAGMENTS, an investor in the Simply Wall St Community, any asset sale or takeover thesis only works if the remaining parks support their own capital needs and debt costs.
The most relevant announcement here is the appointment of Adam Boal as chief procurement officer. His background at CBRE and AstraZeneca involved overseeing multi billion dollar spend, supplier platforms and third party risk. For Six Flags Entertainment, that experience sits right where investors are watching most closely: large capital projects, ride maintenance and safety critical vendors.
FRAGMENTS argues that park level cash flow and required investment already needed tighter scrutiny before the accident. Boal's role now links directly to that question: how to manage US$4.9b of net debt, substantial capital budgets and ongoing safety measures without eroding the value of flagship destinations. Execution on procurement discipline, rather than headlines about potential buyers, is likely to drive the next set of meaningful catalysts.
FRAGMENTS anchors a US$7.00 per share fair value on current operating cash flow, which does not independently support the more optimistic property valuations. The analysis still assigns some weight to the possibility of asset transactions and an improvement in Six Flags Entertainment's operations over time.
Uncover why Six Flags Entertainment's fair value indicates a 39% potential downside to its current price, suggesting that the existing premium may not be sustainable.
Exploring Other Perspectives
The lowest analysts focus on Six Flags Entertainment's earnings power rather than the asset sale story. Before this accident, they were building a case where revenue drifts to about US$2.9b and earnings to roughly US$201.9 million by 2029, yet still justify a lower price target. That is a much more pessimistic path than FRAGMENTS uses. It shows how wide the opinion gap can be, and why you may want to compare several narratives that could easily shift after the recent events.
Explore 5 other Six Flags Entertainment fair value estimates, including one that suggests as much as 54% downside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Six Flags Entertainment research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Six Flags Entertainment. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Six Flags Entertainment's overall financial health at a glance.
Looking for more Six Flags Entertainment style investment ideas?
Once you have a clear stance on Six Flags Entertainment, it often helps to widen the lens and compare it with other businesses that fit different risk and return profiles. The Simply Wall St Screener can help you quickly surface groups of companies that match the type of portfolio role you want this stock to play.
- If you want potential upside with less balance sheet stress, consider a list of solid balance sheet and fundamentals (24 results) that can help you focus on companies with stronger financial footing.
- If dependable income is the priority, shift attention to candidates in our 6 dividend fortresses that may offer substantial yields with a focus on resilience.
- If you are hunting for ideas that the market might not fully appreciate yet, scan through a 20 high quality undiscovered gems that combines quality fundamentals with lower market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com