


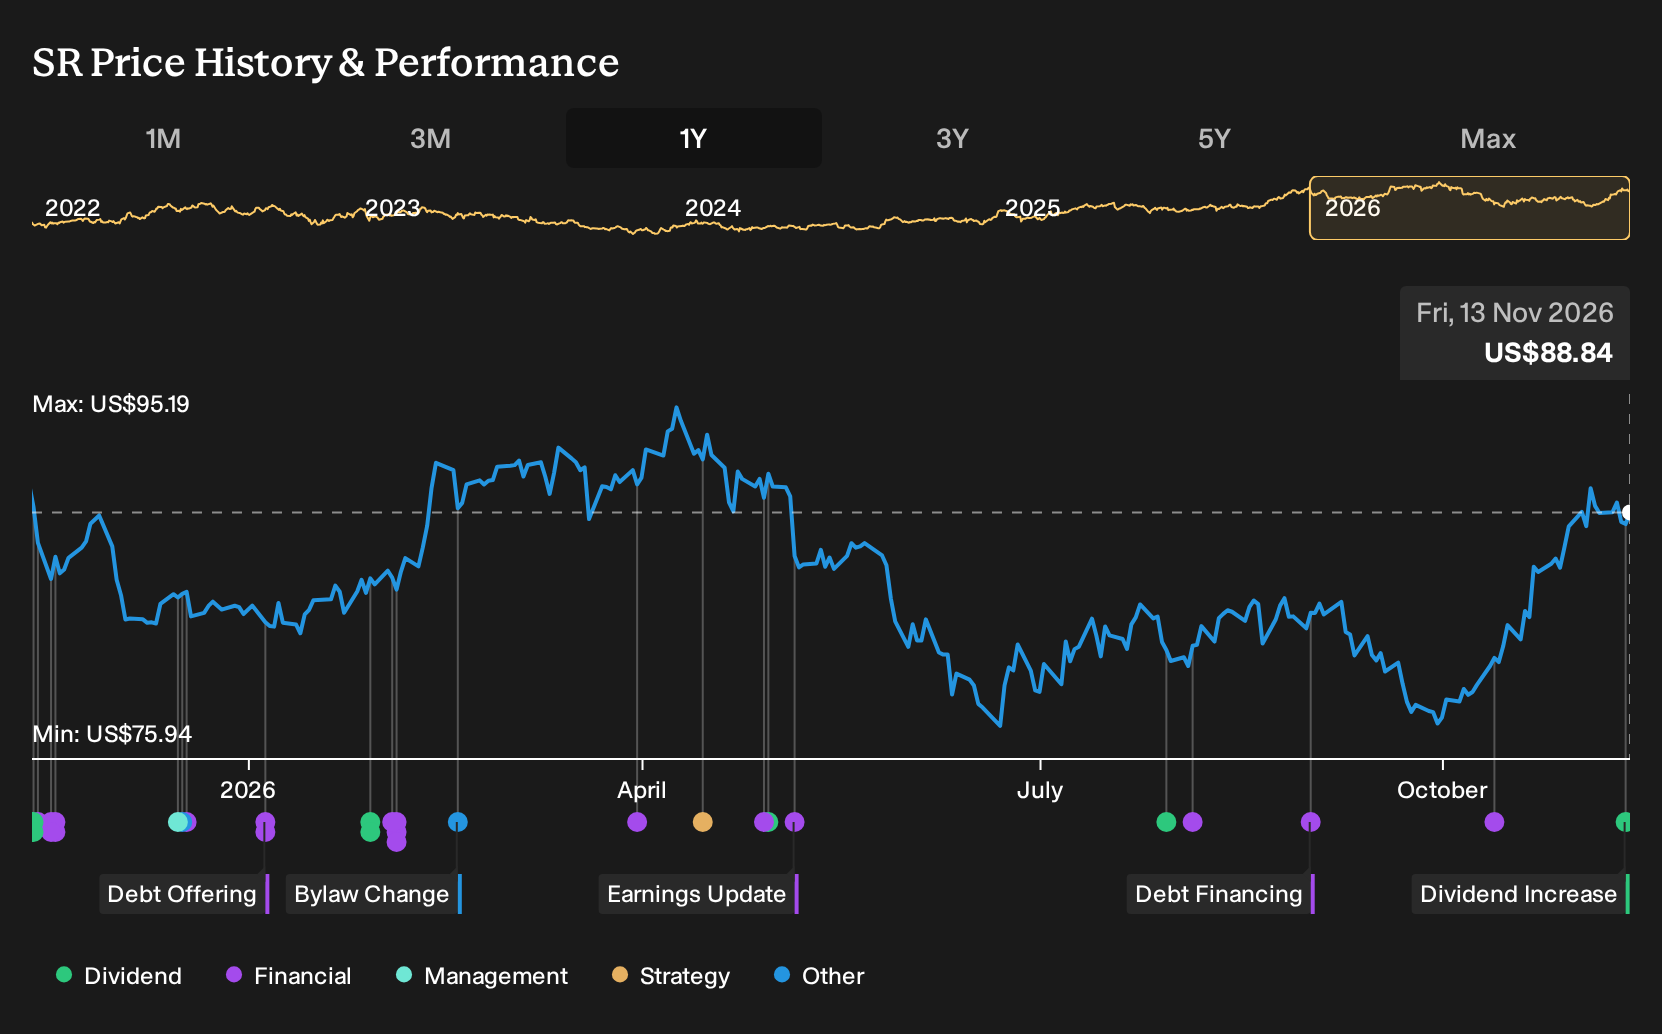
- Spire increased its annual common stock dividend to US$3.46 per share from US$3.30, lifting the quarterly payout to US$0.865, with the higher dividend paid to shareholders of record as of December 11, 2026.
- This latest raise extends Spire’s multi decade record of regular cash dividends and signals ongoing board support for returning capital to investors through income.
- We will look at how Spire’s higher dividend payout interacts with its regulated utility growth plan and long term capital commitments.
Look beyond Spire’s dividend move and evaluate other income focused utilities with solid fundamentals using our curated list of 6 dividend fortresses.
Spire Investment Narrative Recap
For an investor in Spire, the core belief is that a regulated gas utility model with a growing rate base and refined regulatory mechanisms can keep earnings and cash flows relatively steady while capital spending stays high. The analyst consensus Narrative on Simply Wall St expects that to depend on regulators continuing to support the US$11.2b long term capital plan across key jurisdictions.
The latest dividend lift to US$3.46 a share fits that story if earnings keep tracking with capital deployed. On its own, the raise does not materially change the near term catalyst. The main focus remains execution on the Piedmont Tennessee integration and the 2026 capex program, while the biggest risk remains policy and customer pressure on long term gas demand.
The fresh dividend increase, a 4.8% bump in the quarterly rate to US$0.865, is the most directly relevant announcement for income focused investors watching Spire. Management has a long history of regular payments and the firm aims to return a material share of profits via dividends, although free cash flow coverage is flagged as tight.
That higher cash payout leans on the same engine that underpins the analyst consensus Narrative on Simply Wall St, namely growth in the regulated asset base, more customers from Piedmont Tennessee and tools like Missouri weather accounting and formula mechanisms in Alabama and Tennessee. The key watchpoints now are regulatory decisions, funding costs and how quickly new investments convert into earnings that comfortably cover both interest and this larger dividend.
Spire's narrative projects US$3.4b revenue and US$386.0m earnings by 2029. That profile lines up with analysts assuming 8.5% yearly revenue growth and an earnings increase of about US$117m from current earnings of US$268.8m.
Uncover why Spire's fair value indicates a 3% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Community members on Simply Wall St set fair value estimates for Spire between about US$85.35 and US$91.40, across 2 separate views, so you are seeing a fairly tight cluster rather than outliers. Those opinions sit alongside risks around electrification and regulation, which could reshape long term gas demand and earnings resilience.
Explore another Spire fair value estimate, including one that suggests it could be worth just $85.35.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Spire research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Spire. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Spire's overall financial health at a glance.
Looking for more investment ideas beyond Spire?
Once you have a view on Spire, it can help to set it alongside a wider watchlist of potential opportunities, filtered for the traits you care about most.
- If you want potential value ideas with quality fundamentals, start by scanning our 32 high quality undervalued stocks and see which companies match your preferred mix of strength and price.
- For investors who care most about resilience, focus on our 31 resilient stocks with low risk scores to find businesses that score well on stability and financial risk checks.
- To broaden your watchlist with lesser known opportunities, cast a wider net using our 20 high quality undiscovered gems that already show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com