


IQVIA Holdings (IQV) has drawn fresh attention after its shares climbed nearly 59% over the past six months, significantly outpacing both its industry peers and the broader equity market.
That surge sits on top of a 17.6% year to date share price return and a 20.2% total shareholder return over the past year, even though the stock has eased around 2% over the last week as the recent momentum cools slightly.
Scan other healthcare and AI driven contractors showing similar momentum with our curated list of 36 healthcare AI stocks as you assess IQVIA Holdings in context.
After a 59% six month surge, IQVIA Holdings still trades at a discount to both intrinsic estimates and analyst targets. Is that a bargain, or a warning that the market’s caution is on to something?
Most Popular Narrative: 15% Undervalued
IQVIA Holdings closed at $265.12, while the analyst consensus Narrative on Simply Wall St estimates fair value at $311.89 using an 8.8% discount rate. That gap frames the next question: whether the underlying business case really backs up that valuation work.
The main thing that has to go right is that IQVIA Holdings continues to convert strong R&DS bookings, a large backlog and growing Commercial Solutions activity, including with emerging biopharma customers, into sustained revenue and earnings growth despite margin and debt headwinds.
The numbers imply the current share price already reflects a fairly valued, bullish view on IQVIA Holdings. Investors are paying for continued AI-led differentiation, solid backlog visibility and consistent execution rather than a distressed or high-growth scenario.
See why 19 investors see IQVIA Holdings as 15% undervalued.
Result: Fair Value of $311.89 (UNDERVALUED)
Still, IQVIA Holdings faces live threats if client pricing pressure persists or if large pharma customers shift more AI driven data work in house.
Find out about the key risks to this IQVIA Holdings narrative.
Another View: What IQVIA Holdings Looks Like On Earnings
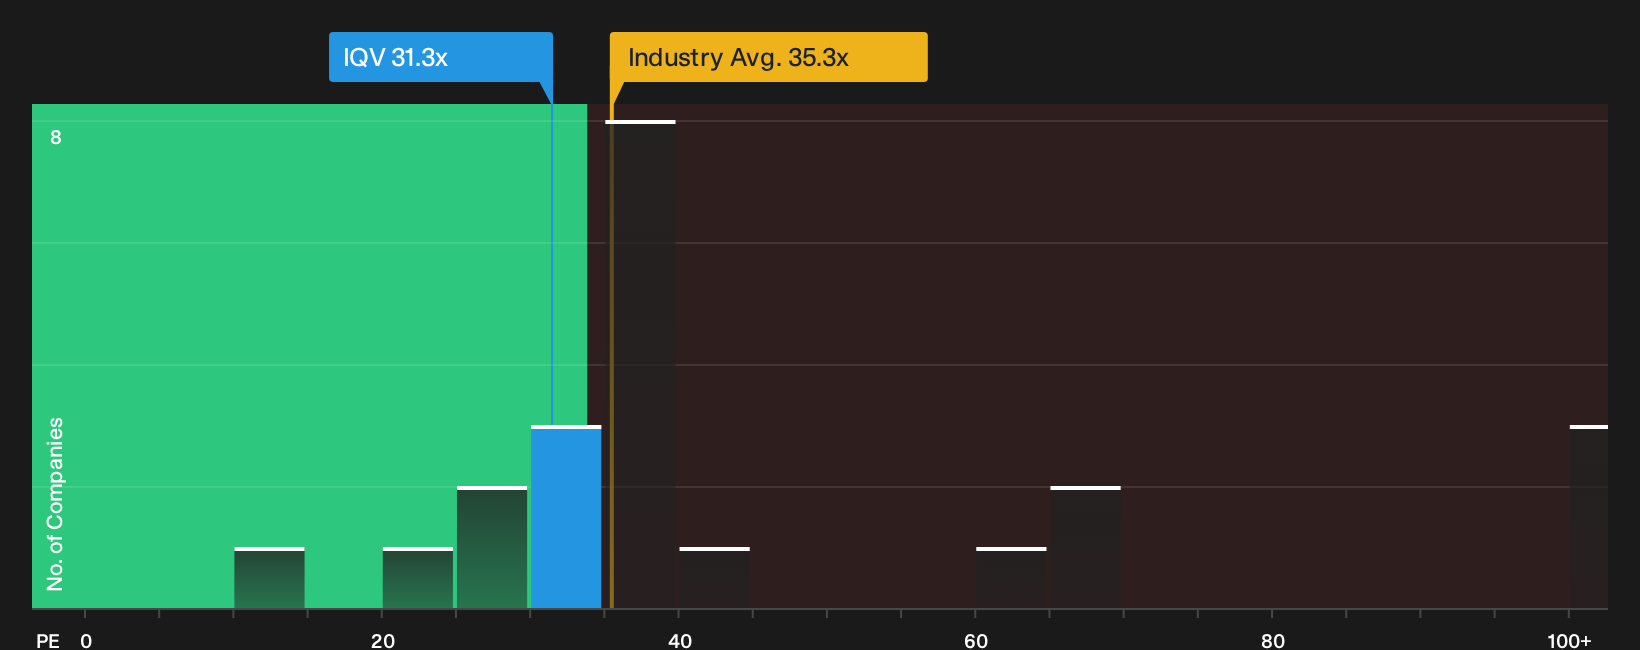
The SWS DCF model points to IQVIA Holdings trading at a discount to its future cash flow value, yet the P/E picture looks tighter. The stock trades on 31.3x earnings versus a fair ratio of 30.5x, above that fair line but below both global life sciences peers at 35.4x and a narrower peer set at 37.9x. That mix of relative value and fair ratio premium leaves a simple question for investors: Is this a margin of safety or a signal that expectations already run hot?
For a closer look at how that earnings based view stacks up against cash flow estimates, and how sensitive it is to small changes in assumptions, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Short term momentum feels strong, yet the real story around IQVIA Holdings sits in the mix of concerns and positives investors are weighing right now. If you want to move quickly and ground your own view in the underlying data, start with the full rundown of 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond IQVIA Holdings?
If you stop with IQVIA Holdings, you risk missing other opportunities that fit your goals just as well or even better on key fundamentals.
- Spot potential mispricing early and scan a curated range of opportunities using the 20 high quality undiscovered gems.
- Strengthen your downside protection by focusing on companies with healthier finances through the list of solid balance sheet and fundamentals (24 results).
- Target a mix of income and resilience by filtering for reliable payers via the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com