


AAR (AIR) has drawn fresh attention after signing a multi-year agreement with Airbus Avionics that covers the full portfolio of Airbus radome repairs across the Asia Pacific region, excluding China.
Recent trading reflects that mixed picture. AAR’s share price has risen 11.70% over the past month but declined 25.36% over the last 90 days, while a 28.38% year to date share price return and 32.53% one year total shareholder return point to longer term momentum building behind the story.
Spot similar aerospace and defense momentum by scanning the curated 31 resilient stocks with low risk scores, which aims to pair operational resilience with steadier return profiles.AAR looks like a solid aviation services platform with fresh Airbus work in hand and a long run of shareholder gains behind it. After the sharp pullback over 90 days, the question for investors is whether that strength is available at a reasonable price.
Most Popular Narrative: 30% Undervalued
AAR’s last close at $108.42 sits well below the $154.50 fair value implied in the analyst consensus Narrative on Simply Wall St. That gap is tied to earnings and margin assumptions that reach out to 2029 using an 8.52% discount rate.
The planned acquisition of a 65% stake in MRO Holdings, which is expected to add about US$1.0b of sales, US$285 million of EBITDA and around US$200 million of operating cash flow in calendar 2026, alongside targeted US$75 million of run rate cost synergies and a medium term margin goal of 19% to 20%, creates a larger integrated MRO platform that could lift AAR’s consolidated revenue, EBITDA margin and cash generation.
See why 12 investors see AAR as 30% undervalued.
Result: Fair Value of $154.50 (UNDERVALUED)
Still, AAR’s story could change quickly if the planned MRO Holdings deal brings higher leverage without stronger cash generation, or if Repair, Engineering and Software margins continue to slide.
Find out about the key risks to this AAR narrative.
Another View: DCF Points The Other Way
A second lens on AAR comes from the SWS DCF model, which puts fair value at $76.83. With the share price at $108.42, this framework sees the stock as overvalued, in clear contrast to the $154.50 analyst fair value. Readers can compare the underlying assumptions and decide which framework aligns more closely with their own view.
For readers who want to unpack how this cash flow view is built and stress test those inputs against their own expectations, Look into how the SWS DCF model arrives at its fair value.
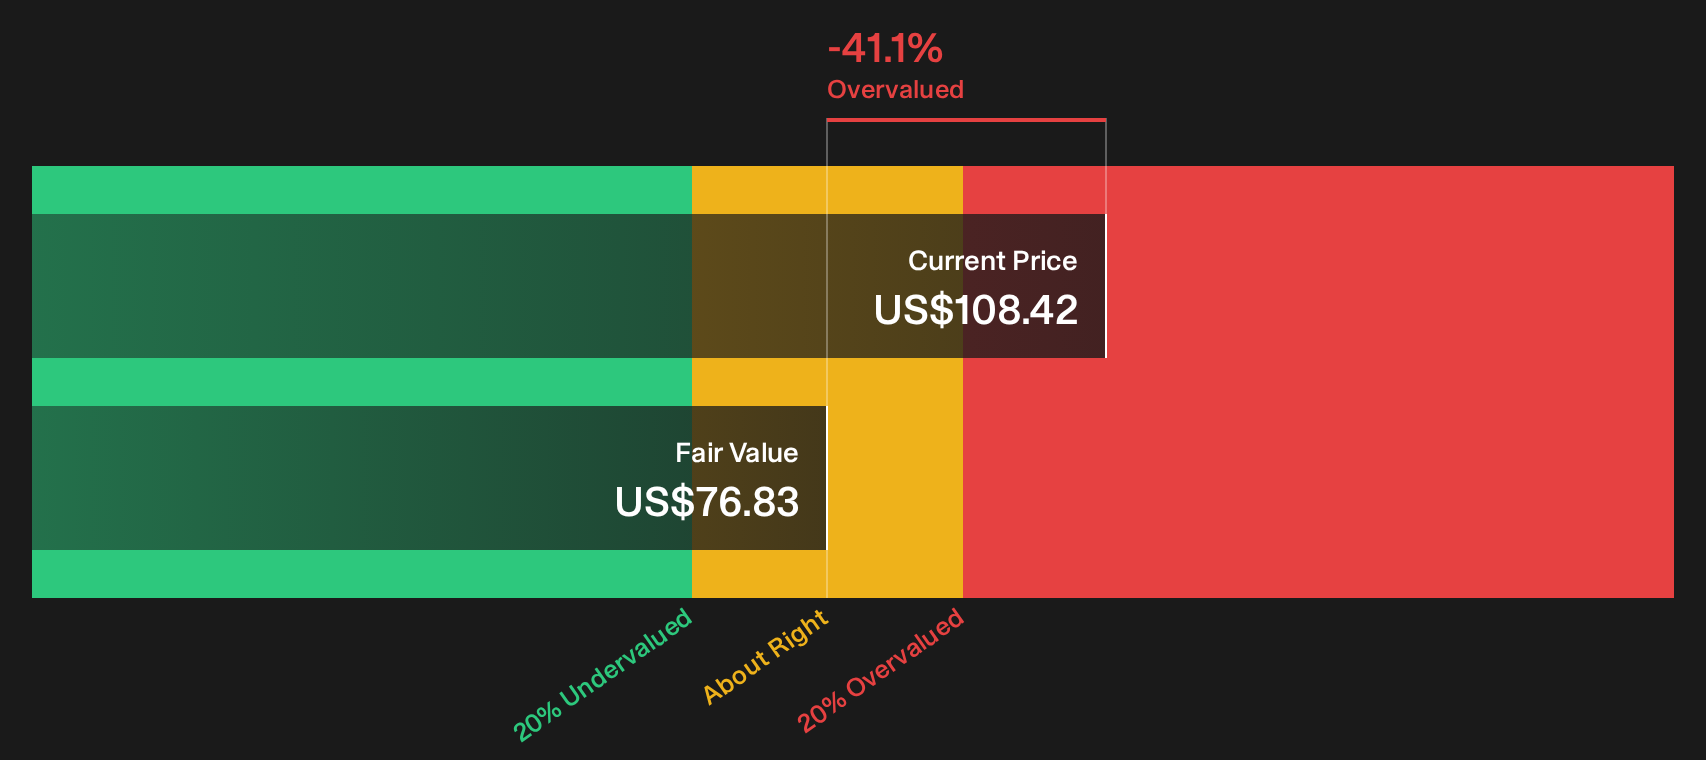
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AAR for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or a clear setup for AAR? Act while the data is fresh, weigh the upsides against the red flags, and start by reviewing 5 key rewards and 2 important warning signs.
Looking for more AAR style investment ideas?
If you are weighing AAR today, broaden your watchlist with fresh ideas sourced from data driven screeners that surface quality, income, and resilience in one place.
- Target potential mispricings by scanning the 32 high quality undervalued stocks that filters for quality fundamentals at prices that may not fully reflect them.
- Strengthen your income stream by reviewing the 6 dividend fortresses focused on companies combining higher yields with consistent payout histories.
- Guard your downside by checking the list of solid balance sheet and fundamentals (24 results) so you are not caught out by weak financial foundations when conditions turn.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com