


Victory Capital Holdings (VCTR) drew fresh attention after releasing third quarter results and affirming its regular dividend, combining steady earnings per share with ongoing cash returns to shareholders.
At a latest share price of $125.26, Victory Capital Holdings has ridden a strong run, with a year to date share price return of 95.41% and a 1 year total shareholder return of 102.78%. The 3 year total shareholder return of about 3x hints at sustained investor enthusiasm that recent earnings and the affirmed dividend appear to have reinforced.
Scan how Victory Capital Holdings compares to other asset managers rewarding shareholders with cash returns by reviewing our curated list of 6 dividend fortresses in the current market.
Victory Capital Holdings now combines a sharp run in the share price with stable recent earnings and a regular dividend. The real tension is whether that strength is already fully reflected in today’s valuation.
Most Popular Narrative: 3% Undervalued
Against a last close of $125.26, the analyst consensus Narrative on Simply Wall St points to a fair value around $129.33, which implies Victory Capital Holdings trades at a small discount while investors weigh acquisition risk against earnings potential.
Victory Capital Holdings is pursuing the acquisition of First Eagle Investments for about US$7b. This transaction is expected to add roughly US$3.2b in annual revenue and expand the combined asset base to around US$571b, creating scope for a larger earnings pool once integrated and contributing to future EPS.
See why 52 investors see Victory Capital Holdings as 3% undervalued.
Result: Fair Value of $129.33 (UNDERVALUED)
Still, the Victory Capital Holdings story could change quickly if the First Eagle integration delivers fewer cost savings than planned or if higher leverage starts to bite in weaker markets.
Find out about the key risks to this Victory Capital Holdings narrative.
Another View: Victory Capital Holdings Through A Cash Flow Lens
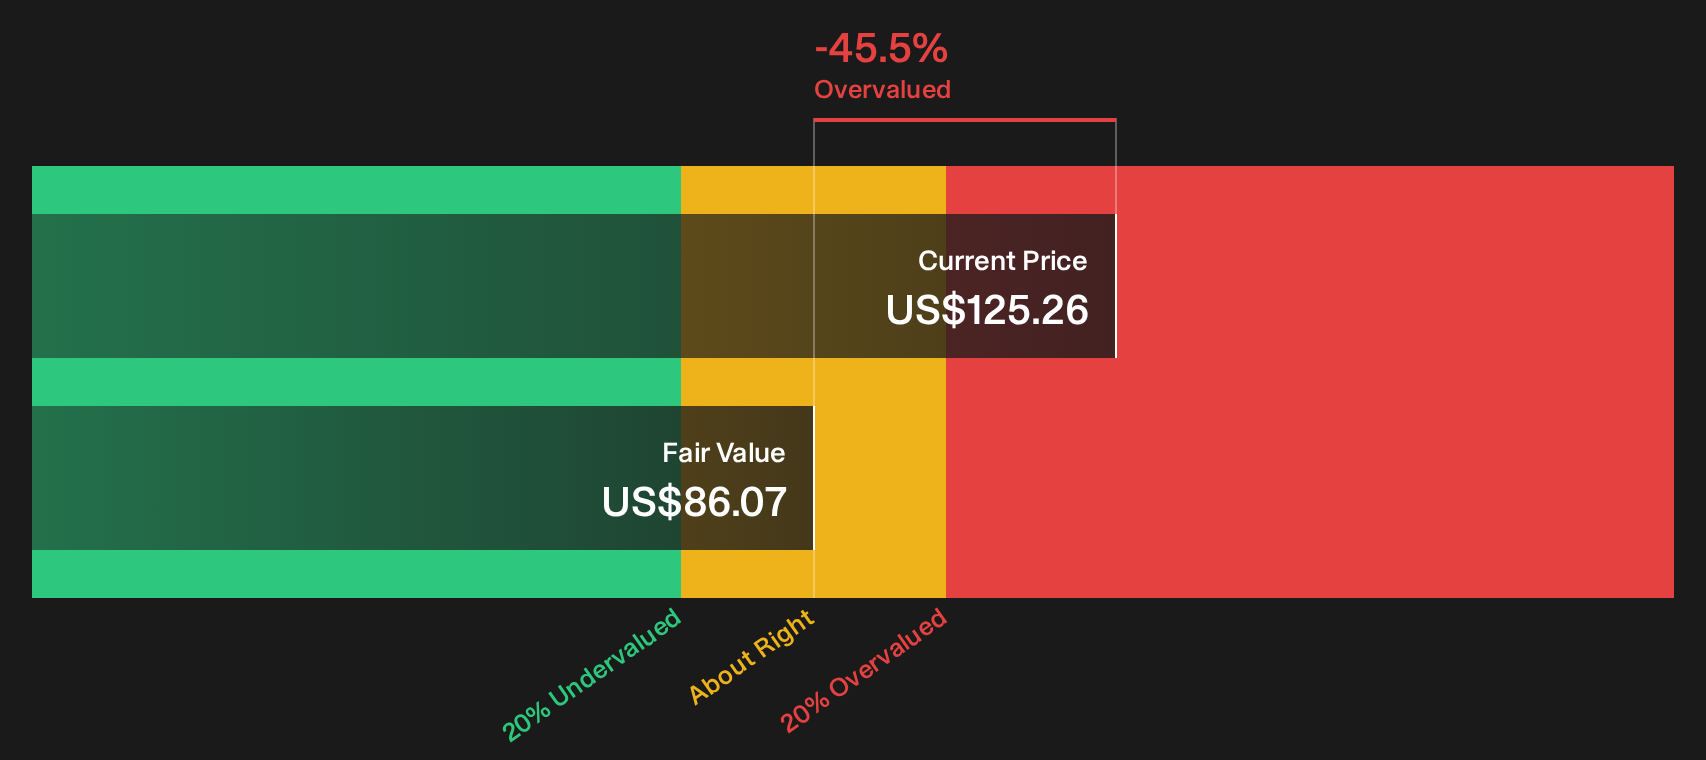
While the analyst Narrative tags Victory Capital Holdings as modestly undervalued around a $129.33 fair value, the Simply Wall St DCF model paints a tougher picture. On that measure, the stock at $125.26 trades well above an estimated future cash flow value of $86.07, which appears closer to overvalued than cheap and raises a simple question for investors: Which story do you trust more, the earnings multiples or the cash flows?
For a closer look at how the numbers are built up in practice, review how the SWS DCF model treats Victory Capital Holdings through Look into how the SWS DCF model arrives at its fair value.. You can then compare this with the analyst target and your own expectations for margins, deal integration and leverage.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Victory Capital Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Curious whether the mixed signals around Victory Capital Holdings lean closer to opportunity or risk for your portfolio today, and keen to firm up your own stance quickly? Take a closer look at the 3 key rewards.
Looking for more investment ideas beyond Victory Capital Holdings?
If Victory Capital Holdings has sharpened your focus on quality, do not stop here. Broaden your watchlist with fresh ideas that could suit very different playbooks.
- Target potential mispricings and hunt for quality businesses that might trade below what their fundamentals suggest by reviewing our curated 32 high quality undervalued stocks.
- Prioritise resilience in tougher markets and zero in on enterprises with strong finances through the focused list of solid balance sheet and fundamentals (24 results).
- Get in early on lesser-known opportunities and scan a focused universe of stronger prospects using the dedicated 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com