


Keurig Dr Pepper has climbed 38.2% over the past year, even as investors digest fresh equity issuance, a major acquisition and plans to split the group in two. With the stock recently closing at US$36.34, the question now is whether that price still lines up with what its earnings can support.
- The 38.2% one year gain asks you to decide whether Keurig Dr Pepper’s current earnings power justifies paying a much higher price than a year ago.
- The US$2b share offering, aimed at reducing debt and preparing for a 2027 separation, may shift how much of today’s earnings can ultimately flow to equity holders over time.
- Your read on Keurig Dr Pepper is one view; the desks covering it have another. See what analysts think Keurig Dr Pepper's shares could be worth.
The issue now is whether Keurig Dr Pepper’s current share price is well supported by the earnings investors are paying for today.
If you want a broader starting point for research around Keurig Dr Pepper’s latest move, you can apply the same earnings-focused lens to 32 high quality undervalued stocks.
Has Keurig Dr Pepper Run Too Far on Earnings?
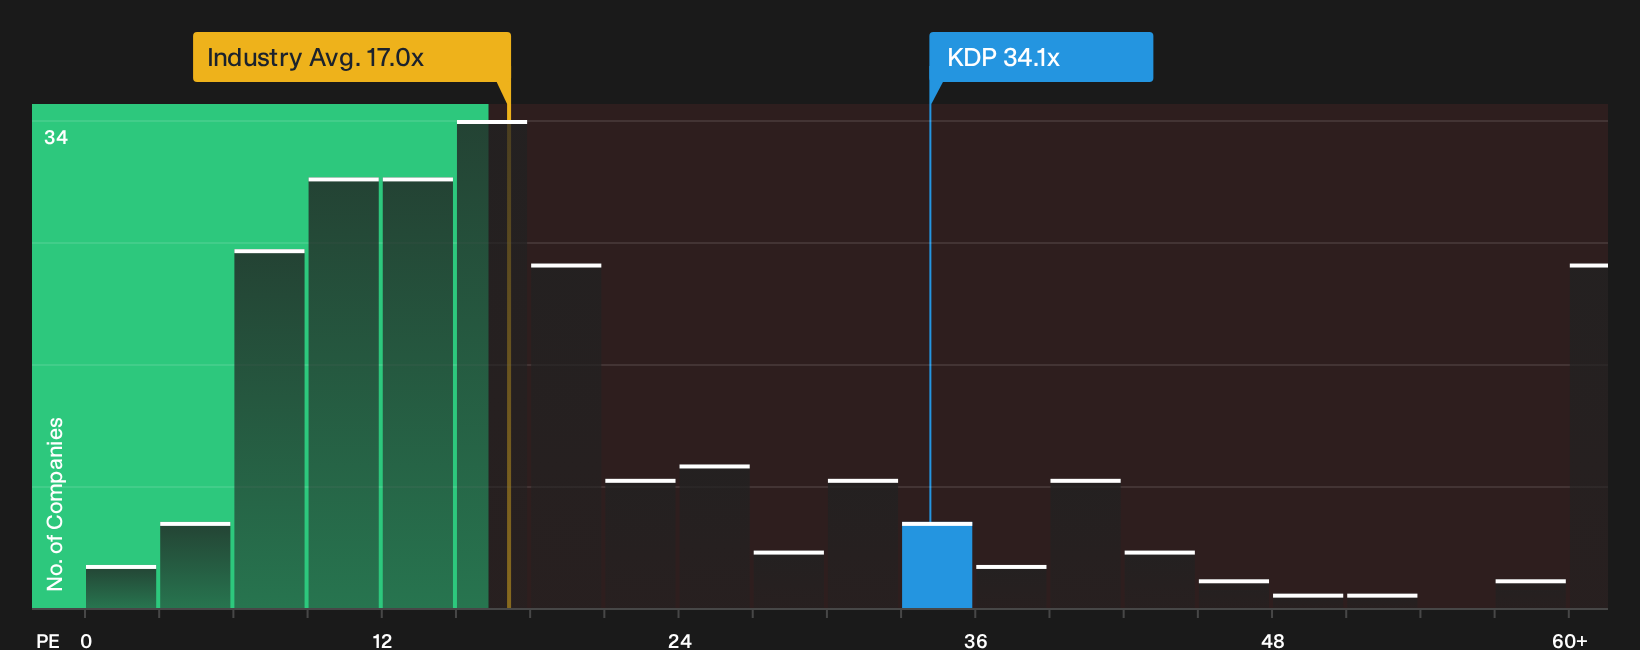
P/E fits Keurig Dr Pepper because earnings still sit at the center of how investors judge a branded beverages group with both coffee and soft drinks under one roof. On this lens, the stock changes hands at about 34.1x earnings, compared with roughly 17.0x for the broader Beverage industry and about 26.0x for closer peers, so you are paying a clear premium for each dollar of profit today.
That gap looks even starker once you factor in the tailored fair P/E that blends Keurig Dr Pepper’s growth profile, margins, scale and risk, since the current 34.1x sits above that mark and screens as overvalued on this framework. The rich multiple also comes in the wake of the US$2b equity offering to cut debt ahead of the 2027 split. This means the market is attaching a full price to the stock despite dilution and the extra complexity of the planned separation. Explore the numbers behind Keurig Dr Pepper's P/E valuation.
The Keurig Dr Pepper Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E puzzle for Keurig Dr Pepper leaves off by spelling out which combinations of future growth, profitability and earnings power would need to materialise for the stock to be worth meaningfully more or less than today’s price. Each scenario ties a fair value estimate to a specific mix of potential catalysts and risks, so you can track over time which version of Keurig Dr Pepper's story appears to be unfolding on Simply Wall St's Community page.
One of the top narratives on Keurig Dr Pepper: roughly fairly valued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The current valuation and research views imply that the market is still pricing Keurig Dr Pepper shares below what a successful separation and delivery on beverage and coffee earnings targets could justify..."
Discover why this Narrative puts Keurig Dr Pepper at roughly fairly valued.
Keurig Dr Pepper’s valuation is only part of the story
Price and P/E tell one story about Keurig Dr Pepper, but the research flags specific pressure points in the background that could matter just as much to long term shareholders. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com