


NewMarket (NEU) has lifted its quarterly dividend by 8% to US$3.25 per share, a move that puts income and valuation firmly back on investors’ radar.
Recent trading has been choppy for NewMarket, with the share price falling 20.3% over the past 30 days and 26.3% over 90 days, even though the year to date share price return is still up 3.1% and the 5 year total shareholder return is 125.8%. This points to long term momentum but fading near term enthusiasm as investors reassess valuation and risk after a strong multi year run.
Scan beyond NewMarket and compare this dividend story with other hand picked income ideas in the 6 dividend fortresses list.
NewMarket now offers a higher cash payout just as the share price has pulled back hard from its highs. Is this a sign that some upside remains, or evidence that most of the easy gains are already behind it?
Preferred P/E of 14.3x: Is it justified?
NewMarket now trades on a P/E of 14.3x while the last close sits at $709.19, which lines up with a valuation profile that looks restrained compared with peers in the Chemicals sector.
The P/E ratio compares what investors are willing to pay for each dollar of current earnings. For a specialist in petroleum additives with a long operating history and global reach, that earnings multiple becomes a quick shorthand for how the market is weighing its profit engine against listed competitors.
Earnings for NewMarket grew 2% over the past year and have risen by 16.2% per year over the past 5 years, with current net profit margins at 16.4%. That backdrop, together with a Return on Equity of 23.7% that is considered high, implies the current P/E reflects a business that has supported solid profitability over time rather than one being priced purely on hope.
Compared to both the US Chemicals industry average P/E of 23.3x and a peer average of 22.1x, NewMarket trades at a clear discount. The stock therefore carries a lower earnings multiple than many sector rivals even though recent earnings growth has outpaced the broader Chemicals group over the past year.
Result: Price-to-Earnings of 14.3x (UNDERVALUED)
See what the numbers say about this price — find out in our valuation breakdown.
Still, the NewMarket story can be knocked off course by weaker demand for petroleum additives or by regulatory shifts that pressure fuel and lubricant markets.
Find out about the key risks to this NewMarket narrative.
Another View: DCF Says NewMarket Looks Cheaper
The earnings multiple paints NewMarket as restrained, but the SWS DCF model tells a stronger value story. At $709.19, the stock trades about 38.6% below an estimated future cash flow value of $1,155.35. This frames the recent selloff as a potential mispricing rather than just fading enthusiasm.
That is a big gap in anyone’s playbook. The question is whether you trust the cleaner, cash flow driven lens more than a simple earnings multiple that is set by a cautious market.
Look into how the SWS DCF model arrives at its fair value.
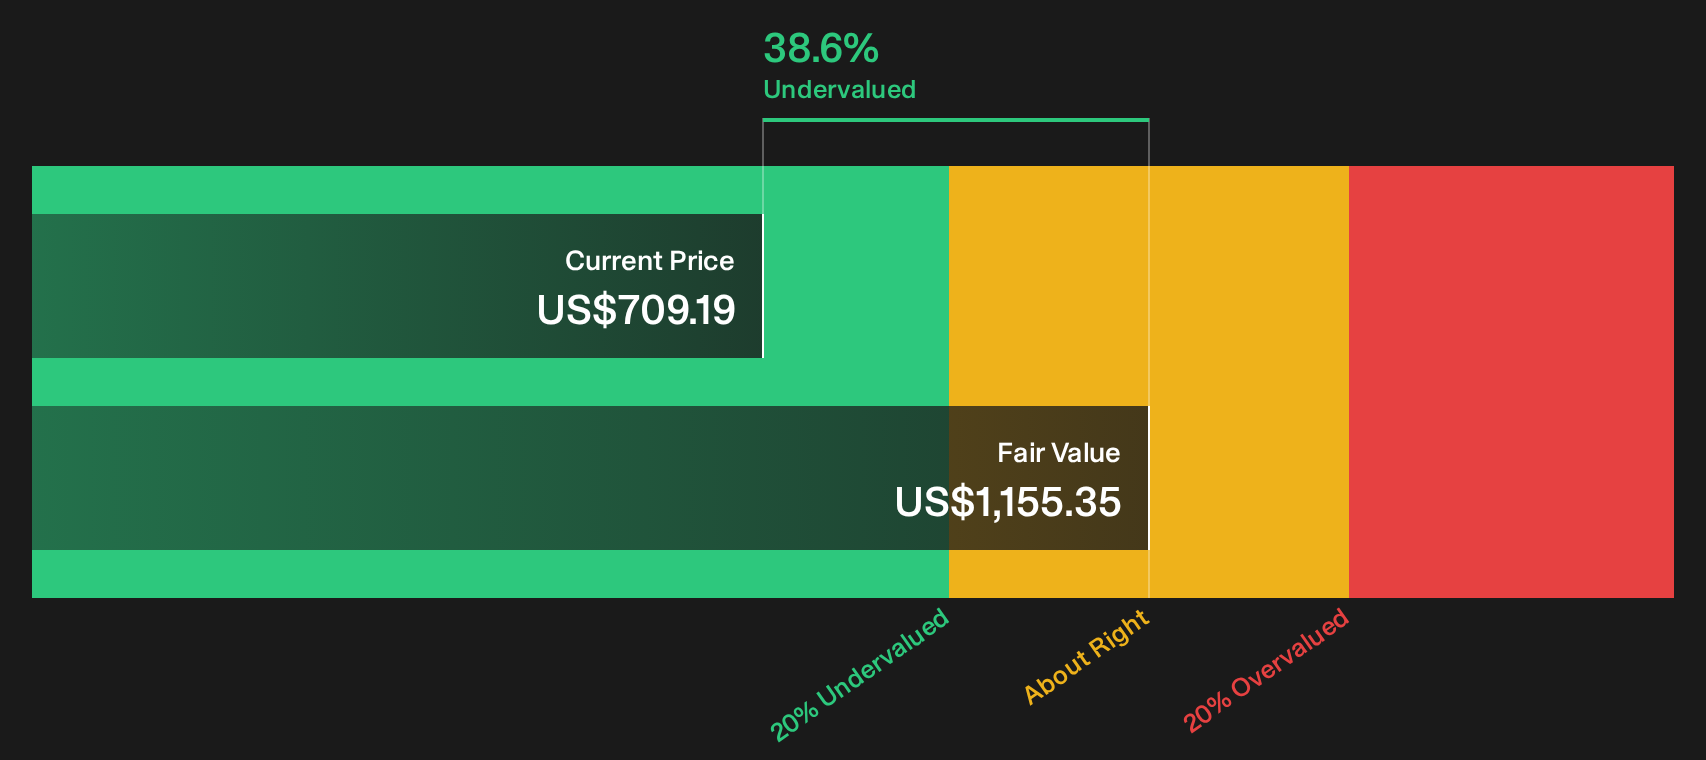
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out NewMarket for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 32 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Is the tone of this NewMarket story too cautious or not cautious enough? Move quickly, review the numbers yourself, and pressure test every assumption in the full breakdown of 3 key rewards.
Looking for more NewMarket style investment ideas?
If NewMarket has your attention, do not stop there. Use the Simply Wall Street Screener to spot other opportunities with income, quality and potential upside aligned.
- Target resilient cash generators by reviewing companies with strong balance sheets and fundamentals in the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced opportunities by scanning companies that flag as 32 high quality undervalued stocks before the crowd catches on.
- Prioritise income today by focusing on reliable payers in the 6 dividend fortresses list before yields move.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com