


AI related infrastructure is driving a large share of global trade growth in 2025 and 2026, even as tariffs reshape old trade routes. That kind of demand can reward businesses that grow quickly and whose leaders keep serious skin in the game through sizeable shareholdings. This piece breaks down three fast growing, high insider ownership stocks from our screener that fit that profile and may merit a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily invested alongside you. However, if you want the absolute best, these 371 high growth high conviction stocks are the cream of the crop.
CoreWeave (CRWV)
Overview: CoreWeave is a cloud infrastructure provider that supplies GPU compute and managed AI tools so developers can run large-scale AI workloads.
Market Cap: US$31.48b
CoreWeave matters for this fast-growth, high insider ownership theme because its GPU-heavy cloud platform directly powers AI workloads that analysts expect to scale rapidly. WIn2026, an investor in the Simply Wall St Community, argues the business model comes with very specific rewards and stresses that you need to understand.
"The business model appears to be an extremely capital-intensive leasing play, acting as a high-leverage buffer that shifts depreciation and technical obsolescence risks entirely onto CRWV."
How this pressure interacts with future AI demand, customer contracts, and funding costs could heavily sway CoreWeave’s margins and growth runway.
Those margin swings are exactly what the full narrative for CoreWeave unpacks, showing where CoreWeave’s capital intensity could either compress returns or accelerate an overlooked upside path.

Tesla (TSLA)
Overview: Tesla builds and sells electric vehicles, energy storage systems, and related services in the transportation industry.
Operations: Tesla generates about US$91.3b from Automotive and US$12.3b from Energy Generation and Storage, mostly in the United States, China, and other international markets.
Market Cap: US$1,571.0b
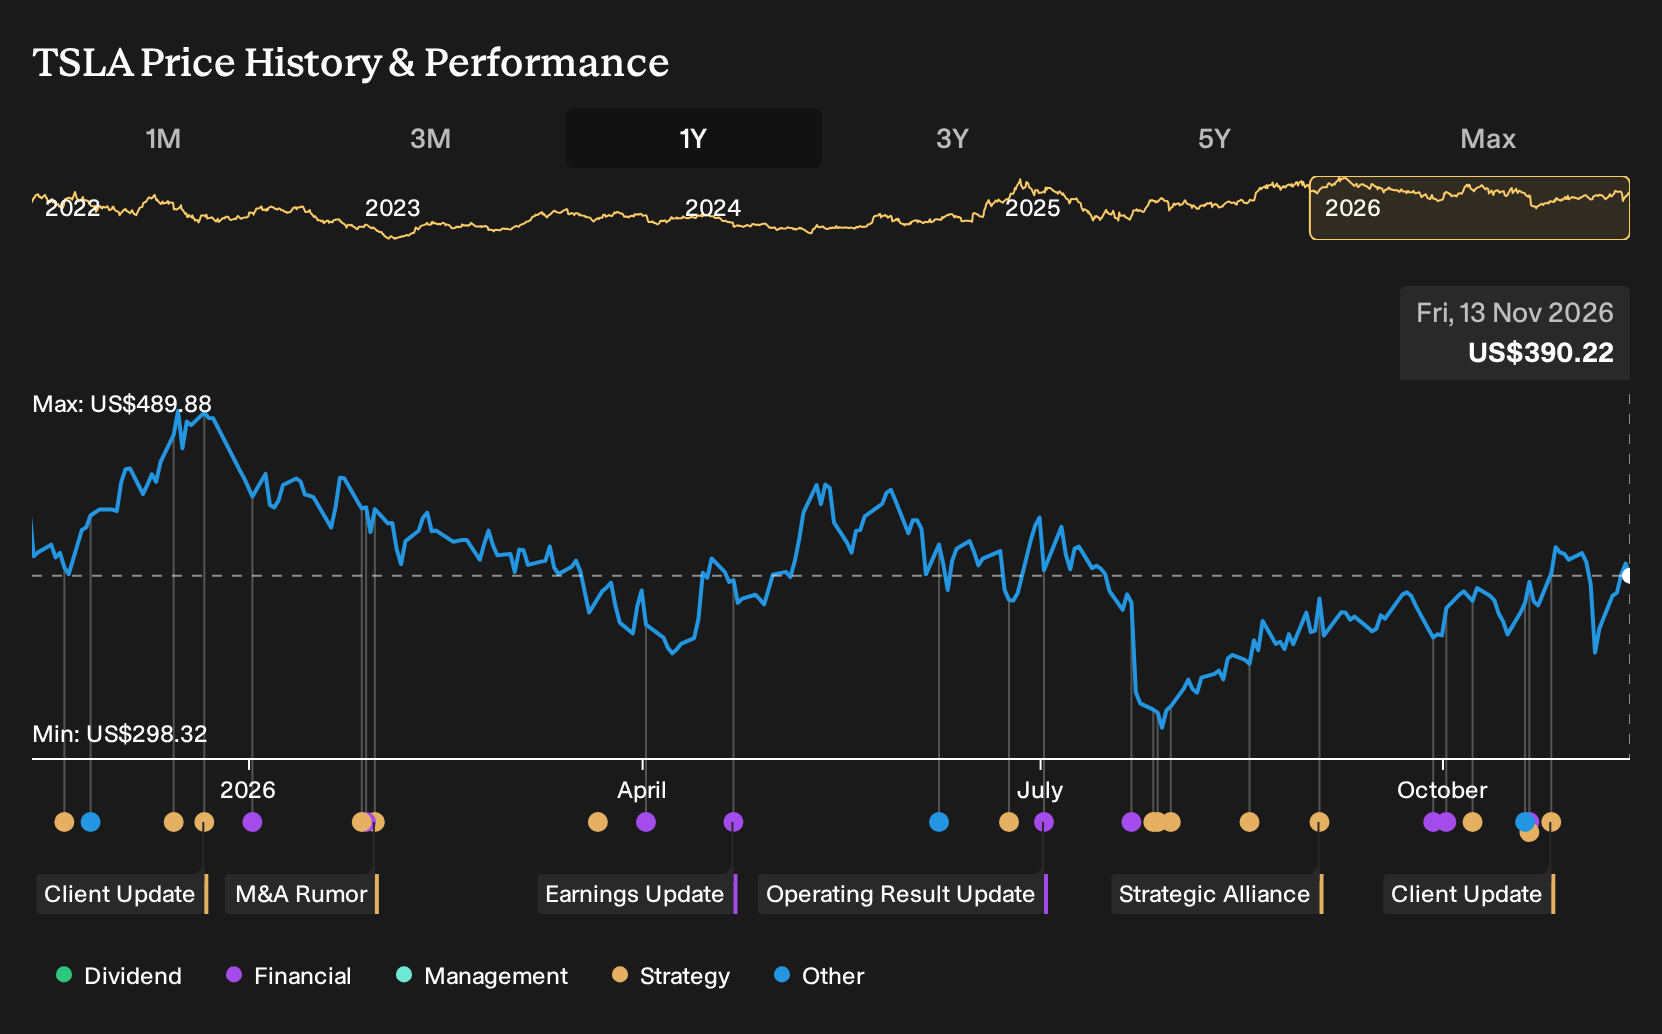
Tesla is included in this high insider ownership theme because its EV line is central to its business strategy, and according to Robbo, an investor in the Simply Wall St Community, that hardware base is what makes its activities in software, autonomy, and energy notable.
"Tesla is pursuing a range of ambitious and, in some cases, speculative opportunities: AI leadership, robotaxis, humanoid robotics, and battery storage."
One question is what might happen to Tesla’s growth path if an unexpected pressure on profitability coincides with its longer-term autonomy and AI projects.
If that timing risk is what you care about, the full narrative for Tesla explains in more detail where Tesla’s next leg of growth could accelerate or stall.
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops semiconductor test equipment such as probe cards and wafer probers, alongside body-measuring and LCD inspection tools worldwide.
Operations: Micronics Japan generates about ¥84,868 million from its Probe Card Business and ¥1,391 million from its TE Business across Asia, Europe, and America.
Market Cap: ¥414 billion
Micronics Japan is connected to this fast-growing, high insider ownership theme through its semiconductor test gear, with earnings up 89.4% and forecasts indicating roughly 25% yearly earnings expansion, supported by rising index visibility and upcoming results that could change significantly if one unseen pressure alters the trajectory of demand across its probe card line.
If that unseen pressure is what you are focused on, the 2 key rewards and 1 important major warning sign shows how Micronics Japan’s growth story could either compound or get capped quickly.

Seeking Fresh Alternatives Before They Fly
New themes gain momentum while old ideas lose their edge. Catch fresh breakouts and under the radar opportunities before the crowd, while the data still matters, and aim to get in early.
- Spot cash-rich businesses that aim to weather shocks more calmly by reviewing a curated list of solid balance sheet and fundamentals (24 results) that filters for resilient balance sheets and consistent fundamentals.
- Identify structural shifts in AI demand by scanning a focused pool of 53 AI infrastructure stocks that plug into the physical backbone of next generation computing.
- Explore potential income pillars by reviewing a hand picked group of 6 dividend fortresses built around higher yields and balance sheet strength while yields remain elevated.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com