


RBC Bearings has delivered a powerful long term share price run, and the question now is whether the current tag can still be squared with what the business is earning. With the stock recently closing at US$485.55, the key issue for you is how much of those earnings are already reflected in that number.
- Over the past 5 years, RBC Bearings has returned 131.5%, which puts a lot of weight on whether its earnings story can keep carrying that kind of share price outcome.
- The company’s edge in highly engineered bearings and related components can support pricing power and margins, which feeds directly into how durable its earnings base may be.
- The analysts covering RBC Bearings have run their own numbers. See what analysts think RBC Bearings's shares could be worth.
The stock’s next move may depend on whether RBC Bearings’ current earnings profile really justifies where the share price now sits.
If you want more ideas where earnings are front and center in the story, a focused stock screen is a useful next step, starting with our screener containing 20 high quality undiscovered gems.
Is RBC Bearings Getting Expensive on Earnings?
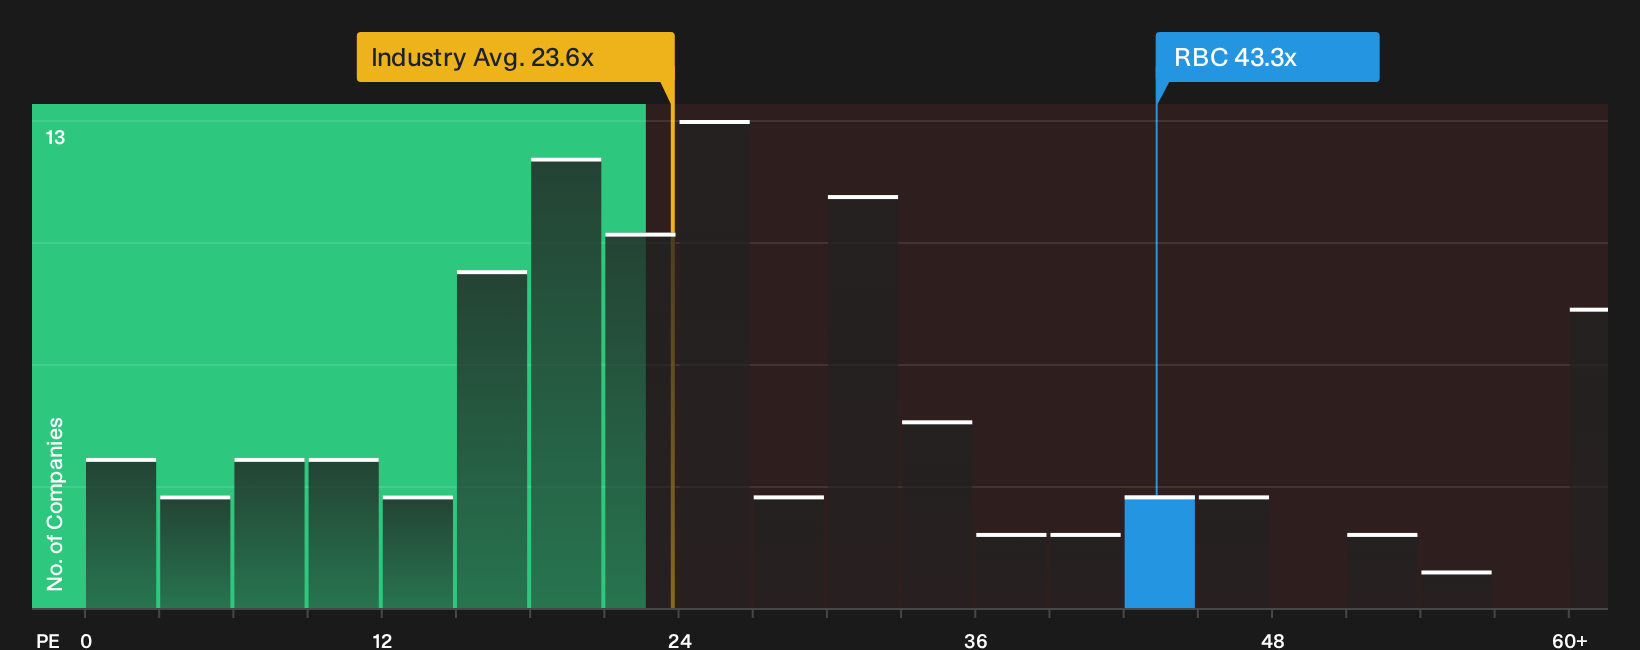
The P/E ratio suits RBC Bearings because earnings are a core driver of how investors frame the story here. On that measure, the stock trades on roughly 43.3x earnings, which is richer than both the machinery industry average of about 23.6x and the peer group around 32.8x. That gap means you are paying a bigger upfront price for each dollar of current profit than you would for many similar industrial businesses.
The tailored fair multiple points to a lower P/E than where RBC Bearings is currently priced, so the shares screen as overvalued on this framework. For that premium to feel comfortable, you would need to believe the company’s earnings quality, growth prospects and resilience justify paying well above broader machinery benchmarks. If that seems like a stretch, the current valuation may look demanding and worth cross checking against other methods before committing fresh capital. Explore the numbers behind RBC Bearings's P/E valuation.
The RBC Bearings Narrative: What Would Justify Today's Price?
RBC Bearings' valuation puzzle only really becomes clear once you map out the specific earnings path that would need to unfold from here. Simply Wall St Narratives act as that bridge, spelling out which assumptions on growth, margins and long term profitability would have to line up for the stock to trade materially higher or lower than today’s level. Instead of a single headline multiple or model output, each narrative lays out its own fair value logic so you can compare those underlying assumptions with actual results as they are reported over time on the Community page.
One of the top narratives on RBC Bearings: 20% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The numbers imply the share price reflects a business that many investors still treat cautiously, even though this narrative views RBC Bearings as undervalued..."
Discover why this Narrative puts RBC Bearings at 20% undervalued.
RBC Bearings' valuation still leaves a crucial leadership question on the table
Before you put too much weight on the numbers alone, it is worth asking how the people steering RBC Bearings are rewarded for the choices they make over the next few years. See who runs RBC Bearings and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com