


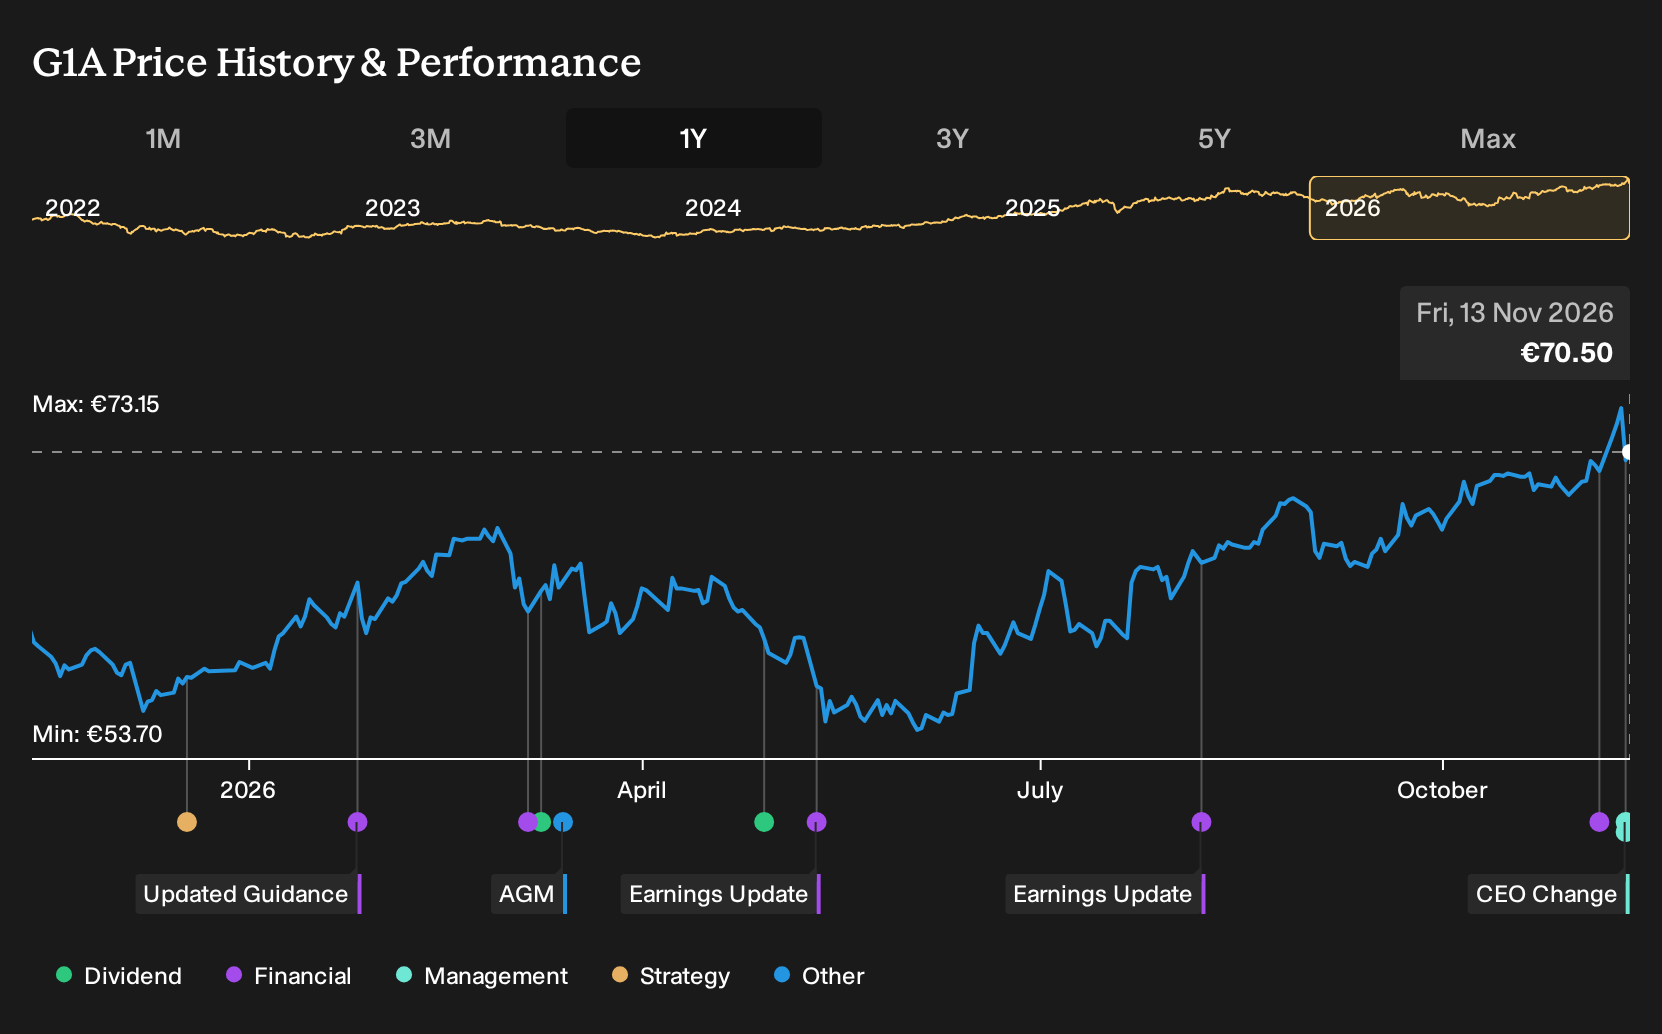
- GEA Group has confirmed that CEO Stefan Klebert will leave the role after the April 2027 AGM, with long-serving executive Klaus Stojentin set to take over and further Executive Board roles reshaped, including the planned appointment of Andreas Seeringer to lead the Nutrition Plant Engineering Division.
- The leadership reshuffle coincides with continued reporting of higher sales and earnings for the first nine months of 2026, meaning investors can weigh the incoming management team against a business that is currently executing on its process equipment and service model across food, dairy and pharma customers.
- We will now see how GEA Group’s existing investment narrative could be affected by this early signalled CEO succession plan.
Scan how GEA Group’s leadership reshuffle and earnings story compares to other industrial players by focusing on 198 high quality undervalued stocks that could be priced for a breakout on cash flow strength.
GEA Group Investment Narrative Recap
For GEA Group, the core belief is that its mix of process equipment and a large service base can keep supporting earnings and cash flow while cost programs such as Mission 30 run their course. The short-term hinge is simple: investors need confidence that order intake in food, dairy and pharma keeps filling the pipeline even as chemicals remain a weaker exposure.
The CEO transition looks carefully staged and does not materially alter the near-term operating catalyst, which is continued execution on guidance for organic sales, margins and returns described in the analyst consensus Narrative on Simply Wall St. The bigger risk is expectation reset. If investors decide Mission 30 gains and high teens margin ambitions are already fully reflected in the current P/E, repricing could follow even if operating targets are met.
The most relevant recent announcement here is the third quarter 2026 report. GEA Group posted €1,461.23m in sales and €128.51m in net income for the quarter, with basic EPS of €0.79. Over the first nine months, sales were €4,176.87m and net profit reached €350.02m, with basic EPS of €2.15 from continuing operations.
These figures provide a concrete run rate to judge whether the incoming leadership can keep delivering on the Mission 30 and service growth storyline analysts describe. If margins, service revenue and dairy or pharma demand stay aligned with guidance, the CEO handover is more about continuity than disruption. If progress stalls, the existing concerns around valuation, efficiency upside and sector mix move quickly back into focus.
GEA Group's current analyst narrative points to revenues of €6.6b and earnings of €674.7m by 2029, based on forecast yearly revenue growth of 5.6% and a move from €436.9m in earnings today to the 2029 consensus. This implies an earnings increase of about €237.8m.
Discover how GEA Group's fair value is essentially in line with its current price.
Exploring Other Perspectives
For GEA Group, the bullish twist is all about faster earnings expansion. The most optimistic analysts were pencilling in revenue of about €6.9b and earnings of roughly €780.1m by 2029, before this leadership change. You can treat those higher targets as one possible scenario that may be revisited after the CEO reshuffle.
Explore 2 other GEA Group fair value estimates, including one that suggests up to 88% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your GEA Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for GEA Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEA Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond GEA Group?
Once you have a view on GEA Group, the next step is to broaden your watchlist and see how other businesses compare on quality, valuation and resilience. The Simply Wall St Screener can help you quickly filter the market to match the type of opportunities you want to research further.
- If you want steadier candidates that prioritise balance sheet strength, start by reviewing our list of solid balance sheet and fundamentals (198 results) to see which businesses keep debt and liquidity tightly controlled.
- For readers who care most about valuation and cash flow support, scan the 198 high quality undervalued stocks to spot companies that screens suggest may have more fundamental support than their current prices imply.
- If you prefer ideas that are not already crowded, look through the 559 high quality undiscovered gems and focus on companies with solid fundamentals that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com