


Tennant shares have climbed 13.7% over the past month, which puts a spotlight on a simple question for anyone looking at the stock today. Is the current price largely in step with what the business is earning, or has recent enthusiasm moved faster than its profit power?
- The 13.7% gain over the past 30 days raises the stakes on whether Tennant's earnings can carry the higher valuation investors are now paying.
- Recent sales growth and solid order intake suggest revenue and earnings expectations may depend on how effectively Tennant converts this demand into sustained profitability.
- The analysts covering Tennant have run their own numbers. See what analysts think Tennant's shares could be worth.
The issue now is whether Tennant's current share price is justified by the earnings the business is producing today and is expected to generate over time.
If you want more ideas at a similar decision point to Tennant, a focused stock screen can be a useful next step. You may wish to start with 32 high quality undervalued stocks.
Is Tennant Getting Expensive on Earnings?
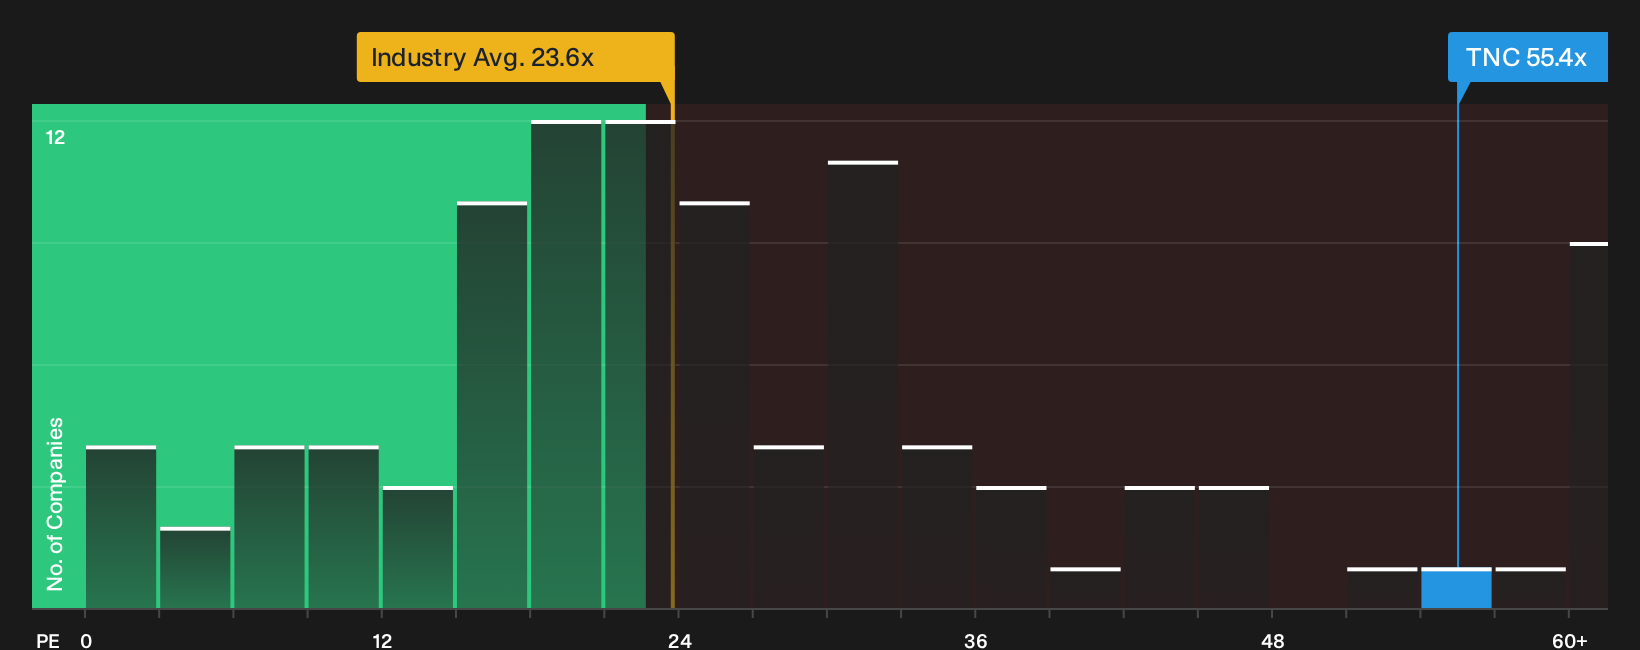
The P/E ratio suits Tennant because earnings remain the main lens investors use to judge how the cleaning equipment business turns sales into profit. Right now the shares trade on a P/E of 55.4x, which is well above the Machinery industry average of 23.6x and also above the peer group average of 39.0x. That gap tells you buyers are paying a premium dollar for each dollar of current profit.
A more tailored fair P/E, which factors in Tennant's growth profile, profitability, size and risk, sits below the current 55.4x, so on this framework the stock screens as overvalued on earnings. Because Tennant just reported third quarter 2026 net sales of US$322.3m and reaffirmed full year guidance, the recent strength in the business already looks heavily reflected in the valuation. For anyone weighing an entry point, the key question is whether Tennant's future profit delivery can justify paying meaningfully more than both peers and that modelled fair multiple today. Explore the numbers behind Tennant's P/E valuation.
The Tennant Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Tennant pick up where the valuation puzzle leaves off and explain which paths for growth, margins and earnings would need to hold for the stock to be worth much more or much less than today’s price on Tennant's Community page. Instead of a single output from a ratio or model, Narratives describe the future that those numbers rely on so you can watch how closely reality tracks the story you are implicitly betting on.
One of the top narratives on Tennant: 12% undervalued
This Narrative is the bearish analyst Narrative on Simply Wall St, built on the most pessimistic analyst price target and forecasts, not one person's view.
"The main thing that has to go right is that Tennant turns its fast-growing robotics and subscription businesses into a higher-margin, recurring revenue engine..."
Discover why this Narrative puts Tennant at 12% undervalued.
Tennant’s price is only one piece of the decision
Before you make a judgment on Tennant based purely on its P/E and earnings story, you also need to understand who is driving those results and how their pay is structured. See who runs Tennant and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com