


- EPAM Systems reported third quarter 2026 sales of US$1,426.43 million and net income of US$130.31 million, issued updated 2026 guidance, disclosed completion of a prior repurchase authorization, and approved a new share buyback program of up to US$1.8 billion running through 2029.
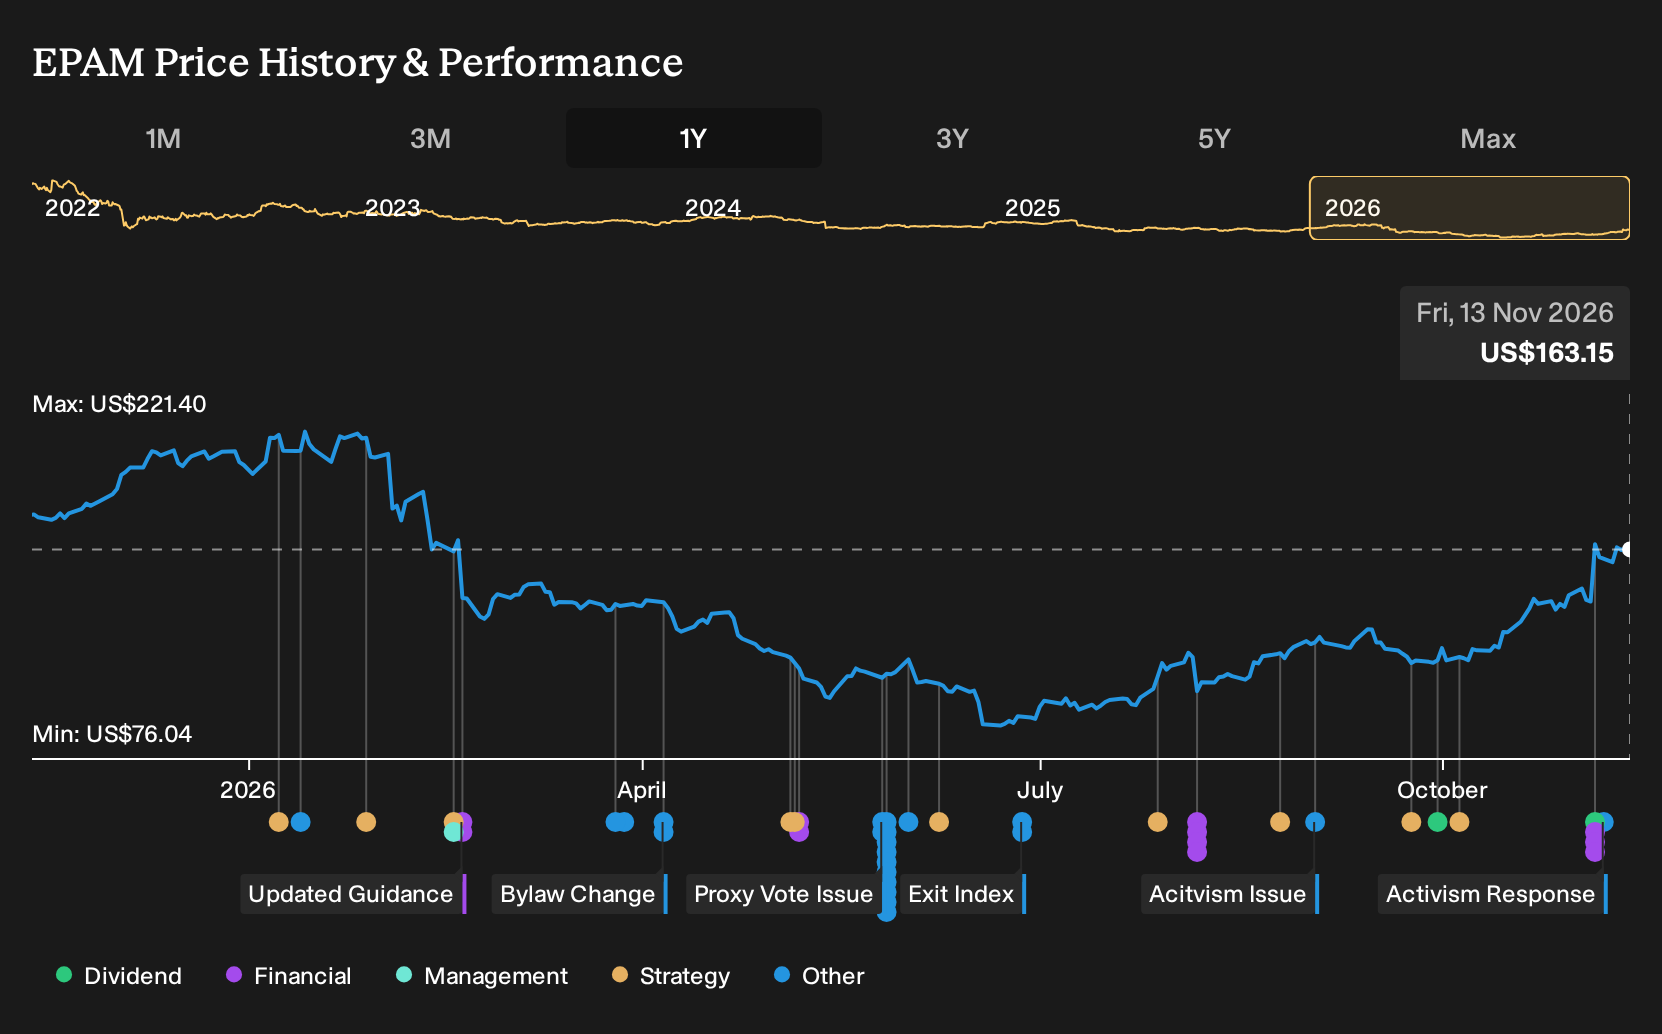
- The combination of higher earnings per share, fresh long term buyback capacity, and Engine Capital pushing for further capital returns and a strategic review is drawing increased attention to EPAM Systems' capital allocation and operating resilience.
- This article examines how EPAM Systems' bearish investment narrative holds up as management commits to a US$1.8 billion share repurchase plan.
EPAM Systems Investment Narrative Recap
To own EPAM Systems today, you need to believe the business can keep turning solid engineering demand into consistent earnings while working through softer IT spending and talent mix issues. Third quarter results showed revenue of US$1,426.43 million and net income of US$130.31 million, with guidance that points to modest 2026 growth and mid teens operating margins in the near term.
The short term swing factor is whether that guidance range proves realistic as clients stay cautious on discretionary projects. Westminster, a Simply Wall St Community investor who wrote the Narrative, argues that margin pressure and talent costs could grind profitability. That view frames the key risk. Any renewed drag on hiring geographies or pricing would matter more than the headline buyback story.
The fresh US$1.8b repurchase authorization running through 2029 is the announcement that ties closest to the current debate. Engine Capital is pushing for capital returns and a strategic review, so management setting a multi year buyback framework signals a willingness to commit free cash to shareholders while still operating under a universal shelf that keeps financing options open.
For you as an investor, the real test is whether EPAM Systems can sustain earnings per share that justify those repurchases while handling the structural issues Westminster highlights around talent and lack of proprietary compute assets. If execution on margins or delivery quality slips, the buyback could soften per share metrics for a time but would not remove the underlying operational questions.
Westminster grounds the narrative’s fair value of US$113.38 in a model that assumes EPAM Systems can grow revenue at 5.1% a year while settling into a 7.0% profit margin, which is framed as a reset level after the pressures on pricing, talent mix, and lack of proprietary compute assets.
Uncover why EPAM Systems' fair value indicates a 31% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One sharp contrast is the most bearish analysts’ view that EPAM Systems might struggle to turn AI work into richer pricing. Before this buyback news, that group was penciling in revenue of about US$6.2b and earnings of US$523.0m by 2029. That is a cooler outlook. It shows how far opinions can stretch. Use this activism push and new guidance as a cue to compare several narratives, then decide which assumptions you find realistic.
Explore 5 other EPAM Systems fair value estimates, including one that suggests as much as 31% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your EPAM Systems research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for EPAM Systems. The report includes a comprehensive fundamental analysis summarized in a single visual called the Snowflake, making it easy to evaluate EPAM Systems' overall financial health at a glance.
Looking for more investment ideas beyond EPAM Systems?
If the EPAM Systems story has you thinking about capital returns, cash generation, and valuation discipline, it can be useful to widen the lens and compare similar traits across a broader watchlist using the Simply Wall St Screener.
- For investors who care most about valuation and balance sheet strength, consider reviewing a curated 32 high quality undervalued stocks that pair robust fundamentals with prices that may look appealing against underlying cash flows.
- If resilience and capital protection sit at the top of your checklist, scan a focused group of 31 resilient stocks with low risk scores that score well on stability and business risk metrics.
- For those who want to catch potential future leaders before they are widely followed, it can be useful to comb through a 20 high quality undiscovered gems that combine quality fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com