


- Oklo Inc. recently signed multi-year definitive contracts with Centrus Energy for HALEU supply backed by Meta’s prepayment, securing fuel from Centrus’ American Centrifuge Plant for multiple Aurora reactors starting in 2029.
- The arrangement links Meta’s long-term clean power demand with Oklo’s advanced reactors and Centrus Energy’s enrichment build out, effectively tying HALEU offtake to a specific power campus and workforce expansion plan in Ohio.
- The next area of focus will be how Centrus Energy’s HALEU contracts with Oklo, supported by Meta’s prepayment, influence its overall investment narrative.
Scan how Centrus Energy fits into the broader nuclear build out by comparing it with 16 nuclear energy infrastructure stocks powering the next wave of advanced reactors and grid-scale baseload projects.
Centrus Energy Investment Narrative Recap
Centrus Energy appeals to investors who buy into a long runway for HALEU demand and believe the firm can turn that bottleneck into durable cash flows. According to CentryResearch, an investor in the Simply Wall St Community, the thesis hinges on advanced reactors needing reliable domestic enrichment capacity. The Oklo contracts backed by Meta’s prepayment help frame that vision around a specific power campus, yet the near term still looks execution heavy.
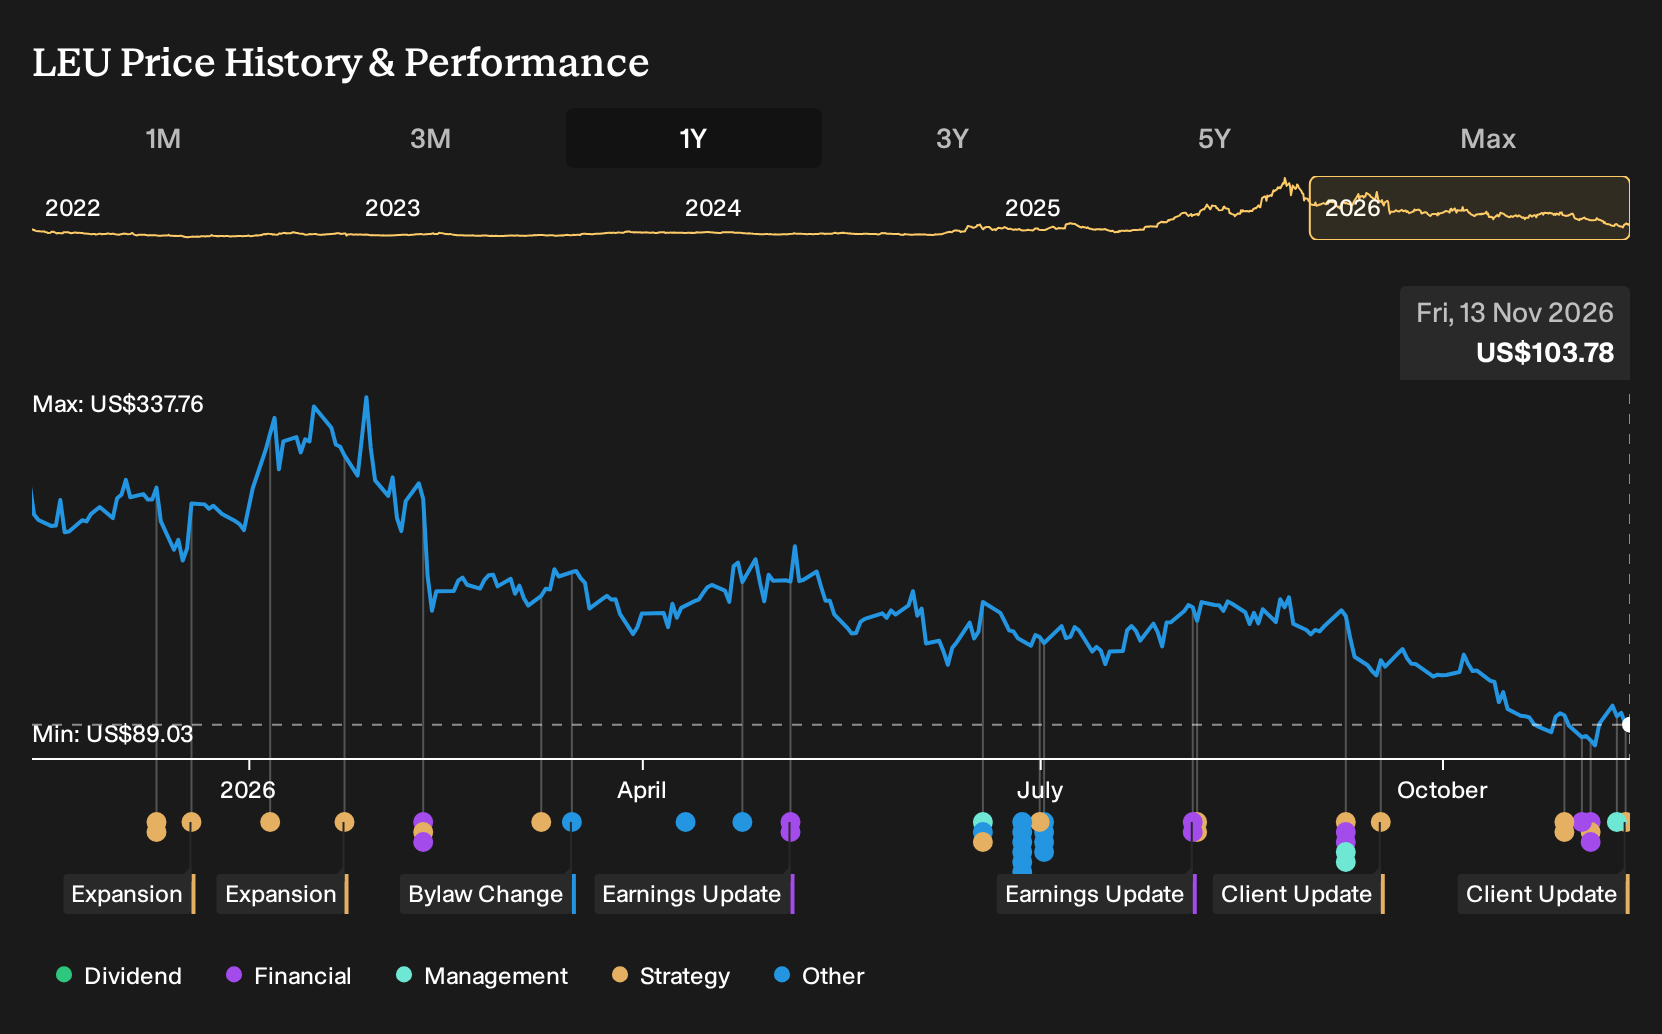
The most important short term catalyst is Centrus Energy’s ability to scale its American Centrifuge capacity on time and on budget, especially with forecast earnings declines and volatile margins. The biggest risk remains that enrichment build out and customer offtake timing stay mismatched, which could pressure returns on the planned US$350 million to US$500 million capital deployment.
The Oklo HALEU agreements connect directly with Centrus Energy’s broader expansion plans, including its expectation to hire at least 100 net new employees in Oak Ridge and at least 175 net new employees in Piketon. That hiring push, tied to centrifuge manufacturing and enrichment, shows how quickly the operational base is expanding around the Piketon plant.
Those commitments could sharpen both upside and downside around the HALEU thesis CentryResearch laid out. More capacity and workforce investment increase leverage to US$5.4b in contracted commitments, yet they also raise the cost of any delays, especially with earnings forecast to decline and the stock already screening as expensive on P/E and exposed to share price swings.
CentryResearch arrives at a fair value of US$190.00 per Centrus Energy share by modelling 24.8% annual revenue growth and a future profit margin of 13.4%, arguing that HALEU supply constraints could support that combination of top line expansion and mid teens profitability over time.
Uncover why Centrus Energy's fair value indicates an 83% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts focus less on HALEU bottlenecks and more on Centrus Energy’s potential margin expansion. Before this Oklo and Meta news, the most optimistic forecasts already pencilled in revenue of about US$677.3 million and earnings of US$107.7 million by 2029. Those views could shift meaningfully as these fresh contracts are digested.
Explore 5 other Centrus Energy fair value estimates, including one that suggests as much as 488% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Centrus Energy research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for Centrus Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centrus Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond Centrus Energy?
Once you have formed a view on Centrus Energy, it helps to line it up against other opportunities that match your goals on value, quality, and risk. The Simply Wall St Screener can surface different sets of companies that fit clear criteria, so you can build a watchlist that matches how you like to invest.
- If you want shares that combine quality metrics with prices that look appealing on fundamentals, start with a curated mix of 32 high quality undervalued stocks that already clear strict cash flow and balance sheet filters.
- If capital preservation matters more than chasing huge swings, consider a group of 31 resilient stocks with low risk scores that carry lower risk scores based on financial strength and business stability.
- If you prefer to back underfollowed businesses before they hit the mainstream, put together a shortlist from a set of 20 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com