


AGCO (AGCO) is back in focus after AGCO Power’s CORE engine family headlined the EIMA International 2026 show in Bologna, with the CORE75 and CORE80 platforms showcased in new Massey Ferguson and Valtra tractors.
AGCO shares have been edging higher, with a 30 day share price return of 4.83% and a 90 day gain of 10.47%. The 1 year total shareholder return of 8.02% points to steady but not explosive progress as interest builds around developments like the CORE engine rollout.
Spot opportunities across agricultural machinery by scanning our hand picked 86 robotics and automation stocks. These options echo the same off highway engineering focus that is now putting AGCO’s CORE engines in the spotlight.AGCO trades below both analyst targets and an internal fair value estimate, even after the recent share price climb. Is this patient pricing, or a warning that the market’s caution on the story is justified?
Most Popular Narrative: 10% Undervalued
AGCO’s last close at $111.94 sits below the $124 fair value used in the analyst consensus Narrative on Simply Wall St. This valuation applies a 9.28% discount rate and is based on detailed revenue, earnings and margin forecasts.
AGCO’s PTx precision agriculture platform is targeted to grow from just under US$900 million of revenue to US$2 billion by 2029, with over 50% gross margins and mid to high 20% operating margins. This would materially increase higher margin revenue and support earnings growth.
See why 35 investors see AGCO as 10% undervalued.
Result: Fair Value of $124 (UNDERVALUED)
Still, weak equipment demand in key regions and a US$93 million to US$95 million tariff headwind in 2026 could pressure the AGCO thesis.
Find out about the key risks to this AGCO narrative.
Another View On AGCO’s Valuation
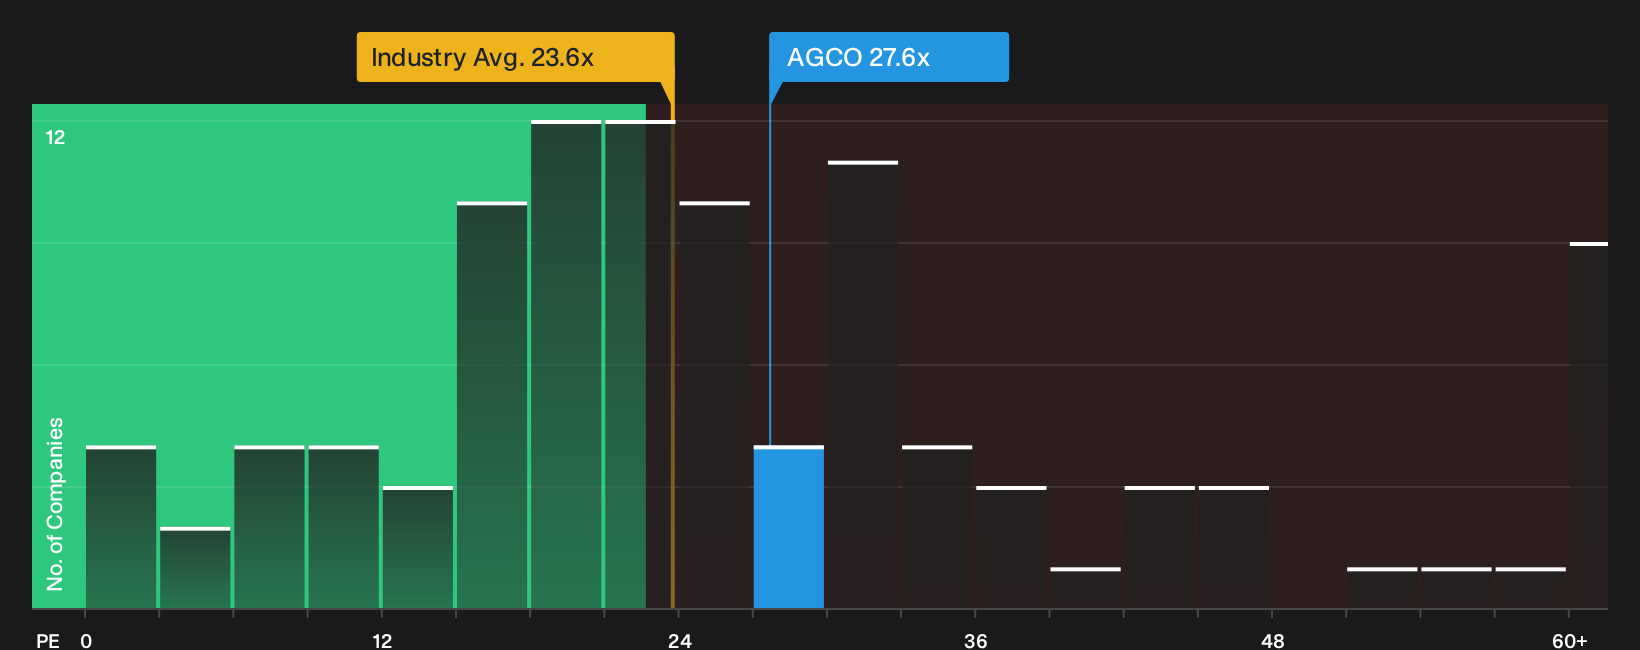
Multiples tell a different story for AGCO. The shares trade on a P/E of 27.6x, richer than the US Machinery industry on 23.7x but cheaper than peers on 31.3x. The fair ratio is reported at 32.5x. This raises the question of whether the DCF-driven undervaluation case reflects the whole picture.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Curious whether the mixed tone around AGCO lines up with your own read of the situation? Move fast, weigh both the potential upside and the pressure points, then stress test that view against the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond AGCO?
If AGCO has sharpened your interest in agricultural machinery and related sectors, do not stop here. Broaden your watchlist now and avoid missing opportunities building quietly elsewhere.
- Target resilience by scanning companies that score for sturdier finances and lower risk using our 31 resilient stocks with low risk scores.
- Hunt for quality at a discount by reviewing the 32 high quality undervalued stocks that match your return and risk expectations.
- Prioritise cash flow today by checking out the 6 dividend fortresses that combine higher yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com