


- Algonquin Power & Utilities reported third quarter 2026 revenue of US$642.5 million and net income of US$59.8 million, alongside consent solicitations to alter terms on three series of subordinated notes by removing an automatic conversion feature tied to certain bankruptcy events.
- The move to keep these subordinated notes as pure debt without changing interest rates, maturities or stated credit ratings highlights how Algonquin Power & Utilities is fine tuning its capital structure, while reporting mixed trends in earnings per share from continuing operations and total earnings.
- We will now explore how Algonquin Power & Utilities' decision to remove the notes' automatic conversion feature could reshape its broader investment narrative.
Algonquin Power & Utilities Investment Narrative Recap
To stay invested in Algonquin Power & Utilities, you need to believe the regulated utility pivot can translate steady rate base growth and cleaner execution into more consistent earnings. The third quarter results point to that tension. Revenue and net income were higher year on year, yet basic EPS from continuing operations moved from US$0.09 to US$0.07 as share count and mix effects did some work.
The analyst consensus narrative on Simply Wall St still leans on rate case execution, disciplined costs and balance sheet repair as the key near term catalyst. That view now sits alongside a revised 2027 adjusted EPS outlook of US$0.38 to US$0.42 and interest coverage flagged as tight. The recent quarter does not change those swing factors in a material way; it just reinforces that credit metrics and regulated returns remain the hinge.
The most relevant update is Algonquin Power & Utilities’ consent solicitation to strip the automatic equity conversion feature from several subordinated note issues. Those securities would remain subordinated debt, with no change to coupon, maturity or stated credit ratings. For a regulated utility planning about US$3.2b of CapEx from 2026 to 2028, the structure of hybrid funding matters for how comfortably that spend can be financed.
Keeping these instruments as pure debt interacts directly with the risks flagged around FFO to debt drifting toward rating thresholds and dividends not being fully covered by earnings or free cash flow. If credit agencies treat the notes similarly from a ratings lens, this approach could help Algonquin Power & Utilities focus on execution in its core regulated businesses while monitoring interest coverage, rather than juggling additional equity-like triggers in a stress scenario.
Algonquin Power & Utilities’ current analyst storyline points to revenues of US$2.9b and earnings of US$342.6 million by 2029. These figures are built on assumed yearly top line growth of 3.4% and an earnings increase of about US$167.6 million from US$175.0 million today.
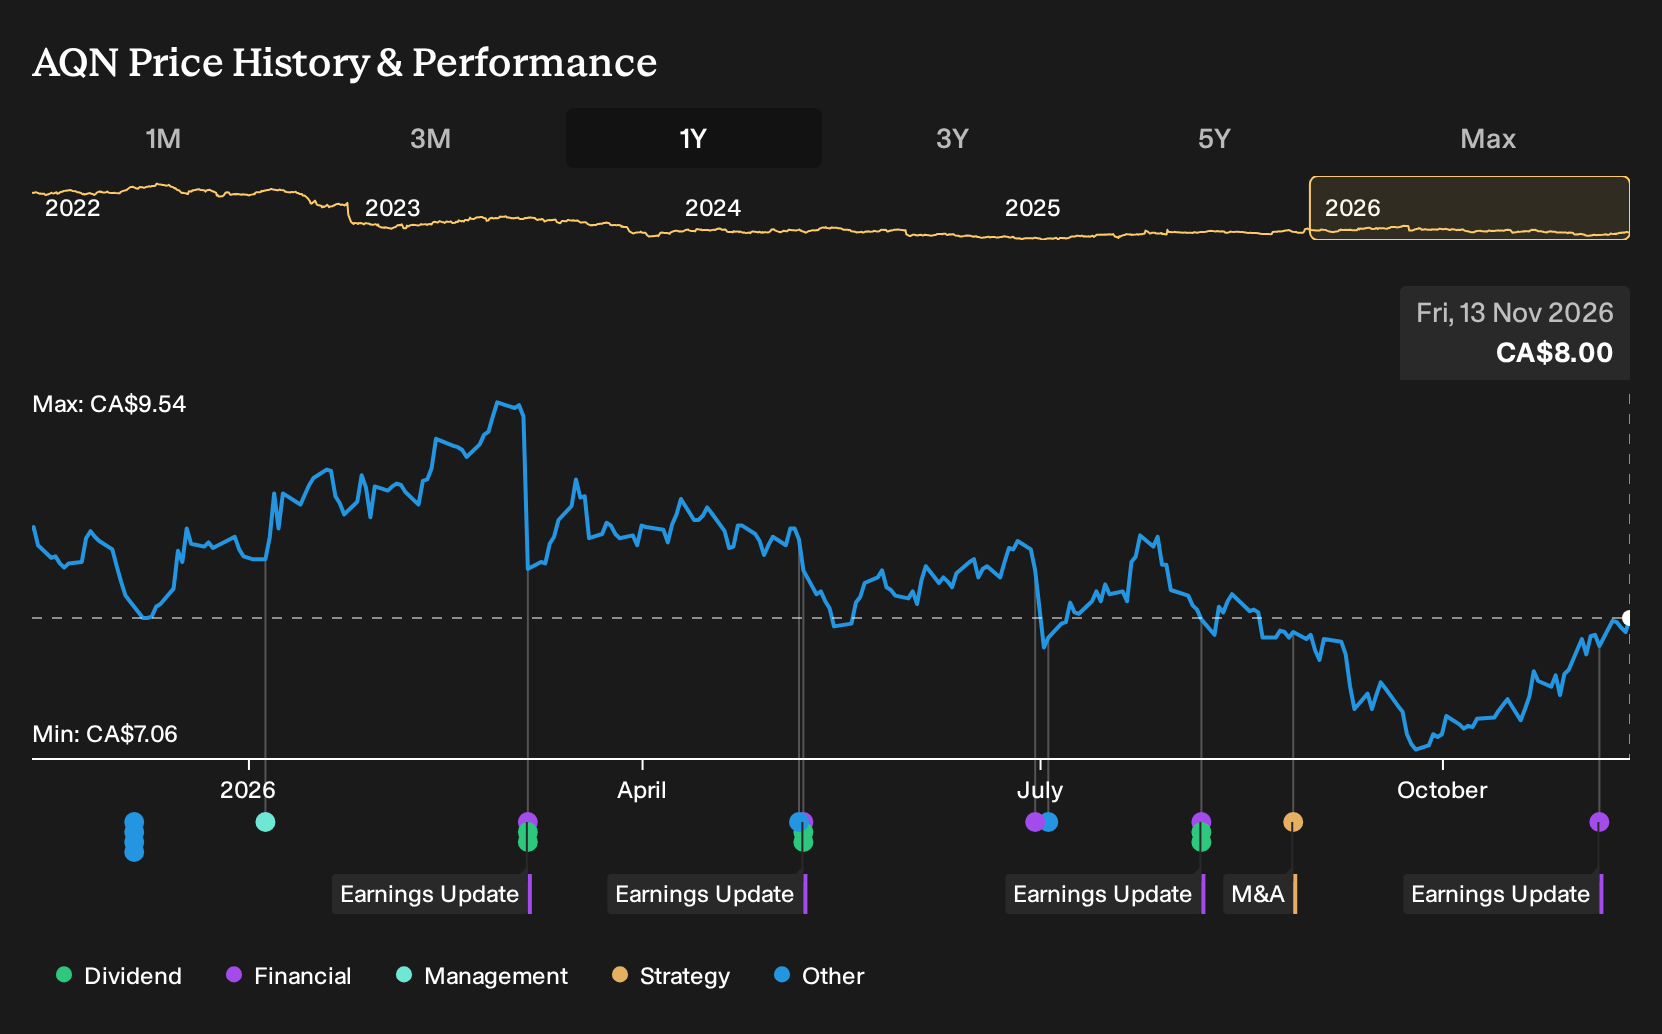
Uncover why Algonquin Power & Utilities' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Algonquin Power & Utilities focuses on earnings potential rather than balance sheet strain. The most optimistic analysts were sketching out about US$3.0b of revenue and US$400.3 million of earnings by 2029 before this quarter and the note conversion change. You can treat this news as a fresh prompt to compare those upbeat forecasts with more cautious views.
Explore 4 other Algonquin Power & Utilities fair value estimates, including one that suggests potential upside of as much as 209% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Algonquin Power & Utilities research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Algonquin Power & Utilities. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Algonquin Power & Utilities' overall financial health at a glance.
Looking for more investment ideas beyond Algonquin Power & Utilities?
If the Algonquin Power & Utilities story has sharpened your focus on balance sheets, income potential and risk, broaden that lens by scanning other companies that fit your preferred criteria using the Simply Wall St Screener.
- For investors who want quality on sale, filter for companies with stronger fundamentals using our 7 high quality undervalued stocks that might fit your watchlist.
- If steady income is a key part of your plan, zero in on potential income payers through the 3 dividend fortresses that screens for higher yielding opportunities.
- When capital preservation ranks high for you, narrow the field to companies with sturdier financial profiles using our 9 resilient stocks with low risk scores to keep your research focused.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com