


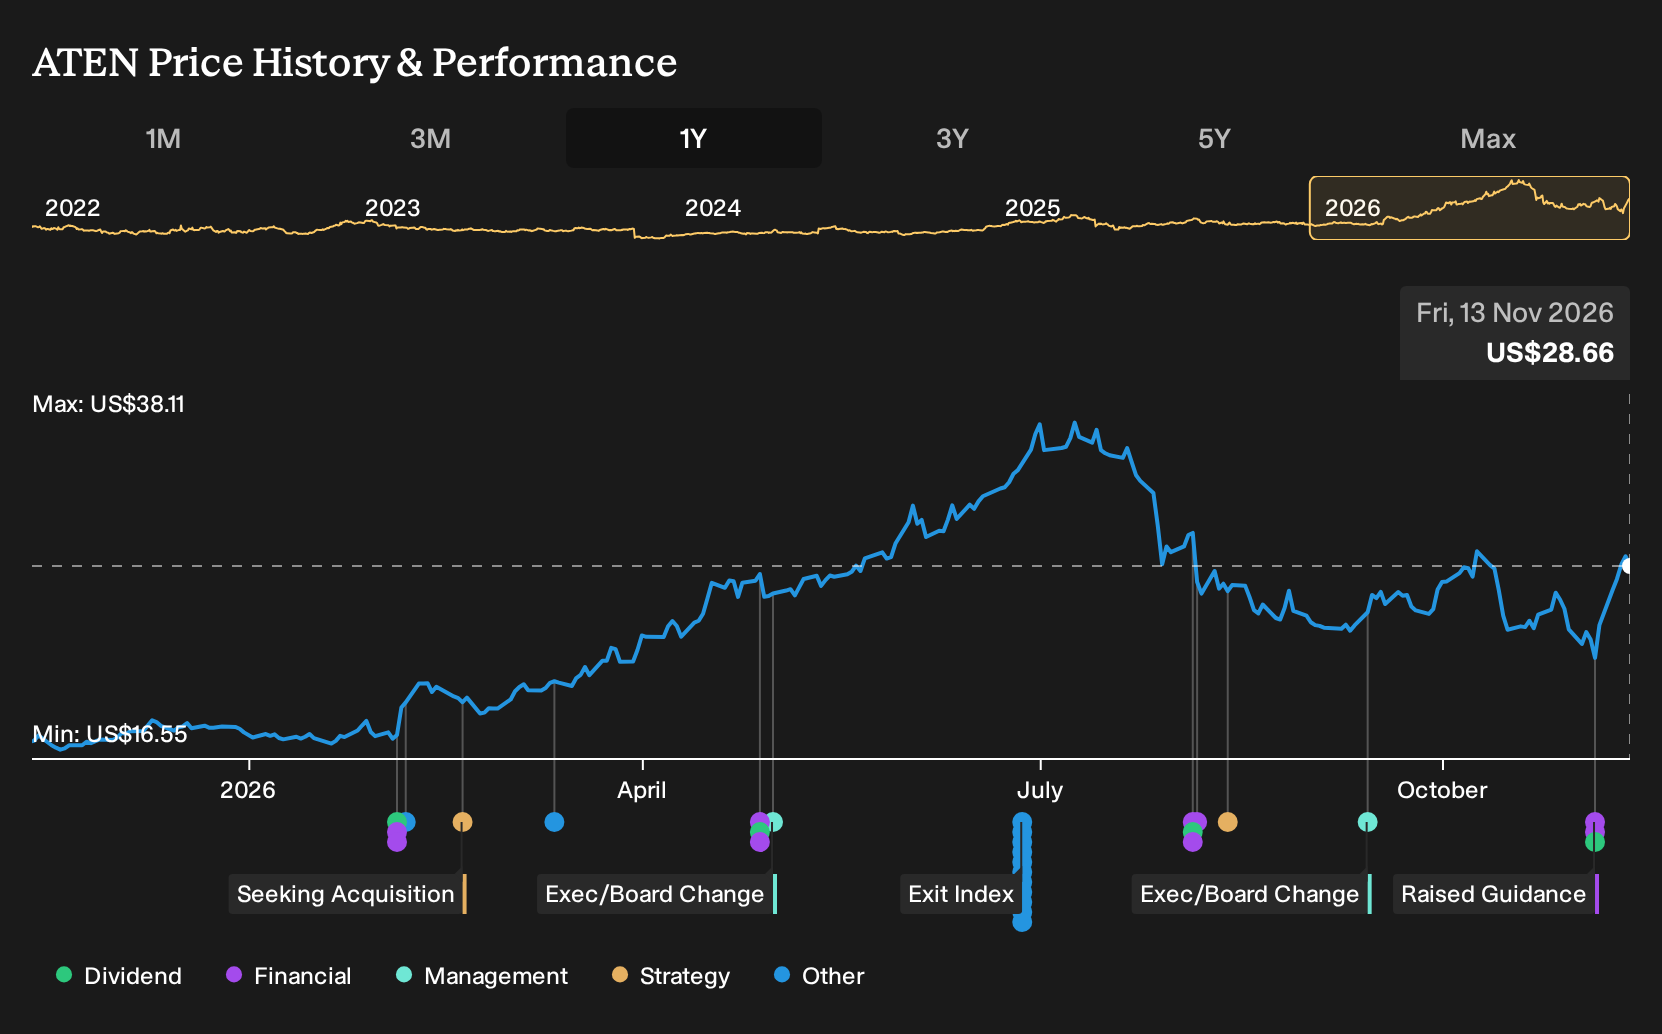
- A10 Networks reported third quarter 2026 revenue of US$91.55 million and net income of US$17.16 million, with higher basic and diluted EPS from continuing operations compared with the same period a year earlier.
- Management raised full year 2026 revenue growth guidance to 16% over the prior year, linking the outlook to demand for AI focused security and networking solutions.
- We will examine how A10 Networks' investment narrative is shaped by the raised full year revenue guidance alongside recent earnings performance.
Scan how A10 Networks' AI focused security story compares with other potential breakouts by reviewing the hand picked 53 AI infrastructure stocks alongside this latest earnings and guidance update.
A10 Networks Investment Narrative Recap
To own A10 Networks, you need to be comfortable with a security led infrastructure business that is tying its future closely to AI traffic. The analyst consensus Narrative on Simply Wall St leans on AI infrastructure projects and products like the coming A10 AI Gateway as the main engine for future earnings. The latest quarter, with higher revenue and EPS than a year earlier, supports that story rather than changing it.
The biggest near term swing factor still looks like execution on large AI heavy deployments with a small set of concentrated customers. Any slowdown from the strategic AI client that contributes about 37% of revenue would matter more than one quarter of solid numbers. Supply chain pressures around memory components also remain a risk for margins even if top line guidance holds.
The clearest announcement to focus on right now is the raised full year 2026 revenue growth guidance to 16% over the prior year. That target sits on top of nine month revenue of US$246.68 million and management commentary linking demand to AI focused security and networking. For a reader, the key question is whether current orders and the planned A10 AI Gateway launch can sustain that pace.
This higher outlook cuts both ways. It underlines confidence in AI infrastructure spend as a near term catalyst, yet it also tightens the bar for execution if any large AI projects slip or that major customer moderates spending. Against that backdrop, the affirmed quarterly dividend of US$0.06 per share signals a willingness to return cash even while the business leans into growth opportunities.
A10 Networks' current narrative points to forecast revenues of US$443.1 million and projected earnings of US$79.1 million by 2029. This outlook is based on analysts assuming yearly revenue growth of 10.7% and an earnings increase of about US$31.2 million from current earnings of US$47.9 million.
Uncover why A10 Networks' fair value indicates a 19% potential upside to its current price that could narrow quickly if sentiment shifts toward A10 Networks.
Exploring Other Perspectives
One alternative view leans hard into A10 Networks as a cash flow story. The most optimistic analysts were already sketching out about US$452.8 million of revenue and roughly US$81 million of earnings by 2029. That reflects a more upbeat narrative on AI security demand, which this latest guidance raise may still reshape.
Explore 2 other A10 Networks fair value estimates, including one that suggests potential upside of as much as 19% from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A10 Networks research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for A10 Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A10 Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond A10 Networks?
If the A10 Networks story has sharpened your thinking about AI infrastructure and security, you can use that same lens to hunt for other opportunities with the Simply Wall St Screener.
- If you are hunting for companies that already pair stronger fundamentals with appealing valuations, start with a focused set of 32 high quality undervalued stocks that fit those filters out of the box.
- If capital preservation sits higher on your priority list, narrow your search to a curated group of 31 resilient stocks with low risk scores that may suit a more cautious approach.
- If balance sheet strength is your first checkpoint, scan the list of solid balance sheet and fundamentals (24 results) to see which businesses clear a higher bar on debt and liquidity.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com