


Lucid Group earnings reset the conversation
Lucid Group (LCID) just released third quarter 2026 results, giving investors fresh numbers on sales and ongoing losses as the electric vehicle maker continues to build out its business model.
The earnings release landed amid a sharp reset in sentiment. Lucid Group’s share price has fallen 52.49% over the past 90 days and is down 73.50% year to date, while the 1-year total shareholder return has declined 79.19%, signaling fading momentum as investors reassess the balance between growth ambitions and ongoing losses.
Scan beyond Lucid Group's reset and compare it to hand-picked EV peers and related plays, which are screened for financial strength using list of solid balance sheet and fundamentals (24 results).
Bulls see Lucid Group as a beaten down growth story with rising sales and narrowing quarterly losses, while bears focus on the deep ongoing net loss. Which side does the valuation math lean toward next?
Most popular narrative: 2% undervalued
Lucid Group last closed at $2.96, while the narrative fair value sits at $3.02, a small gap that still raises big questions over whether the current share price fully reflects the latest earnings reset.
According to DanielOliveira, an investor in the Simply Wall St Community who wrote the narrative, the key debate sits around pricing per vehicle and how much Lucid Group leaned on incentives to move cars in the latest quarter.
Consensus revenue is about $399.1 million from eight analysts, in a range of $321.7 million to $441.5 million. I expect about $376.6 million. With volume settled, the consensus needs a price Lucid has never reported. Excluding regulatory credits, revenue per delivery was $79.7K a year ago, $91.3K in Q1 and $96.1K in Q2. With $15 million of credits, $399.1 million needs about $100.9K per delivery, another 5% rise, in a quarter when Lucid delivered 852 more vehicles than it built. Some of the eight estimates were probably built before the delivery release and not revised.
See why 1 investors see Lucid Group as 2% undervalued.
Result: Fair Value of $3.02 (UNDERVALUED)
Still, the narrative could crack if Lucid Group relies more on discounted deliveries or if Saudi-related sales soften further and weigh on pricing power.
Find out about the key risks to this Lucid Group narrative.
Another view on Lucid Group’s valuation
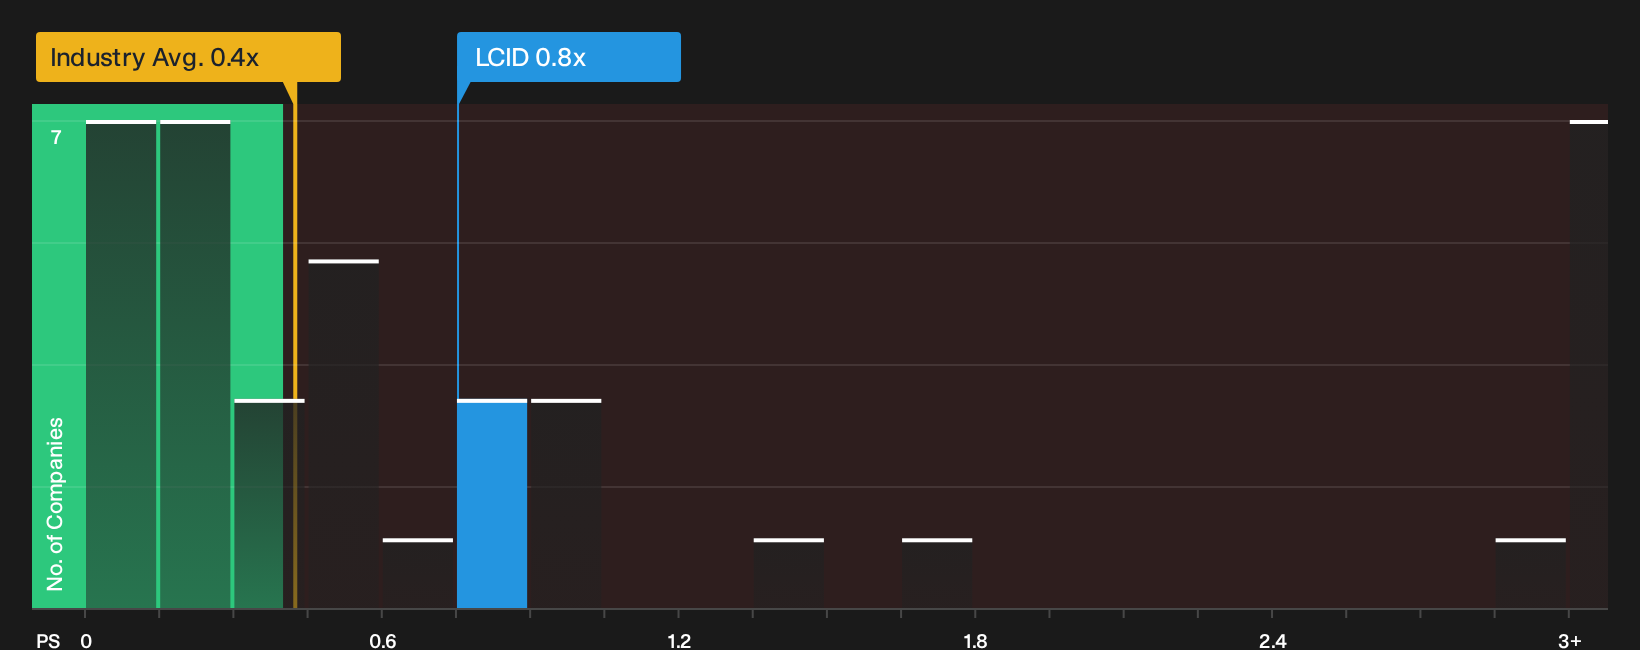
The community narrative points to Lucid Group trading about 2% below fair value at $3.02. The market’s own yardstick tells a very different story. On a P/S of 0.8x, Lucid trades well above both its direct peers at 0.3x and the wider US auto industry at 0.4x, while the fair ratio sits at 0x. That gap suggests investors face more valuation risk than the narrative alone implies. Where should you anchor your view?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty in this Lucid Group story can look polarizing at first glance, so treat this as a prompt to check the data yourself and move fast to shape your own stance. To weigh what matters most for you, start with a clear view of the trade off between the 1 key reward and 4 important warning signs highlighted in 1 key reward and 4 important warning signs.
Looking for more investment ideas beyond Lucid Group?
If Lucid Group has sharpened your focus on risk and reward, treat this as your cue to hunt for better positioned opportunities before others move first.
- Target potential bargains by scanning companies that pair healthy balance sheets with attractive valuations through the 32 high quality undervalued stocks.
- Prioritize resilience by reviewing a 31 resilient stocks with low risk scores that screens for businesses with sturdier financial risk profiles.
- Spot emerging opportunities early by working through a 20 high quality undiscovered gems that highlights quality companies still flying under most investors' radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com