


ACI Worldwide (ACIW) released third quarter 2026 results that showed lower revenue and earnings versus a year earlier, while keeping full year guidance and outlining new fourth quarter revenue expectations.
Against that earnings backdrop, ACI Worldwide’s share price has climbed 15.68% over the past month and 33.11% year to date, while total shareholder return over three years sits at 136.26%, pointing to momentum that has strengthened rather than cooled.
Scan how ACI Worldwide compares with other payment and software players by running your own shortlist using our curated 32 high quality undervalued stocks.
ACI Worldwide now trades below both analyst targets and one estimate of fair value after a sharp run, so the real test is whether that discount reflects opportunity or justified caution on recent earnings softness.
Most Popular Narrative: 10.6% Undervalued
Against Friday's close at $60.79, the analyst consensus Narrative on Simply Wall St anchors fair value for ACI Worldwide at $68. This frames the current discount through the lens of forecast revenue, earnings and capital return assumptions.
The roll out of ACI Connetic as a cloud native payments hub, supported by recent wins with Solaris and multiple Federal Home Loan Banks and a rapidly expanding pipeline among mid tier financial institutions, points to additional subscription and services revenue that investors may not yet fully reflect in expectations.
Growing real time payments adoption, illustrated by double digit revenue growth in this area and new infrastructure contracts with institutions across Malaysia, Colombia and Canada, creates further transaction and software revenue potential that may not be fully captured in ACI Worldwide valuation.
See why 9 investors see ACI Worldwide as 11% undervalued.
Result: Fair Value of $68 (UNDERVALUED)
Still, the ACI Worldwide story can be knocked off course if rivals win key payment flows, or if Biller segment hiccups repeat and squeeze profitability again.
Find out about the key risks to this ACI Worldwide narrative.
Another View: Market Ratios Push Back
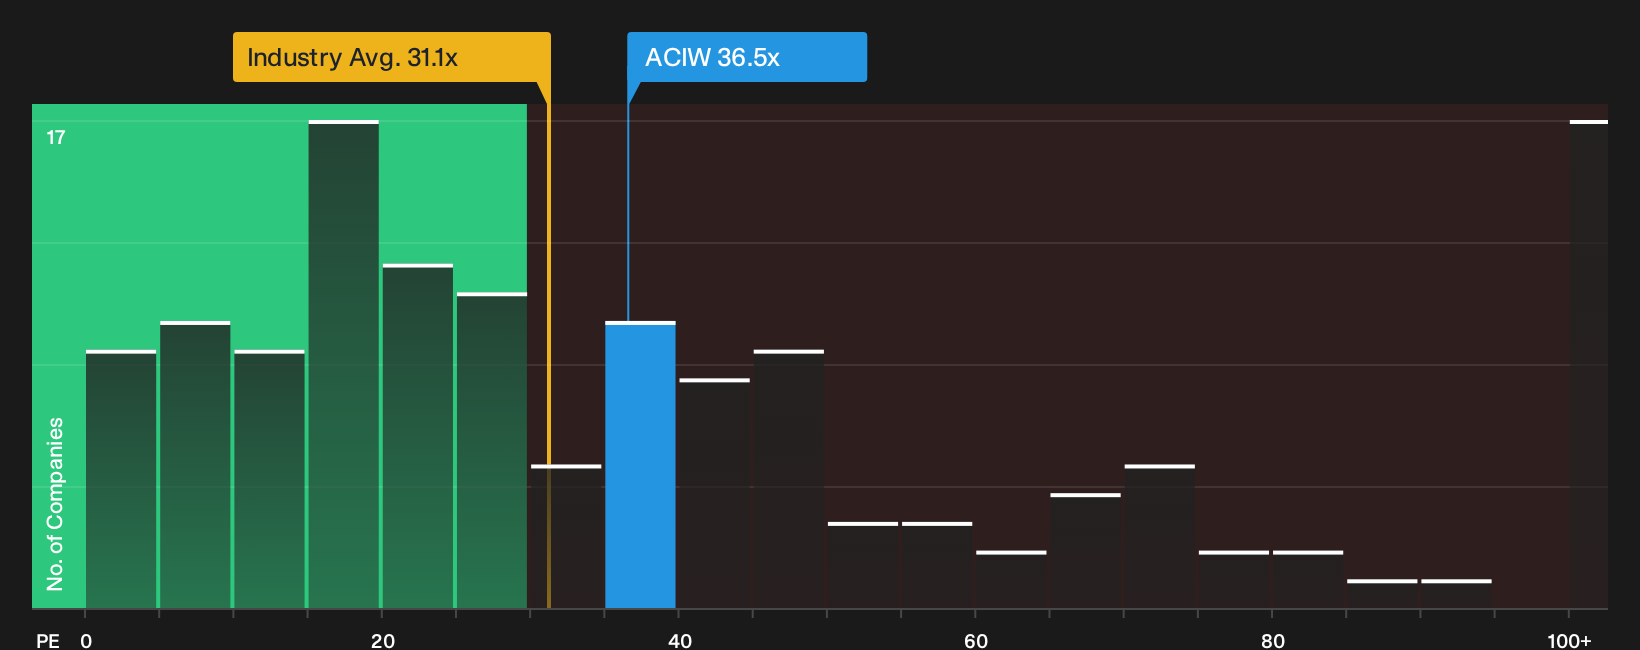
There is a catch with ACI Worldwide. On simple market ratios, the stock looks expensive. The shares trade on a P/E of 36.5x versus a fair ratio of 30.8x, the US Software industry at 31.1x, and peers around 24.1x. That kind of gap can close in more than one way.
For a closer look at how those earnings multiples stack up against the fair ratio and peers in practical terms, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on ACI Worldwide so far. If you want to move quickly and form your own take using the same inputs, start with our breakdown of 2 key rewards and 2 important warning signs
Looking for more ACI Worldwide style investment ideas?
If you only focus on ACI Worldwide, you could miss other opportunities quietly gaining traction, so give yourself options with a broader watchlist.
- Spot potential bargains early by scanning our 20 high quality undiscovered gems before they move onto everyone else's radar.
- Strengthen your downside protection by focusing on businesses highlighted in our 31 resilient stocks with low risk scores that score well on resilience.
- Build a sturdier income stream by filtering for steady payers through the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com