


- House Foods Group reported half year results for the period ended September 30, 2026, with sales of JPY 156,393 million, net income of JPY 9,839 million, and basic earnings per share from continuing operations of JPY 110.09.
- The increase in net income relative to the prior half year indicates a period of stronger profitability for House Foods Group, which investors may view as evidence that cost control and product mix are working more effectively together.
- Next, the focus turns to how House Foods Group's investment narrative develops as higher half year earnings per share influence the risk and reward profile.
What Is House Foods Group's Investment Narrative?
For a shareholder, the core belief around House Foods Group is that a broad, staple driven product set in spices, curry roux, tofu and health foods can keep factory lines busy and pricing relatively steady through different cycles. The latest half year showing, with sales of ¥156,393 million and net income of ¥9,839 million, suggests that recent execution on mix, efficiency and overheads is feeding through to earnings per share at ¥110.09.
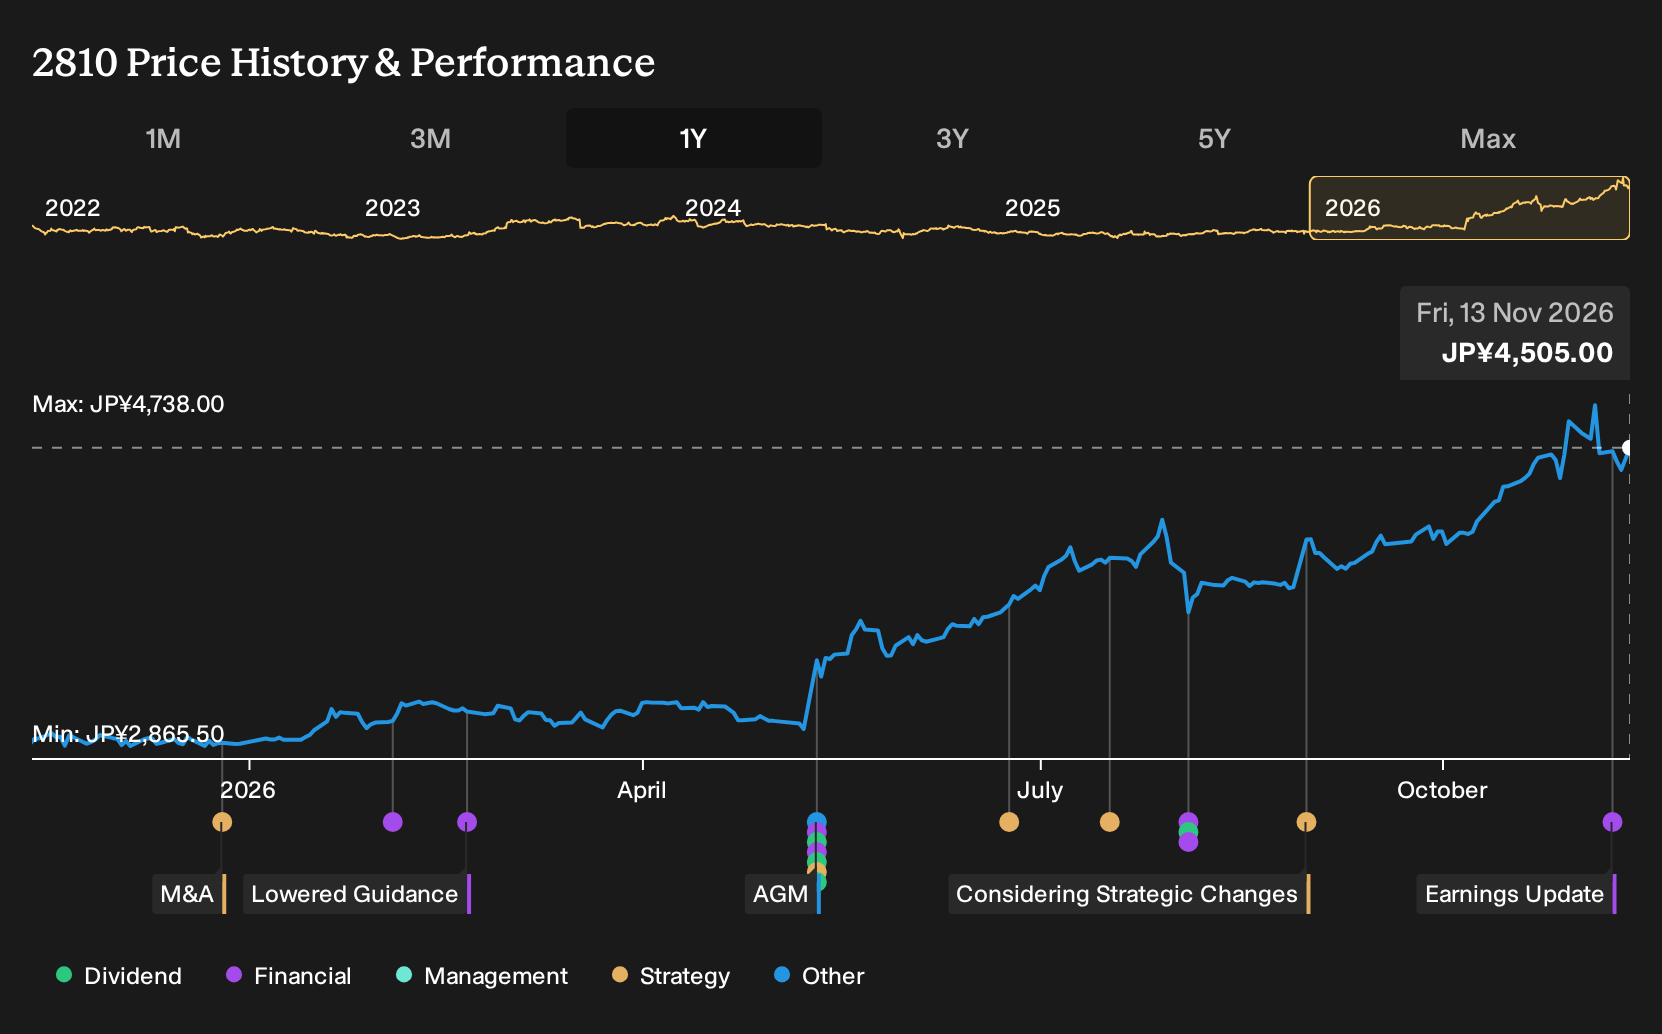
In the short term, the key swing factors are how well House Foods Group manages input costs, keeps demand for core products firm and allocates cash between reinvestment and dividends. The share price has climbed 59.3% over the past year and the P/E sits at 34.2x, so expectations already embed a fair amount of confidence in operations. The new profit line slightly eases concern around earnings quality, though questions remain around slower forecast revenue growth and how well free cash flow supports a 2.22% yield.
That said, there is still one pressure point in the House Foods Group story that deserves closer attention before committing new capital...
There's only one way to know the right time to buy, sell or hold House Foods Group. Head to Simply Wall St's company report for the latest analysis of House Foods Group's Fair Value.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your House Foods Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for House Foods Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate House Foods Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond House Foods Group?
Once you have a view on House Foods Group, it can help to set that thinking alongside a wider watchlist so you can compare quality, valuation and risk side by side using the Simply Wall St Screener.
- If you want income to play a bigger role in your portfolio, scan for higher yielding opportunities with the 28 dividend fortresses that may complement a stock like House Foods Group.
- For investors who care most about balance sheet resilience, filter for companies with stronger finances using the list of solid balance sheet and fundamentals (24 results) and stress test your holdings against sturdier peers.
- If you prefer to look off the beaten track for potential opportunities, broaden your research with the 72 high quality undiscovered gems and compare those profiles with what you see at House Foods Group.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com