


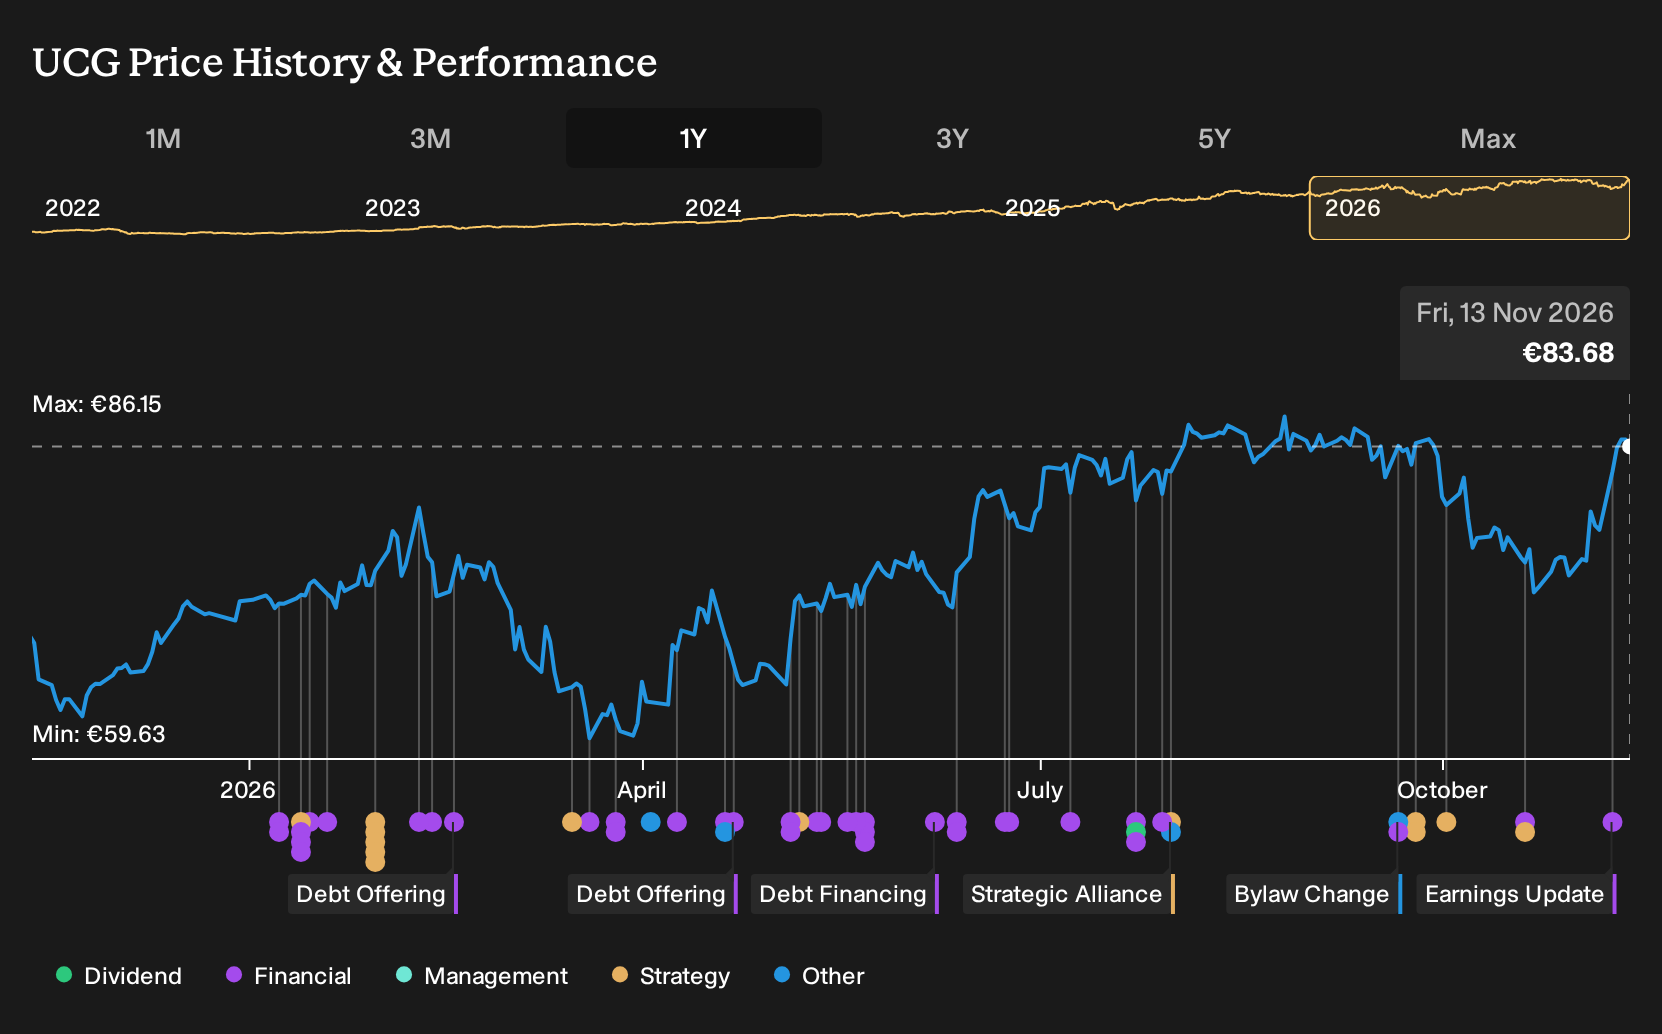
If UniCredit sat on your watchlist instead of in your portfolio during the past year, this result may feel like a missed shot. Investors who held UniCredit over the past year are up 36.1%, including dividends. That jump came while bulls argued for long-run earnings power and bears flagged fintech pressure and regulatory costs. If you rewind to late 2025, which business assumption looked more important: UniCredit’s push for digital and cross border growth, or concerns about disruption and tighter rules?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
If the move has made UniCredit harder to judge, start where the gap is still open and scan 198 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On UniCredit
The shares cost €67.48 at the start of the period, and investors looking at UniCredit had to choose between two sharply different stories.
On the bullish side, a thesis from December 2024 put Fair Value at €78.13, or 16% above the start price. This was built on 18.0% revenue growth, a 43.3% profit margin assumption and a future P/E of 5.7x over a 10 year horizon.
The bearish view from June 2025 set Fair Value at €57, or 16% below the start price. It leaned on risks from digital disruption, tighter regulation and concentration in Southern Europe.
What The UniCredit Evidence Actually Tested
UniCredit’s push to gain control of Commerzbank, backed by ECB authorisation to exceed a 30% stake and German conditions around listing and lending, directly relates to the argument about cross border scale. At the same time, Q3 2026 results showed revenue and net income above Q3 2025, with net margin up from 43.6% to 48.5%. Overall, the evidence supported the more optimistic interpretation rather than a more cautious one.
The central assumption here was earnings power from expansion rather than just cost cutting. When you assess another bank, check whether large acquisition plans and digital initiatives eventually appear in reported revenue, net profit and net margin, not only in presentation materials.
What UniCredit’s Price Now Asks You To Believe
UniCredit now trades at €83.68, which is above the Fair Value in the bearish analyst Narrative on Simply Wall St. That Narrative treats today’s level as already baking in a positive outcome on efficiency, capital strength and pan European reach.
For a buyer at this price, the working assumption is that integration, AI spend and Russia compression all net out well. The open question is how the execution and capital strains described in that Narrative affect the odds of that result.
"The main thing that has to go right is that UniCredit converts its AI and technology programme, fee and insurance expansion, Commerzbank integration and Russia de-risking into sustained, capital-light earnings while maintaining strong capital and distributions."
One Narrative disagrees with today's price. → See where this Narrative says UniCredit should trade
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 40% below our estimate - targets higher margin nutrition products as it shifts toward premium, specialised lines.
- Company 2 - 28% below our estimate - pushes clinically supported probiotics into faster growing adult and oral health segments.
- Company 3 - 41% below our estimate - extends data and AI tools across underwriting and claims to sharpen cost control.
That is three of the list. See all 198 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com