


- Recent coverage of Amkor Technology highlights fresh earnings estimate revisions that point to higher expected profit compared with the prior fiscal year, with the business still identified as an outsourced semiconductor assembly and test provider serving multiple end markets.
- Analysts now grade Amkor Technology as A on valuation and see it trading at a discount to sector peers, which helps frame how investors weigh the revised earnings outlook against the company’s current pricing.
- This article examines how Amkor Technology's upgraded earnings expectations and valuation rating may influence the broader investment narrative around the stock.
Scan beyond Amkor Technology and see how other potential value ideas with similar earnings and pricing setups line up in our curated 32 high quality undervalued stocks.
Amkor Technology Investment Narrative Recap
To own Amkor Technology, you need to believe its heavy build out in Arizona, Korea, Vietnam, Portugal and Taiwan turns into solid utilization rather than idle capacity weighing on profit. The analyst consensus narrative on Simply Wall St ties the story to AI data center, high performance computing and automotive demand feeding those advanced packaging lines.
In the short term, the key swing factor is how quickly AI and computing programs offset softer communications end markets and any disruption from migrating SiP capacity to Vietnam. The biggest risk remains underused facilities and the fixed cost drag that could create. The latest news around sentiment shifts does not change those operational stakes.
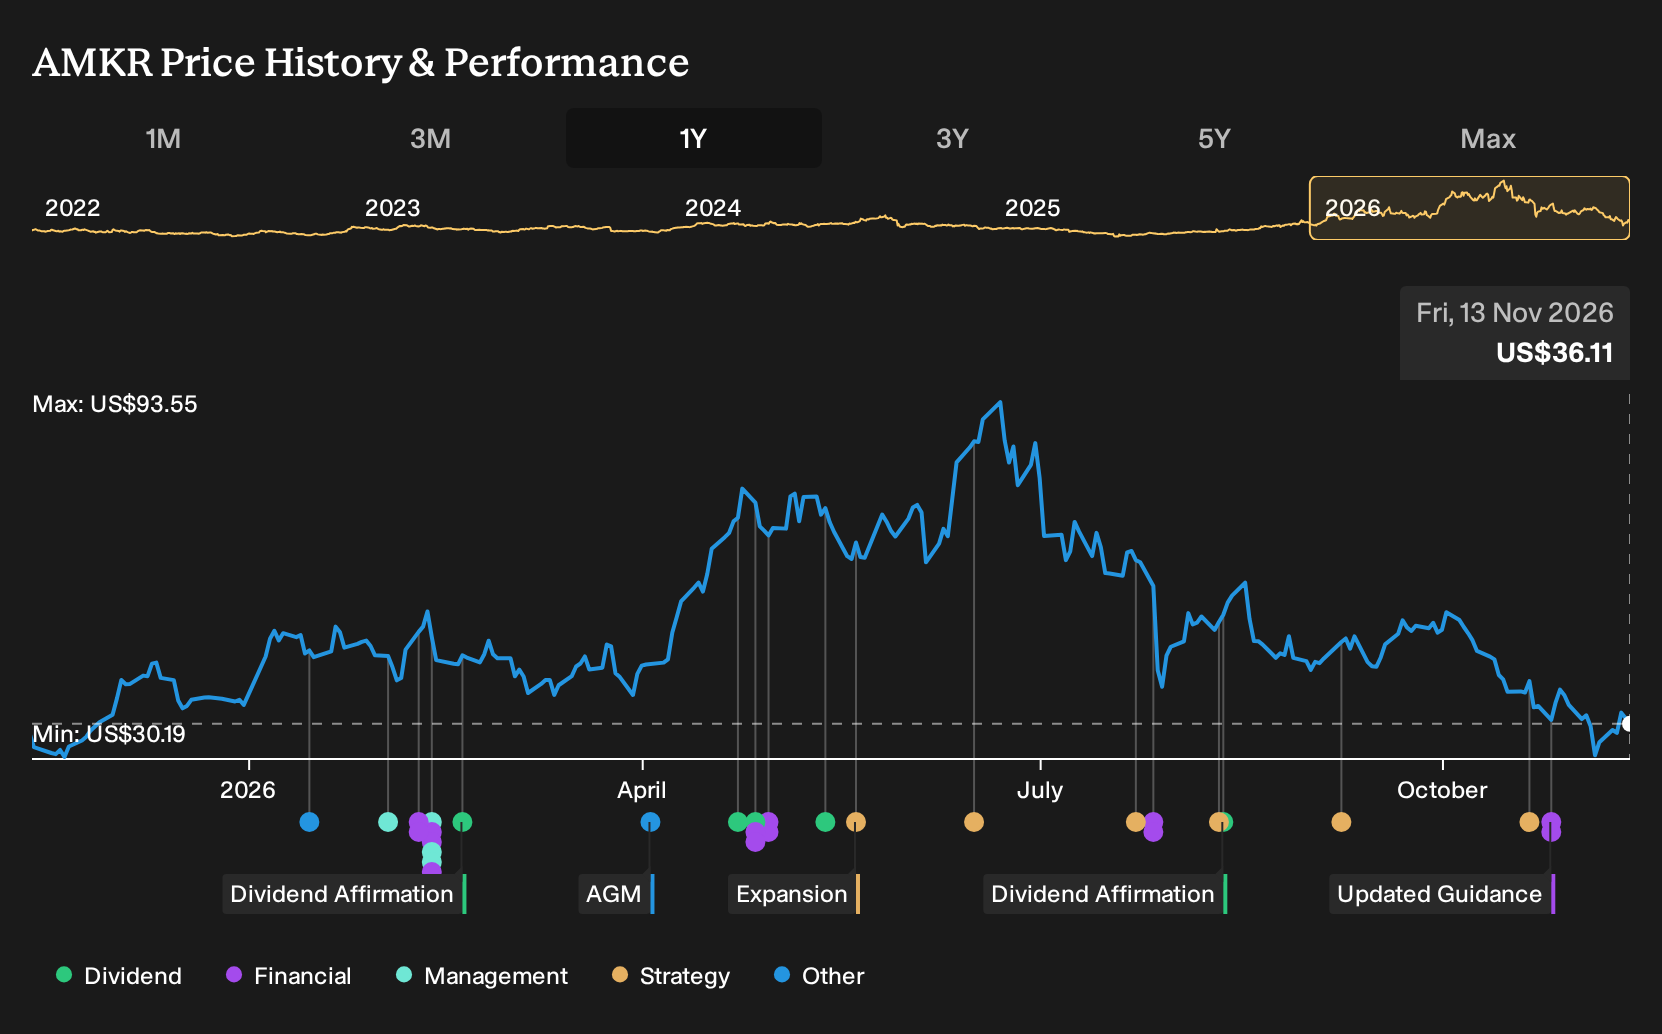
The recent Argus move to lower its target price to US$38 brings attention back to execution risk around that global expansion and earnings trajectory. It does not alter Amkor Technology’s capacity plans or its role as an outsourced packaging and test provider across computing, communications, automotive and industrial customers.
For you as an investor, the key link is how such sentiment intersects with the upgraded earnings estimates and the valuation grade already flagged for Amkor. If the firm continues to align its Arizona and Asian capacity with long term arrangements tied to AI and advanced packaging demand, that operational follow through is likely to matter more than any revised external targets.
Amkor Technology's current earnings are $619.5 million, with analysts projecting revenues of $10.2b and earnings of $845.3 million by 2029. This projection assumes 11.2% yearly revenue growth and an earnings increase of about $225.8 million from today's level.
Uncover why Amkor Technology's fair value indicates an 83% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on Arizona execution risk. The most bearish analysts, who were assuming revenue of about US$9.9b and earnings near US$742.7 million by 2029 before this Argus target cut, see Amkor Technology carrying a larger U.S. footprint than demand justifies. Their story is far more cautious on utilization and future profitability. You are seeing how far opinions can stretch; use this news as a cue to compare several narratives before deciding where you sit.
Explore 5 other Amkor Technology fair value estimates, including one that suggests as much as 88% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Amkor Technology research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Amkor Technology. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Amkor Technology's overall financial health at a glance.
Looking for more investment ideas beyond Amkor Technology?
Once you have formed a view on Amkor Technology, it can help to cross check that thesis against other stocks with similar financial traits and different risk profiles using the Simply Wall St Screener.
- For investors who want income plus resilience, scan for companies with strong cash coverage and consistent payouts using our 6 dividend fortresses.
- If capital preservation sits high on your priority list, filter for businesses with steadier balance sheets and fewer flagged risks through the 31 resilient stocks with low risk scores.
- When you want to widen the search beyond well known tickers, surface financially strong but less followed opportunities with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com