


- Qualcomm reported fiscal 2026 revenue of US$43.12b and net income of US$13.63b. The company then guided first quarter fiscal 2027 sales to a range of US$10.4b to US$11.2b and also issued several multi year fixed rate bond offerings in November 2026.
- The earnings release showed handset pressure with a 26% decline in handset chip revenue cited by Freedom Capital Markets, even as Qualcomm pushes deeper into AI data center programs and 5G infrastructure partnerships that aim to diversify its future mix.
- We will now see how Qualcomm's handset weakness, highlighted in the latest guidance and downgrade commentary, could reshape its broader investment narrative.
Scan beyond QUALCOMM and see how other AI infrastructure and data center players are setting up right now with the curated 53 AI infrastructure stocks in this same theme.
QUALCOMM Investment Narrative Recap
To own QUALCOMM, you need to believe the handset slump is a passing drag and that data center, automotive and IoT can carry more of the load. Handset chip revenue fell sharply and the latest guidance points to softer near term earnings. The near term catalyst is clear execution on AI and data center ramps that start converting recent wins into meaningful revenue.
The biggest operational risk right now is that handset weakness and competition from in house chips at large OEMs offset progress in newer lines. If data center and other non handset programs scale slower than planned, QUALCOMM could face pressure on QCT margins and a less balanced revenue mix than the analyst consensus Narrative on Simply Wall St assumes.
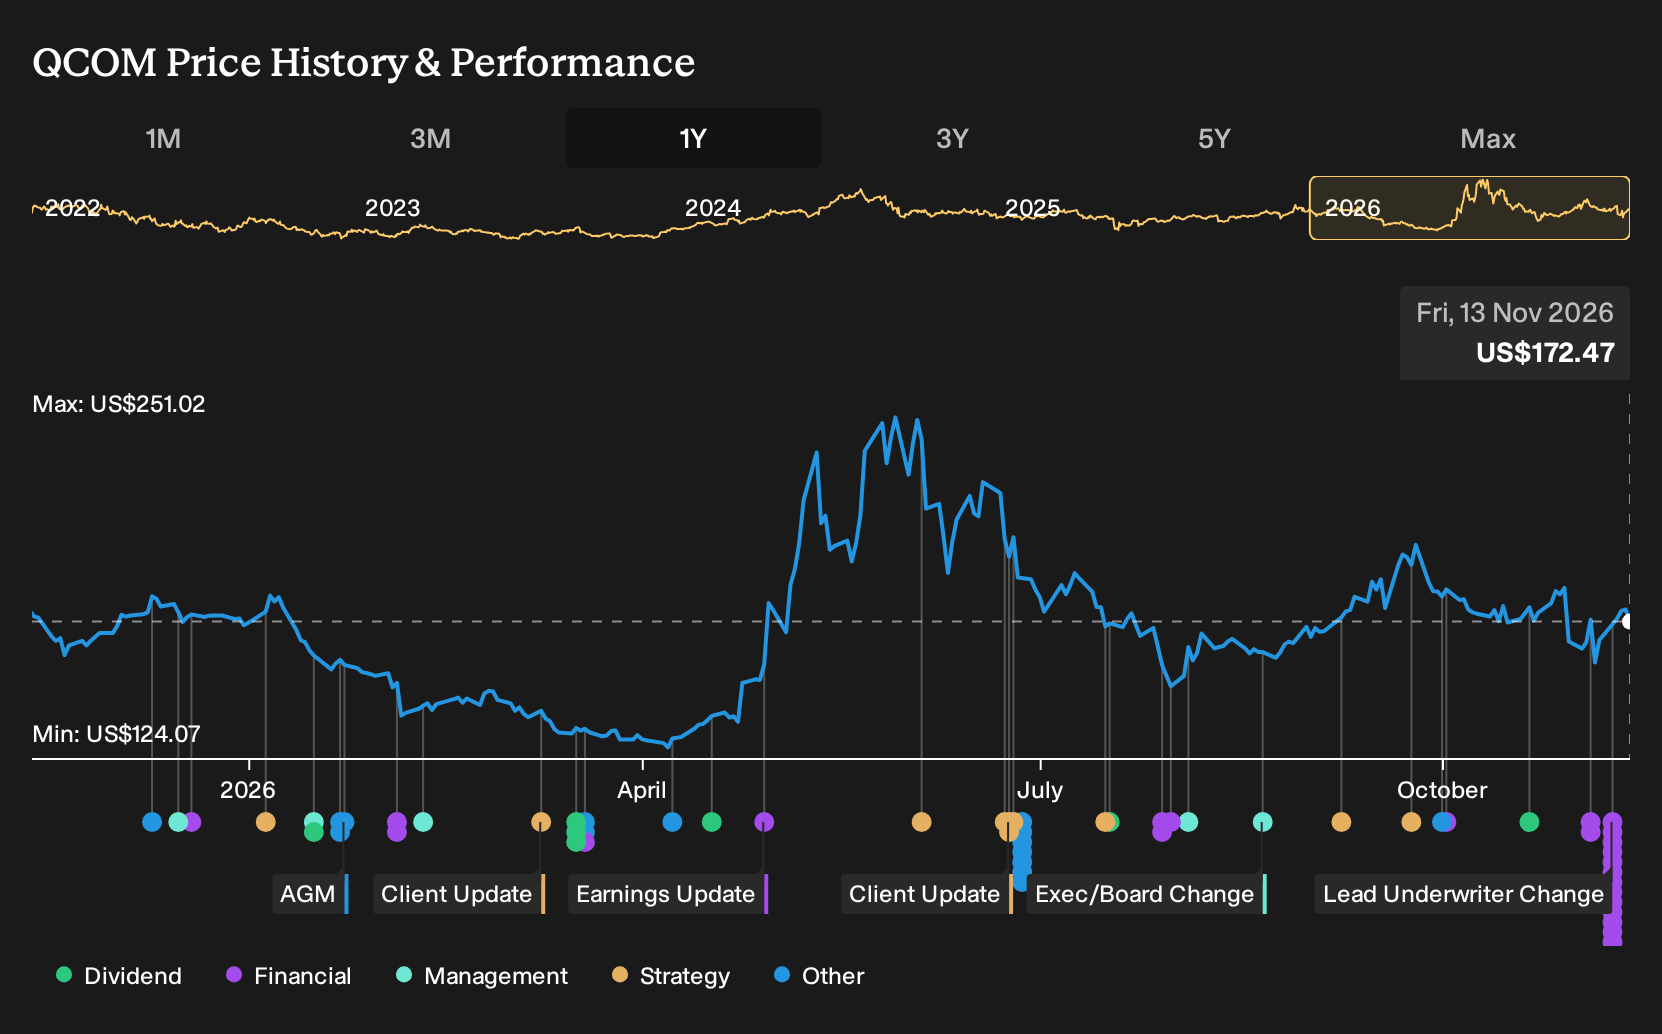
Among the recent updates, the cluster of fixed rate bond offerings in early November 2026 looks most relevant for the current story. QUALCOMM issued several tranches of callable senior unsecured notes with maturities out to 2036, at coupons between 5% and 5.8%. That adds material long term debt funding to a business already leaning more on higher risk borrowing.
For you as a shareholder, this bond activity matters because it affects how QUALCOMM funds the heavy AI and data center build out that management has framed around multi year revenue targets. The key execution test is whether these new resources translate into durable non handset income streams quickly enough to offset handset pressure without leaving investors with lower future flexibility if earnings fall short of guidance.
QUALCOMM's current analyst narrative points to revenues of US$62.7b and earnings of US$12.3b by 2029, based on a forecast 13.3% yearly increase in sales. This view assumes current earnings of about US$13.6b and an earnings decline of roughly US$1.3b by the 2029 estimate year.
Uncover how QUALCOMM's fair value indicates an 8% potential upside to its current price before sentiment around QUALCOMM's handset reset and AI ramp shifts.
Exploring Other Perspectives
One alternate view zooms in on QUALCOMM's data center targets as a possible weak spot rather than a pure opportunity. The most bearish analysts were already pencilling in 2029 revenue of about US$58.1b and earnings of US$11.8b before this guidance and bond spree. You can see how their more cautious narrative could shift again after these conference updates.
Explore 3 other QUALCOMM fair value estimates, including one that suggests it could be worth just $171.59.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your QUALCOMM research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking for more investment ideas beyond QUALCOMM?
Once you have a handle on QUALCOMM's story, it can help to compare it with other opportunities that fit different risk and return profiles using the Simply Wall St Screener.
- Target companies with strong balance sheets and robust fundamentals by scanning our list of solid balance sheet and fundamentals (24 results), which can help if you want financial resilience to be front and center.
- If income is your focus, check out a curated set of higher yielding dividend payers through the 6 dividend fortresses, built for investors who want cash returns alongside potential price moves.
- For those hunting for overlooked opportunities, the 20 high quality undiscovered gems can point you toward under-followed businesses with solid underlying metrics that the market may not be pricing fully.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com