


- Micron Technology (NasdaqGS:MU) faces fresh scrutiny as a senior US Senator urges a ban on Chinese memory rival CXMT in November 2026.
- The Senator cites CXMT's progress in DRAM and high bandwidth memory used in AI servers as a risk to US chipmakers.
- CoreWeave reports very strong Q3 2026 results and higher AI infrastructure spending, which lifts sentiment around suppliers of AI memory and storage.
- The push to restrict CXMT and the upbeat CoreWeave numbers only tell part of Micron's story and risk profile. Check out 2 warning signs (1 major) that Micron Technology investors should know about.
Readers tracking AI hardware demand may want to look beyond Micron and scan a broader group of AI data center suppliers through 53 AI infrastructure stocks.
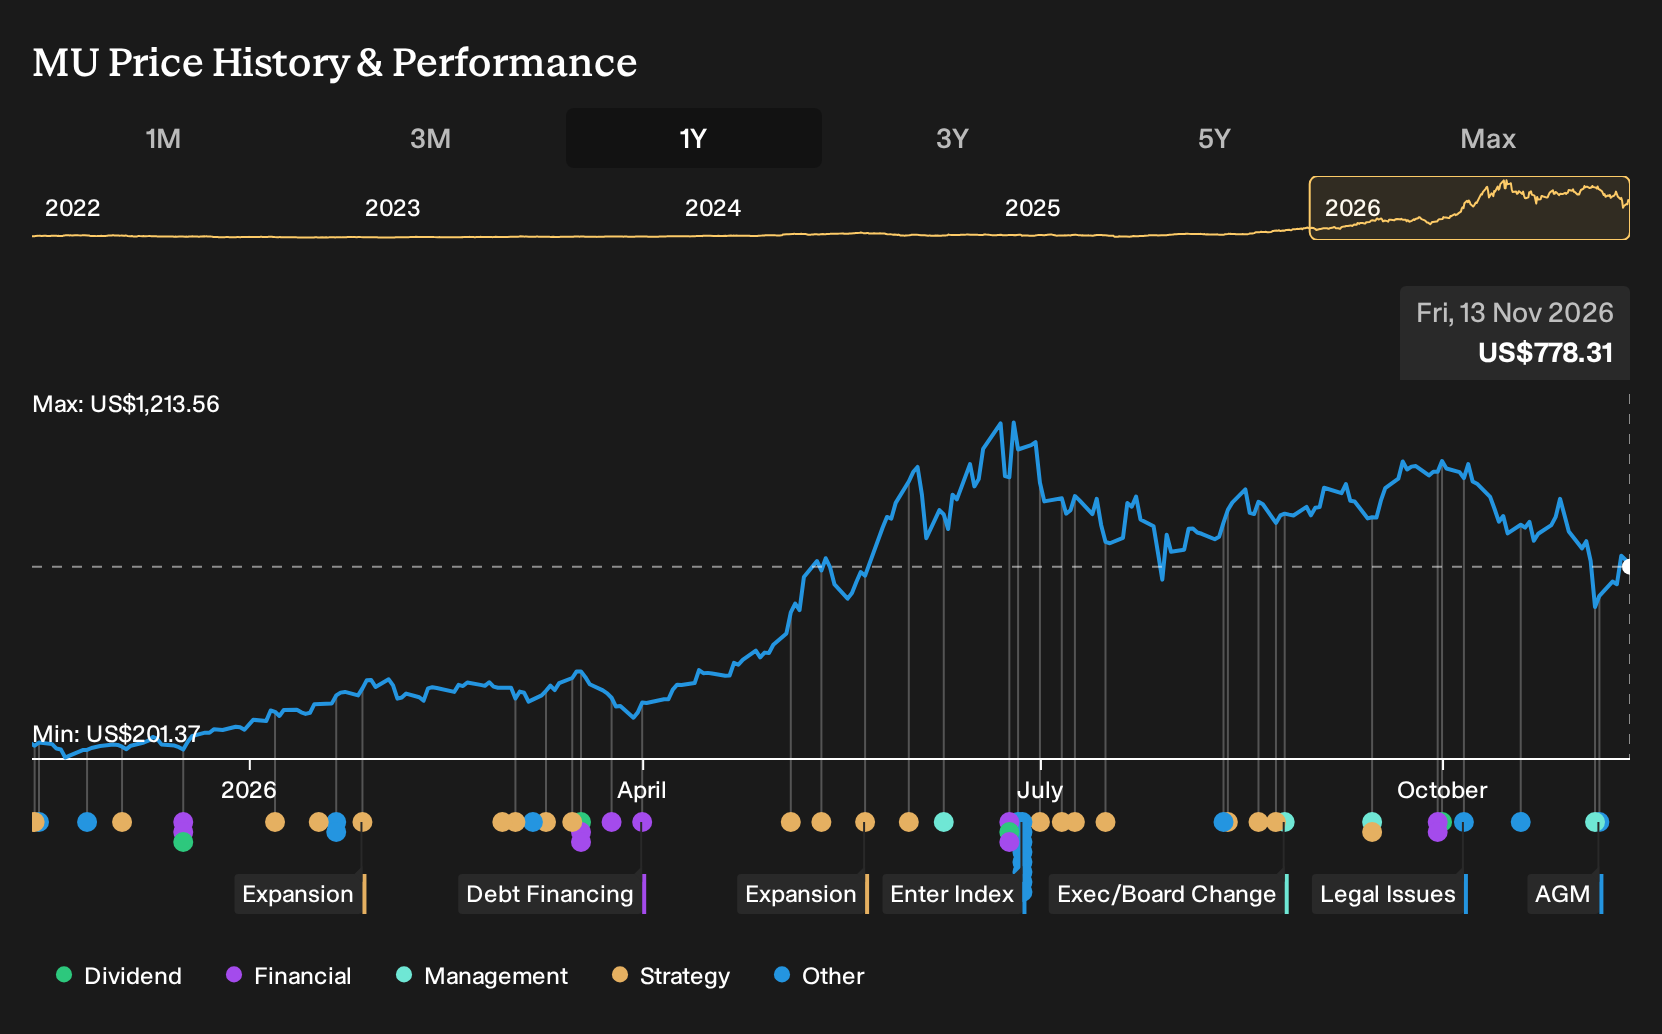
Micron Technology sells memory and storage chips that sit inside AI servers and data centers, so any move to curb Chinese rival CXMT or signs of heavier AI infrastructure spending directly affect the markets where the business competes. The group operates across the US, Mainland China and other key manufacturing hubs, which makes regulatory and customer shifts especially relevant for its risk profile.
What a CXMT ban debate and CoreWeave’s AI spend really change for Micron’s story
For Micron Technology, calls to restrict CXMT and stronger AI infrastructure spending read directly against the existing Narrative that tight DRAM and NAND supply plus long dated customer agreements need to translate into lasting, high margin cash generation. Reduced competitive pressure from a Chinese peer would support that supply discipline, while CoreWeave’s heavier AI outlay reinforces the focus on data center demand as the main driver of memory pricing power. The open question is whether these policy and customer tailwinds outweigh execution risks in fabs, labor and governance as the board prepares for Linnie Haynesworth’s retirement in January 2027 and shifts committee responsibilities.
See how these catalysts shape Micron Technology's path to a $1,561 fair value.
The cleanest test of whether this is working will come from Micron’s next few quarters of disclosures on AI focused customer agreements. Investors can watch for updates on the size and duration of Strategic Customer Agreements for HBM and data center DRAM, any shift in the roughly US$18b of customer deposits, and commentary on competitive dynamics with CXMT as US export policy evolves through 2027.
Add Micron Technology to your Watchlist and get alerts as these catalysts play out.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com