


Veracyte has seen its share price fall hard in recent months, and the drop has pushed fresh attention onto a simple question for investors who care about valuation. Is the current US$24.33 price supported by what the business is earning today and is expected to earn over time?
- Over the past 5 years the stock has declined 50.6%, which puts the focus squarely on whether the current market value still lines up with the underlying earnings power of the diagnostics business.
- Management has lowered future expectations for its key Decipher Prostate test, while also authorizing a US$100m share repurchase. This combination can reshape how investors think about the durability and timing of Veracyte's earnings and cash flows.
- The analysts covering Veracyte have run their own numbers. See what analysts think Veracyte's shares could be worth.
The issue now is whether Veracyte's recent share price level can be justified by its earnings when judged against the Fair Ratio benchmark.
If you are questioning whether Veracyte's US$24.33 price still lines up with its earnings profile after this guidance reset, it can help to compare that mindset across 32 high quality undervalued stocks
Where Does Veracyte Sit on Earnings?
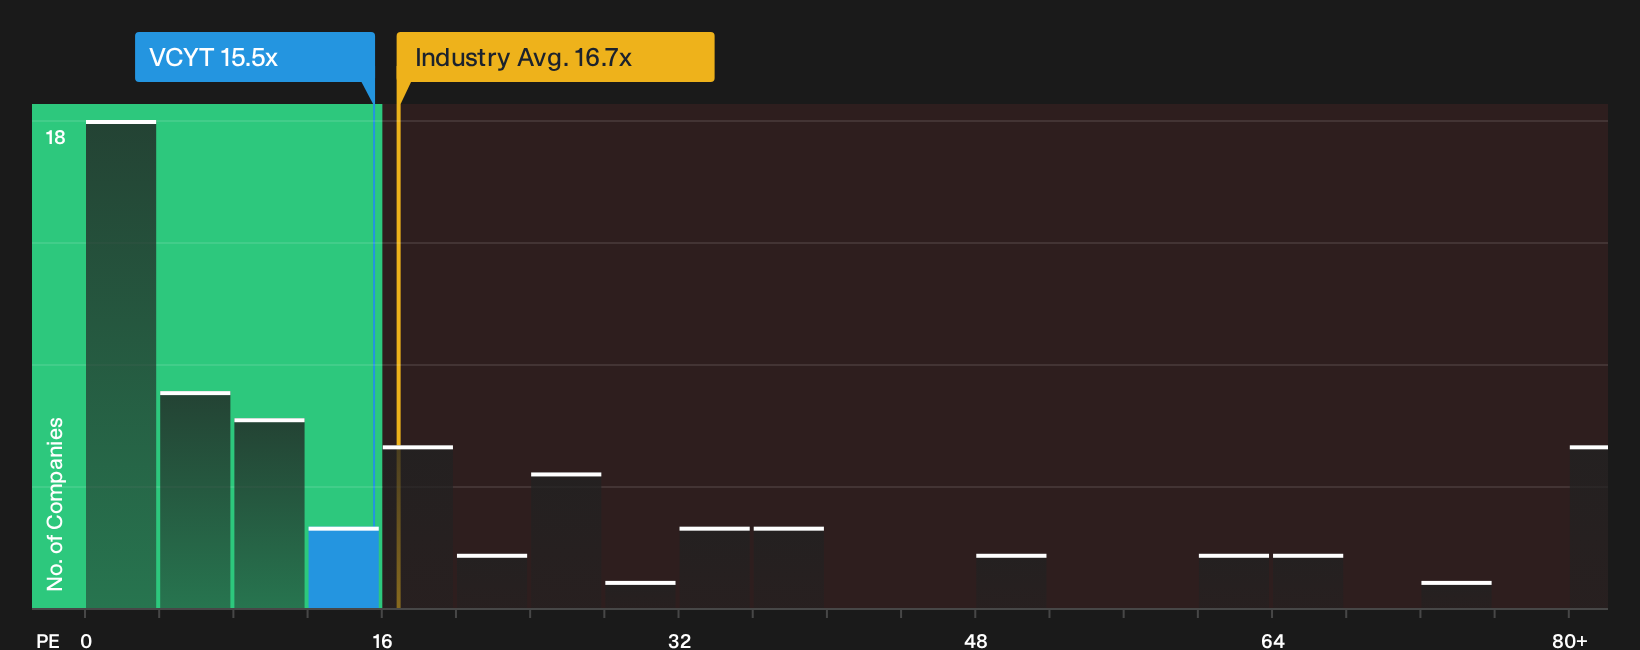
The P/E ratio works well for Veracyte because investors are focused on how its diagnostics earnings stack up against the price being paid today. On this lens, the stock trades on a P/E of about 15.5x, which is slightly below the broader biotech sector average of 16.7x and also below peers at roughly 28.4x.
The Fair Ratio benchmark, which blends Veracyte's own growth profile, profitability, size and risk into a single expected P/E anchor, points to a level very close to where the shares trade now, so the multiple screens about right on this framework. Because the recent cut to the Decipher Prostate outlook has already reset expectations, the current P/E suggests the market is pricing in that guidance change without applying a clear premium or discount relative to what the company's earnings profile would imply. Because the revision to 2026 guidance and the subsequent share price fall have already reset sentiment, the present P/E leaves the stock trading at roughly the valuation that model based screens would suggest is warranted. Explore the numbers behind Veracyte's P/E valuation.
The Veracyte Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Veracyte pick up where this valuation puzzle leaves you. They set out the specific future paths for growth, margins and earnings that would need to play out for the stock to look materially stronger or weaker than it does today on a P/E of 15.5x. Where a single ratio or model gives one neat figure, these scenarios unpack the operating assumptions behind it so you can watch Veracyte's actual results and see how closely reality tracks that implied future on the Community page.
One of the top narratives on Veracyte: 59% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"Expanding cancer diagnostics portfolio and clinical evidence are driving greater physician adoption, market penetration, and long-term top-line growth..."
Discover why this Narrative puts Veracyte at 59% undervalued.
Veracyte’s valuation is only one piece of the decision
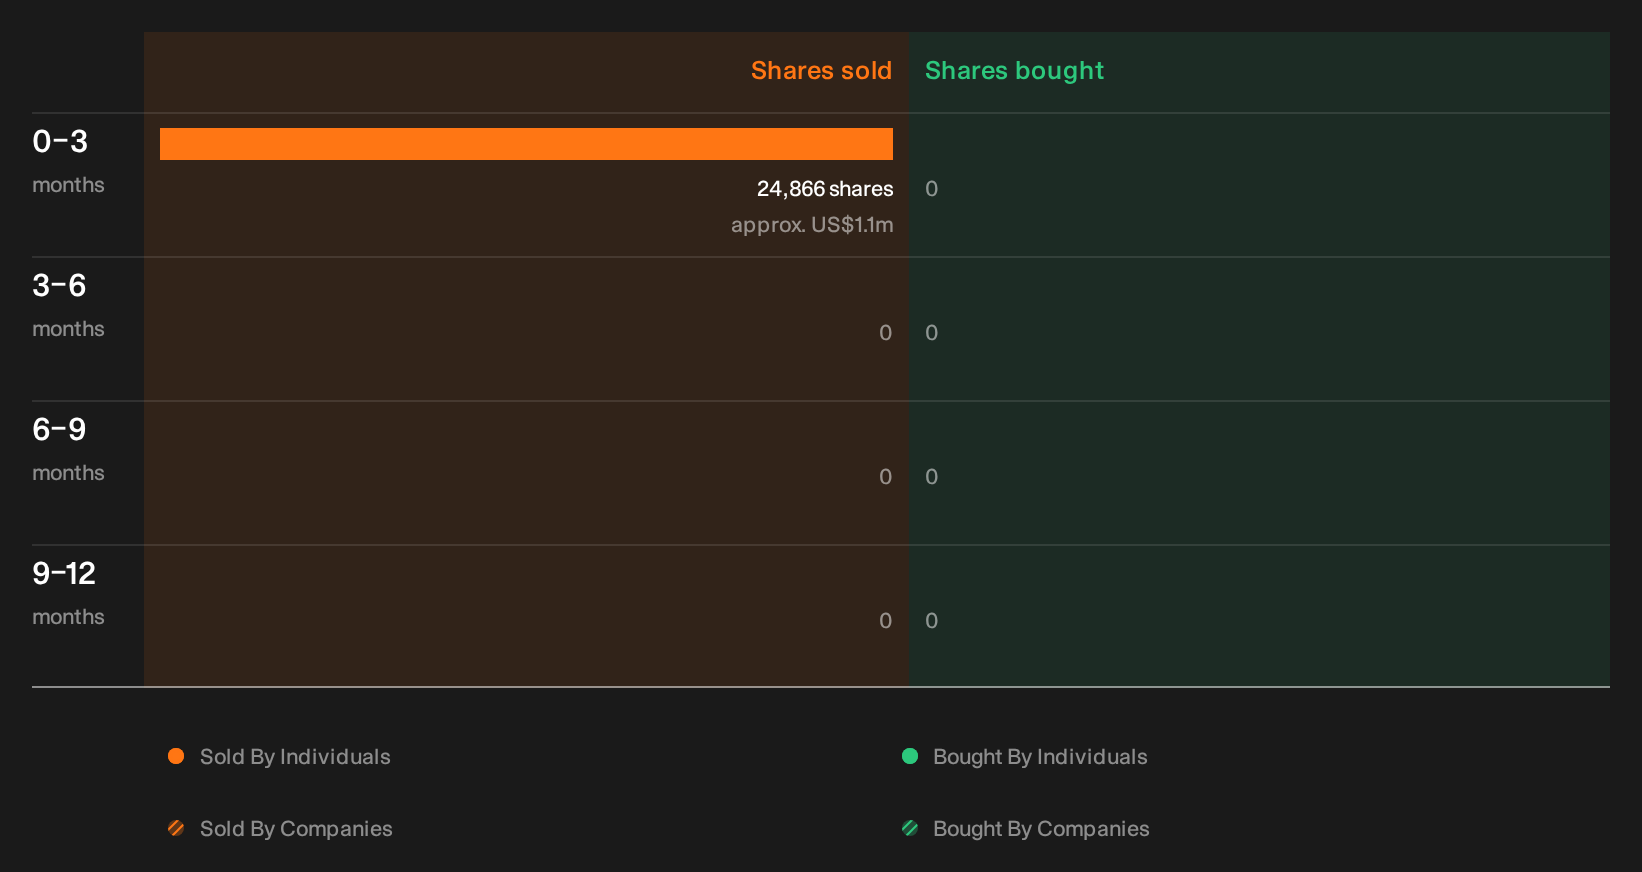
Price and earnings tell part of the Veracyte story, but our checks have also highlighted recent share activity by people inside the business that you may want to review more closely. See the recent insider selling flagged for Veracyte.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com