


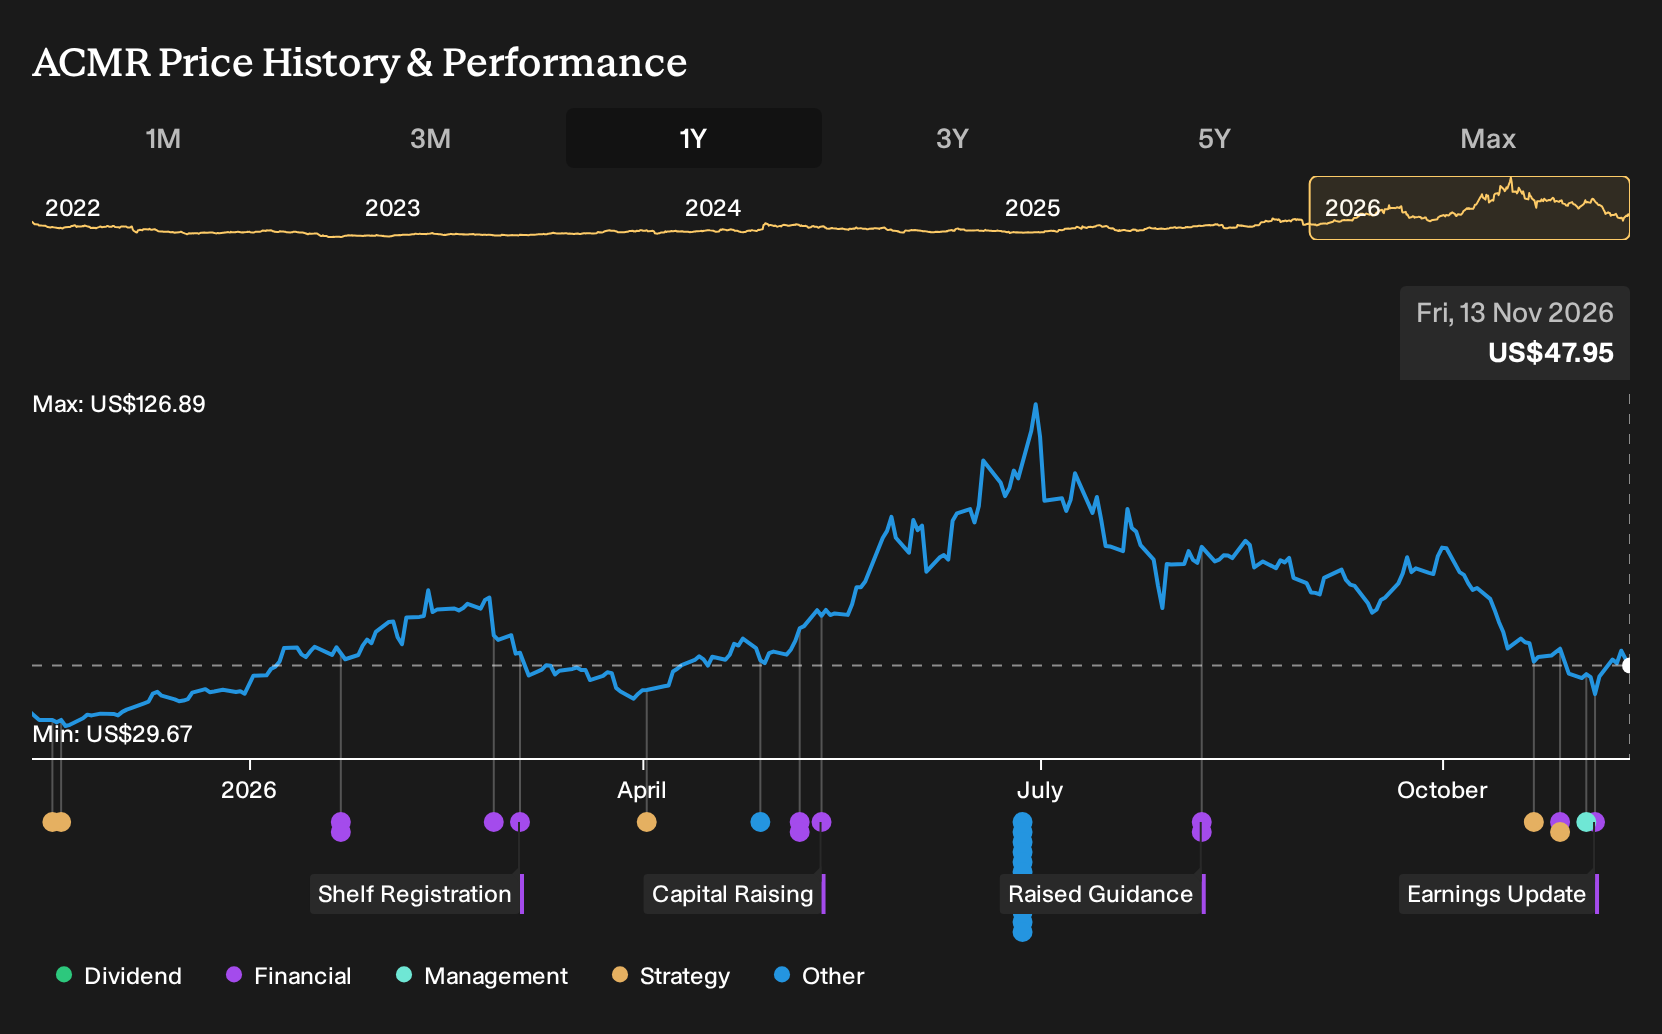
- ACM Research reported third quarter 2026 sales of US$367.69 million and net income of US$1.54 million, with nine month 2026 figures of US$891.87 million in sales and US$107.84 million in net income. The company also appointed Yue Ma as Chief Operations Officer, effective October 1, 2026.
- The latest results show higher sales alongside much lower quarterly net income, which highlights pressure on recent profitability even as ACM Research continues to scale its operations and leadership team.
- The focus now turns to how ACM Research's mixed revenue and profit picture could reshape the existing investment narrative around margin quality.
Scan beyond ACM Research and explore other semiconductor and equipment players experiencing earnings pressure alongside scaling sales in our hand picked 32 high quality undervalued stocks list.
ACM Research Investment Narrative Recap
To stay comfortable as a shareholder in ACM Research, you need to believe the business can turn growing sales into consistent earnings quality. The analyst consensus Narrative on Simply Wall St leans on demand tied to AI, advanced packaging and more complex wet cleaning. The latest quarter did not change that long term story, but the sharp gap between revenue and quarterly profit puts more scrutiny on execution.
In the short term, the key catalyst is still how quickly ACM Research converts its backlog in advanced packaging, plating and newer tools into higher margin shipments. The biggest risk remains concentration in mainland China and exposure to export controls. The Q3 profit compression makes that risk feel more immediate, because the cushion from current earnings now looks thinner.
The appointment of Yue Ma as Chief Operations Officer appears directly connected to these execution questions. A COO with a recent background at ASML in architecture and technical roles gives ACM Research additional operational depth at a time when tool mix, quality and delivery timing are central to the thesis.
For you as an investor, this management change ties back to the catalysts that analysts highlight. Effective operations leadership will matter for ramping panel level electroplating, scaling PECVD and furnace platforms, and balancing reliance on China with newer regions. If those programs run smoothly, the recent margin pressure may look more like a growing pain than a structural issue, but that remains to be proven in future results.
ACM Research's narrative projects US$2.3b revenue and US$322.7 million earnings by 2029. This assumes 25.9% yearly revenue growth and an earnings increase of about US$206.8 million from US$115.9 million today.
Discover why ACM Research's fair value indicates a 116% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view on ACM Research puts more weight on the risk that core single wafer cleaning stays under pressure, and that newer tools do not fully pick up the slack. The most cautious analysts were already working with roughly US$2.1b of 2029 revenue and about US$307.2 million in earnings before this result. That is a much more restrained narrative than the consensus, and the latest profit squeeze could push forecasts in either direction. Use it as a reminder that opinions differ widely and that it can be useful to explore several viewpoints before deciding how this quarter fits your own story for the stock.
Explore 4 other ACM Research fair value estimates, including one that suggests it could be worth just $58.74!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ACM Research research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ACM Research. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, making it easy to evaluate ACM Research's overall financial health at a glance.
Looking for more ACM Research style ideas?
If this quarter has sharpened your view on ACM Research and you want a broader watchlist, the Simply Wall St Screener can help you line up other candidates that fit your style, risk appetite and time horizon.
- If capital preservation sits high on your list, filter for companies with stronger risk profiles using our 31 resilient stocks with low risk scores and see which ones deserve a spot on your radar.
- For investors who prefer durable businesses with cleaner finances, scan a list of solid balance sheet and fundamentals (24 results) and compare those balance sheets with what you see at ACM Research.
- If you are hunting for underfollowed opportunities with better fundamentals, broaden your search by reviewing our 20 high quality undiscovered gems that might complement or compete with your ACM Research thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com