


Earnings setback reshapes the BIPROGY stock story
BIPROGY (TSE:8056) just put fresh numbers on the table, and they matter. Half year sales came in at ¥201,130 million with net income of ¥11,150 million, both below the prior period.
Recent trading tells a mixed story. BIPROGY’s share price has rallied, with a 12.52% 7 day share price return and a 4.88% 90 day gain. However, the year to date share price return is down 9.46% and the 1 year total shareholder return has fallen 14.05%, even though the 5 year total shareholder return is up 58.79%.
Compare BIPROGY’s earnings setback with a curated group of IT and software peers that currently screen as 19 high quality undervalued stocks to see how this story compares on value and quality.
BIPROGY shares have bounced after weaker earnings, yet the stock still trades below both analyst targets and one intrinsic value estimate. Where does a fair price really sit inside that gap?
Price-to-Earnings of 17.4x: Is it justified?
BIPROGY closed at ¥4,880 with a trailing P/E of 17.4x, which places the stock on a richer earnings multiple than many domestic IT peers.
The P/E ratio compares what investors are paying today for each unit of current earnings. For a software and IT services group like BIPROGY that reports ¥27,036 million in net income and offers recurring cloud and outsourcing revenue, that lens focuses attention on how durable those profits look and how much future progress is built into the price.
Several data points pull this valuation in different directions. The shares trade on a higher P/E than the JP IT industry average of 15.4x, suggesting the market is assigning a premium to BIPROGY even though earnings declined 11.4% over the past year and return on equity of 14.7% has been flagged as low. At the same time, the 17.4x multiple is described as good value relative to a fair P/E estimate of 23.6x and a peer average of 27.3x. This comparison suggests investors may be applying a lower earnings multiple than those reference points.
That tension shows up clearly against sector benchmarks. Compared with the JP IT industry, BIPROGY looks expensive on P/E alone. However, against the regression-based fair ratio and the higher peer average, the same 17.4x looks conservative by comparison and indicates a gap between the current valuation and those fair value markers if sentiment were to change.
Explore the SWS fair ratio for BIPROGY.
Result: Price-to-Earnings of 17.4x (ABOUT RIGHT)
Still, the recent earnings decline and ongoing year to date share price weakness could challenge confidence in BIPROGY if contract wins or cloud demand soften.
Find out about the key risks to this BIPROGY narrative.
Another view on BIPROGY’s value
The P/E discussion paints BIPROGY as slightly expensive against the JP IT sector, yet good value against its own fair ratio. A different lens comes from the SWS DCF model, which values the shares at ¥6,172.73 versus today’s ¥4,880, implying the stock trades at a discount to estimated future cash flows.
That gap suggests the cash flow outlook and the earnings multiple are not telling exactly the same story, which leaves a simple question: Which signal do you treat as the anchor when you size any position in BIPROGY?
Look into how the SWS DCF model arrives at its fair value.
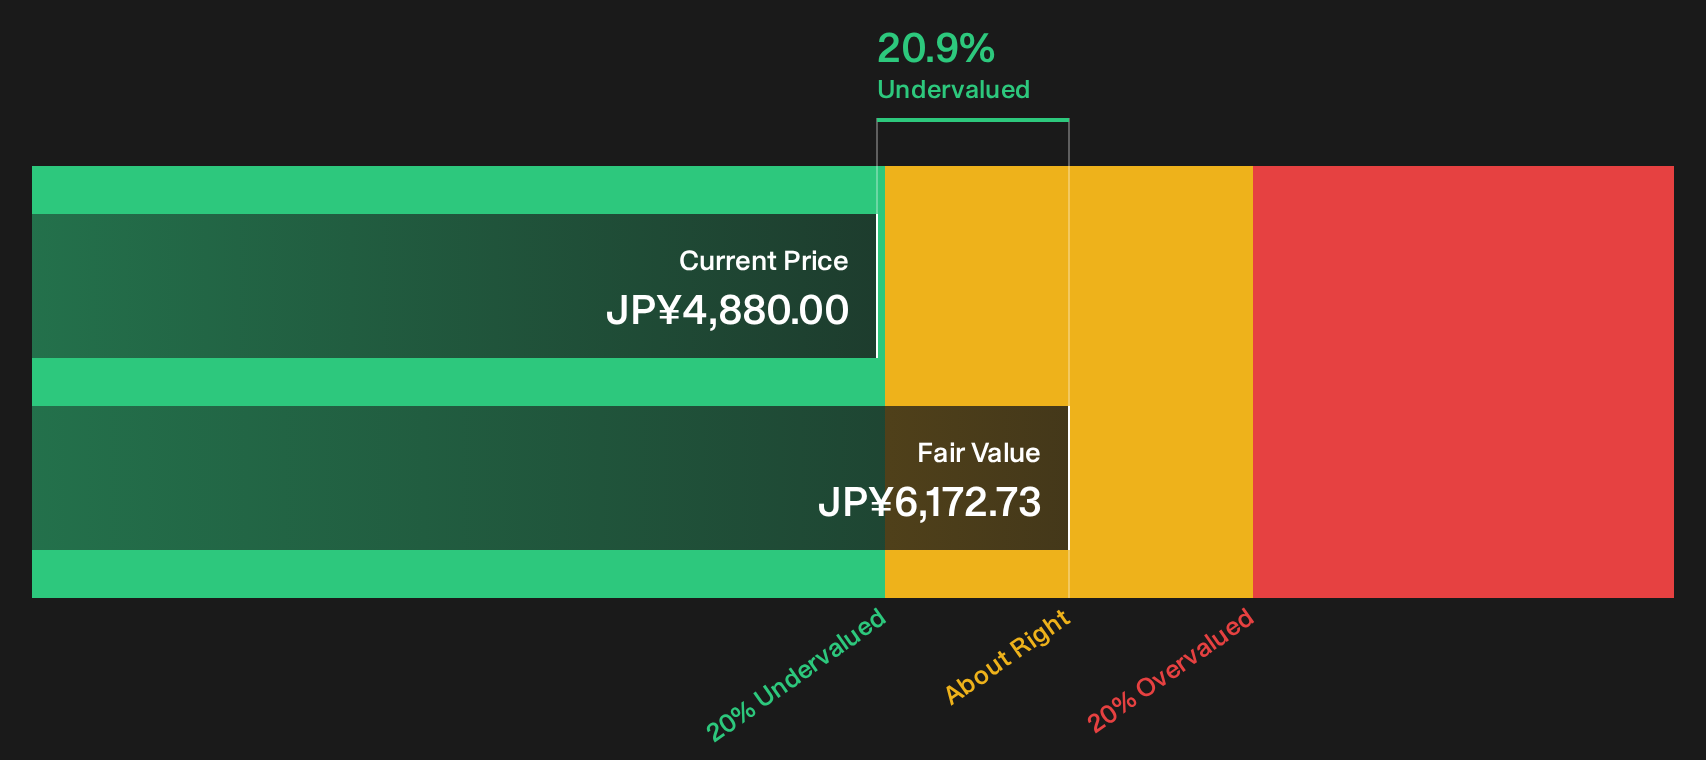
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out BIPROGY for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around BIPROGY can easily pull you in opposite directions, so check the full set of data points, weigh the trade offs, and then judge for yourself with 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond BIPROGY?
If BIPROGY has sharpened your thinking on valuation, do not stop here. Use the Simply Wall Street Screener to surface fresh opportunities that match your priorities.
- Explore potential opportunities by scanning a focused list of smaller, higher risk companies using the 1 elite penny stocks with strong financials.
- Look for quality at a sensible price with the help of the 19 high quality undervalued stocks before the market fully catches on.
- Prioritise resilience and balance sheet strength by filtering companies through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com