


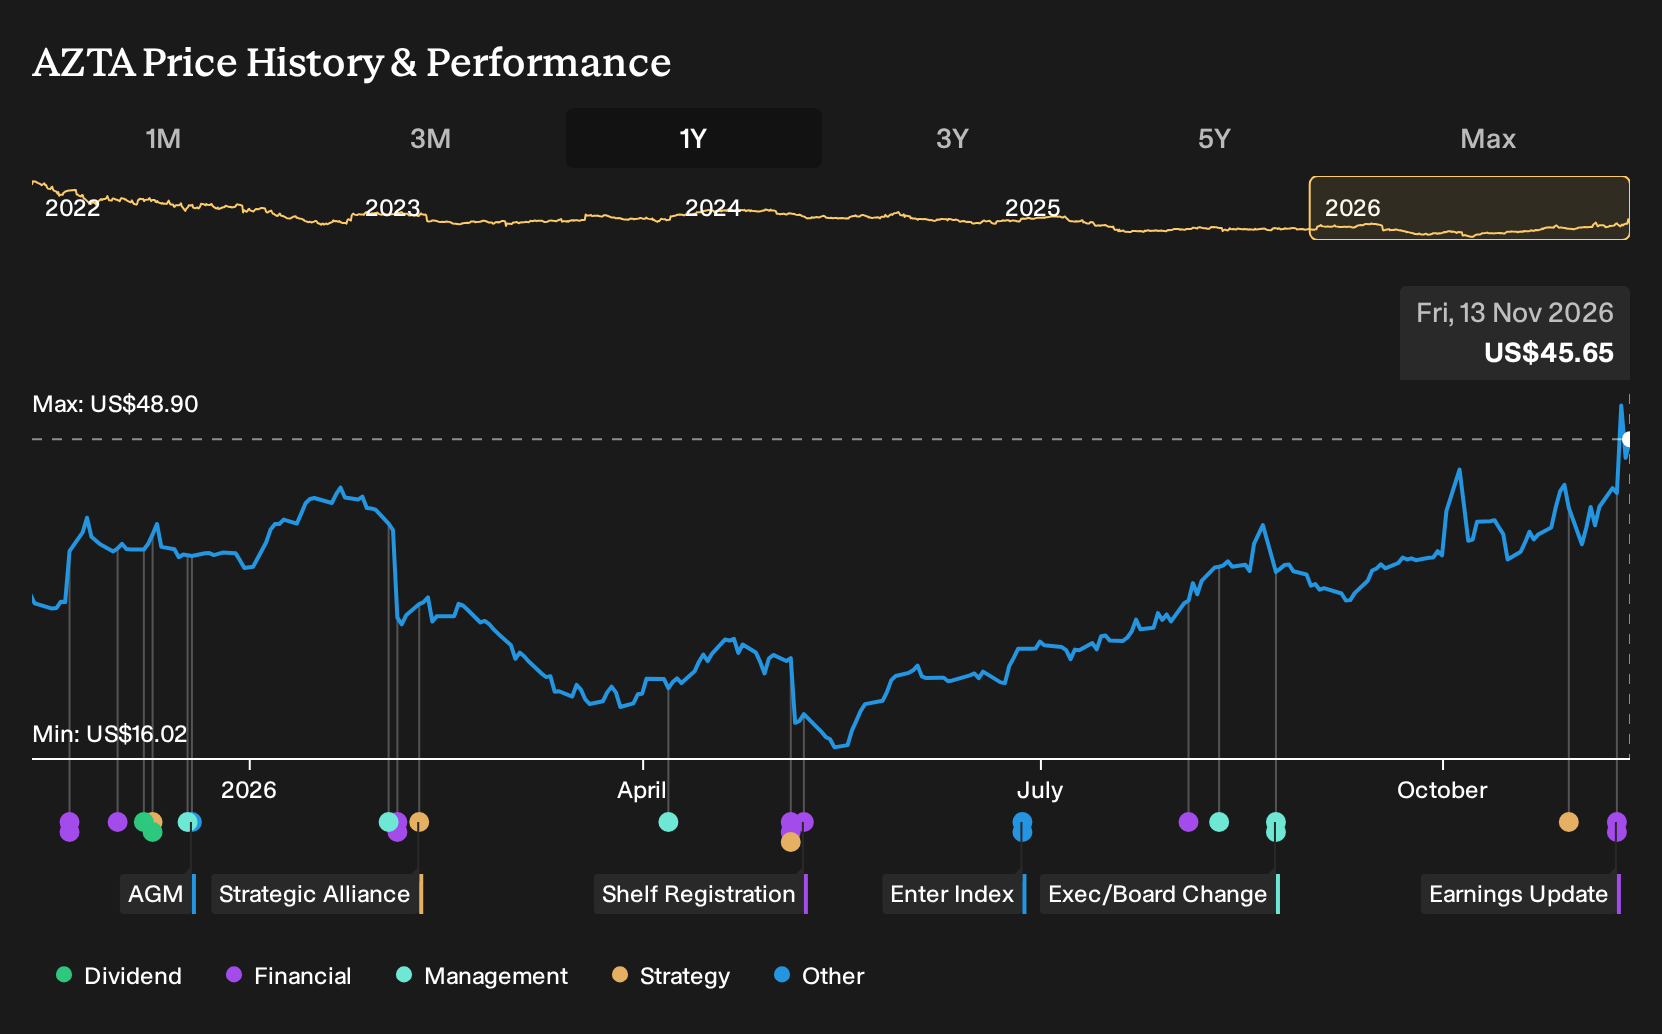
- Azenta reported fiscal 2026 revenue of US$621.7 million and a quarterly adjusted profit improvement, alongside fiscal 2027 revenue guidance of US$648 million to US$660 million from continuing operations.
- The update paired earnings and guidance with fresh agreements in gene synthesis and synthetic biology services, indicating a deeper focus on Multiomics capabilities and recurring life sciences workflows.
- We will examine how Azenta’s investment narrative is affected by the new 2027 revenue outlook and gene synthesis expansion.
See how Azenta’s latest guidance compares with peers by reviewing our curated list of 36 healthcare AI stocks that are also focusing on genomics, multiomics, and AI-enabled lab workflows.
Azenta Investment Narrative Recap
For Azenta, the big picture an investor needs to believe in is that recurring sample management and Multiomics services can offset lumpier capital equipment cycles and eventually support consistent profitability. The latest update keeps that story mixed. Fiscal 2026 revenue of US$621.7 million and 2027 guidance of US$648 million to US$660 million point to steady activity, but the fiscal 2026 net loss of US$166.99 million shows the turnaround is not finished.
The analyst consensus Narrative on Simply Wall St highlights execution in Multiomics and capital equipment as the key near term catalyst, and that still holds. Margin improvement and better gene synthesis productivity remain the operational swing factors. The biggest risk is that goodwill impairments, governance issues, and weaker North America Multiomics demand persist, which could keep reported earnings and investor confidence under pressure despite stable top line guidance.
The fresh 2027 revenue outlook of US$648 million to US$660 million is the announcement that most closely ties the recent earnings release to Azenta’s catalysts. It frames what success needs to look like as the business pushes deeper into gene synthesis, synthetic biology services, and higher value contracts tied to life sciences automation and biobanking.
For you as a potential or current shareholder, that range provides a reference point to judge whether deployment into Elegen based Multiomics capabilities and automated stores is tracking to plan. Any sustained shortfall against this guidance, especially if paired with further impairments or limited progress in North America, would directly test the thesis that Azenta can lift margins while keeping recurring revenue stable.
Azenta's narrative projects US$696.4 million revenue and US$23.2 million earnings by 2029. This projection is based on analysts assuming 4.3% yearly revenue growth and an earnings change of roughly US$135 million from the current loss of US$112.1 million to the forecast profit of US$23.2 million.
Uncover why Azenta's fair value indicates a 17% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One bearish twist in the Azenta story is the concern that governance setbacks and earlier goodwill impairments keep dragging on confidence. The lowest analysts were already modeling 2029 earnings of about US$23.3 million on roughly US$702.6 million revenue before this latest update. That is a much harsher lens. Use this as a reminder that smart people can look at the same information and reach very different conclusions. Treat this fresh guidance as a cue to compare several viewpoints yourself.
Explore another Azenta fair value estimate, including one that suggests as much as 45% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker, dig into the data and build a conviction that's truly your own.
- A great starting point for your Azenta research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Azenta. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Azenta's overall financial health at a glance.
Looking For More Azenta Style Investment Ideas?
If the Azenta story has you thinking about where else recurring revenue, solid balance sheets, or differentiated business models might show up, screening across the wider market can surface a few fresh angles to research next.
- For investors who want potential upside without paying too much for quality, a focused list of 32 high quality undervalued stocks can highlight companies where fundamentals and price are pulling in different directions.
- If capital protection matters as much as growth, consider companies with sturdier finances by reviewing the list of solid balance sheet and fundamentals (24 results), which concentrates on businesses with stronger balance sheets and underlying fundamentals.
- When you want fresher ideas that are not heavily followed yet, a curated set of 20 high quality undiscovered gems can point you toward under-the-radar stocks with stronger financial foundations.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com