


Arcus Biosciences (RCUS) just posted third quarter results, with revenue of US$9 million and a net loss of US$128 million. That compares with US$26 million in revenue and a US$135 million loss a year earlier.
Against that backdrop, Arcus Biosciences shares have come under pressure, with the 30 day share price return down 22.6% and the 90 day move down 40.9%. However, the 3 year total shareholder return is still positive, while the 5 year record remains deeply negative.
Scan beyond Arcus Biosciences and compare this latest setback with a hand-picked 20 high quality undiscovered gems that also pair clinical ambition with stronger financial foundations.
After a 40.9% slide over 90 days and a last close of US$17.43, Arcus Biosciences now trades well below both analyst targets and intrinsic value estimates. How wide is that gap in practical terms for investors?
Most Popular Narrative: 57% Undervalued
At a last close of $17.43 against a fair value narrative of $41, the analyst consensus Narrative on Simply Wall St frames Arcus Biosciences as heavily discounted. That gap is described as being built on detailed assumptions about future trials, margins and cash flows rather than sentiment alone.
Arcus Biosciences is advancing the Phase III PEAK-1 trial of casdatifan plus cabozantinib in second-line RCC, now guided to complete enrollment by the end of 2026 with supportive ARC-20 combination data. A positive outcome could open a multi billion dollar second-line contribution to revenue and earnings.
See why 10 investors see Arcus Biosciences as 57% undervalued.
Result: Fair Value of $41 (UNDERVALUED)
Still, the Arcus Biosciences story can break if casdatifan’s anemia and hypoxia curb real world use, or if regulatory decisions drag out timelines and costs.
Find out about the key risks to this Arcus Biosciences narrative.
Another View: SWS DCF Versus The Narrative
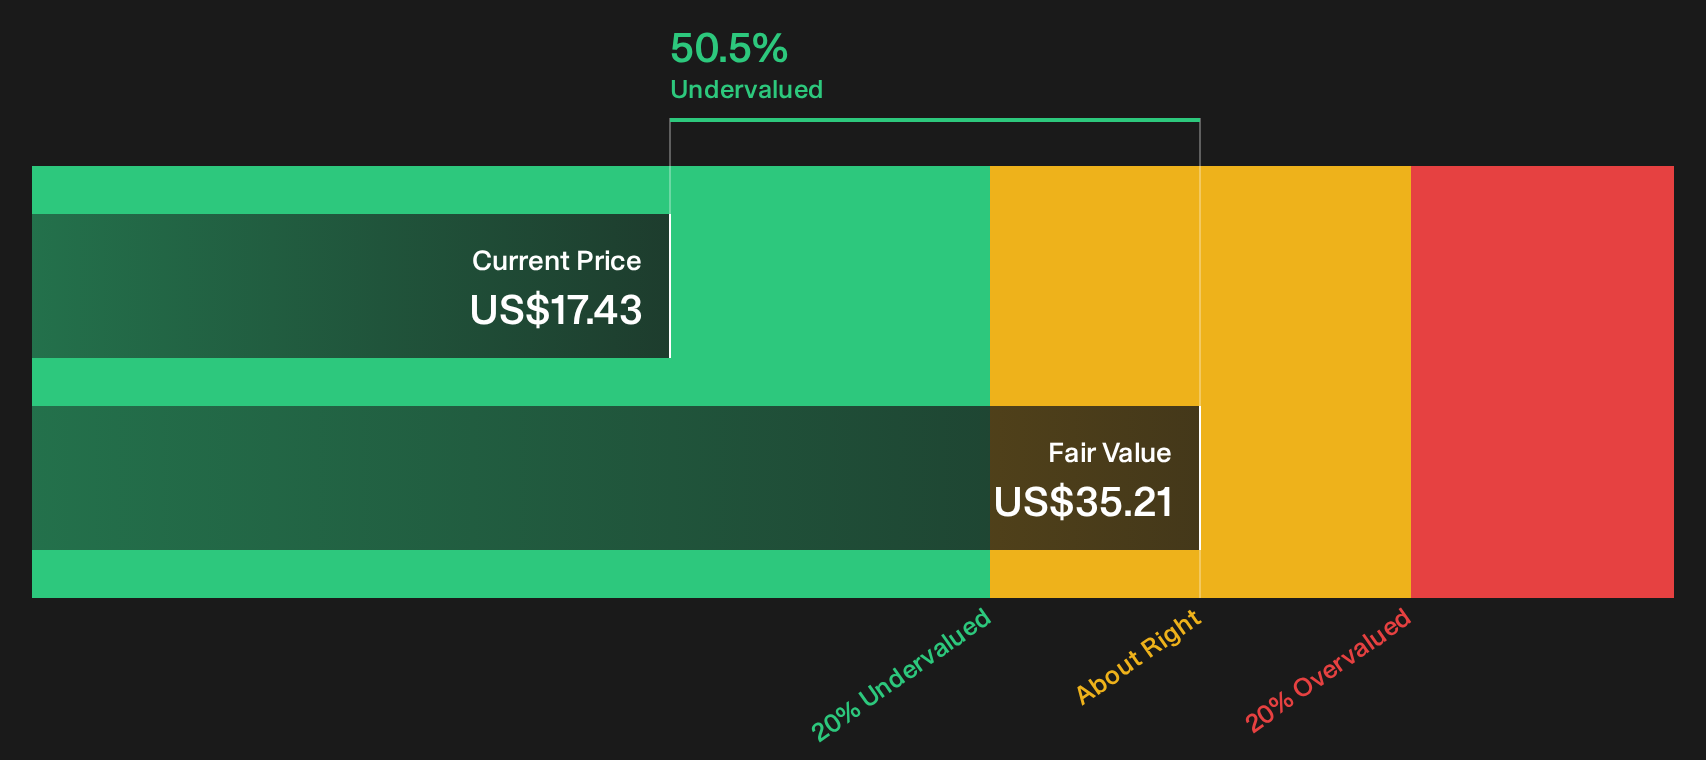
Analysts frame Arcus Biosciences as 57% undervalued at a fair value of $41, yet the SWS DCF model comes in lower at $35.21. Both see upside from $17.43, but the gap between $35 and $41 raises a simple question for you: Which set of assumptions feels more realistic?
For readers who want to see how that cash flow based estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sentiment around Arcus Biosciences is clearly split, with real worry sitting alongside genuine optimism, so move quickly to review the numbers and stress test the thesis for yourself with the 2 key rewards and 2 important warning signs
Looking for more ideas beyond Arcus Biosciences?
Do not stop at Arcus Biosciences. Broader opportunities across the market can help you pressure test your thinking and avoid anchoring on a single story.
- Target steadier performers by scanning a 31 resilient stocks with low risk scores that prioritises resilience when conditions get choppy.
- Hunt for quality on sale through a 32 high quality undervalued stocks that filters for strong fundamentals at prices that lag underlying business strength.
- Balance offense and defense by checking a list of solid balance sheet and fundamentals (24 results) to see which companies pair staying power with room for future execution.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com