


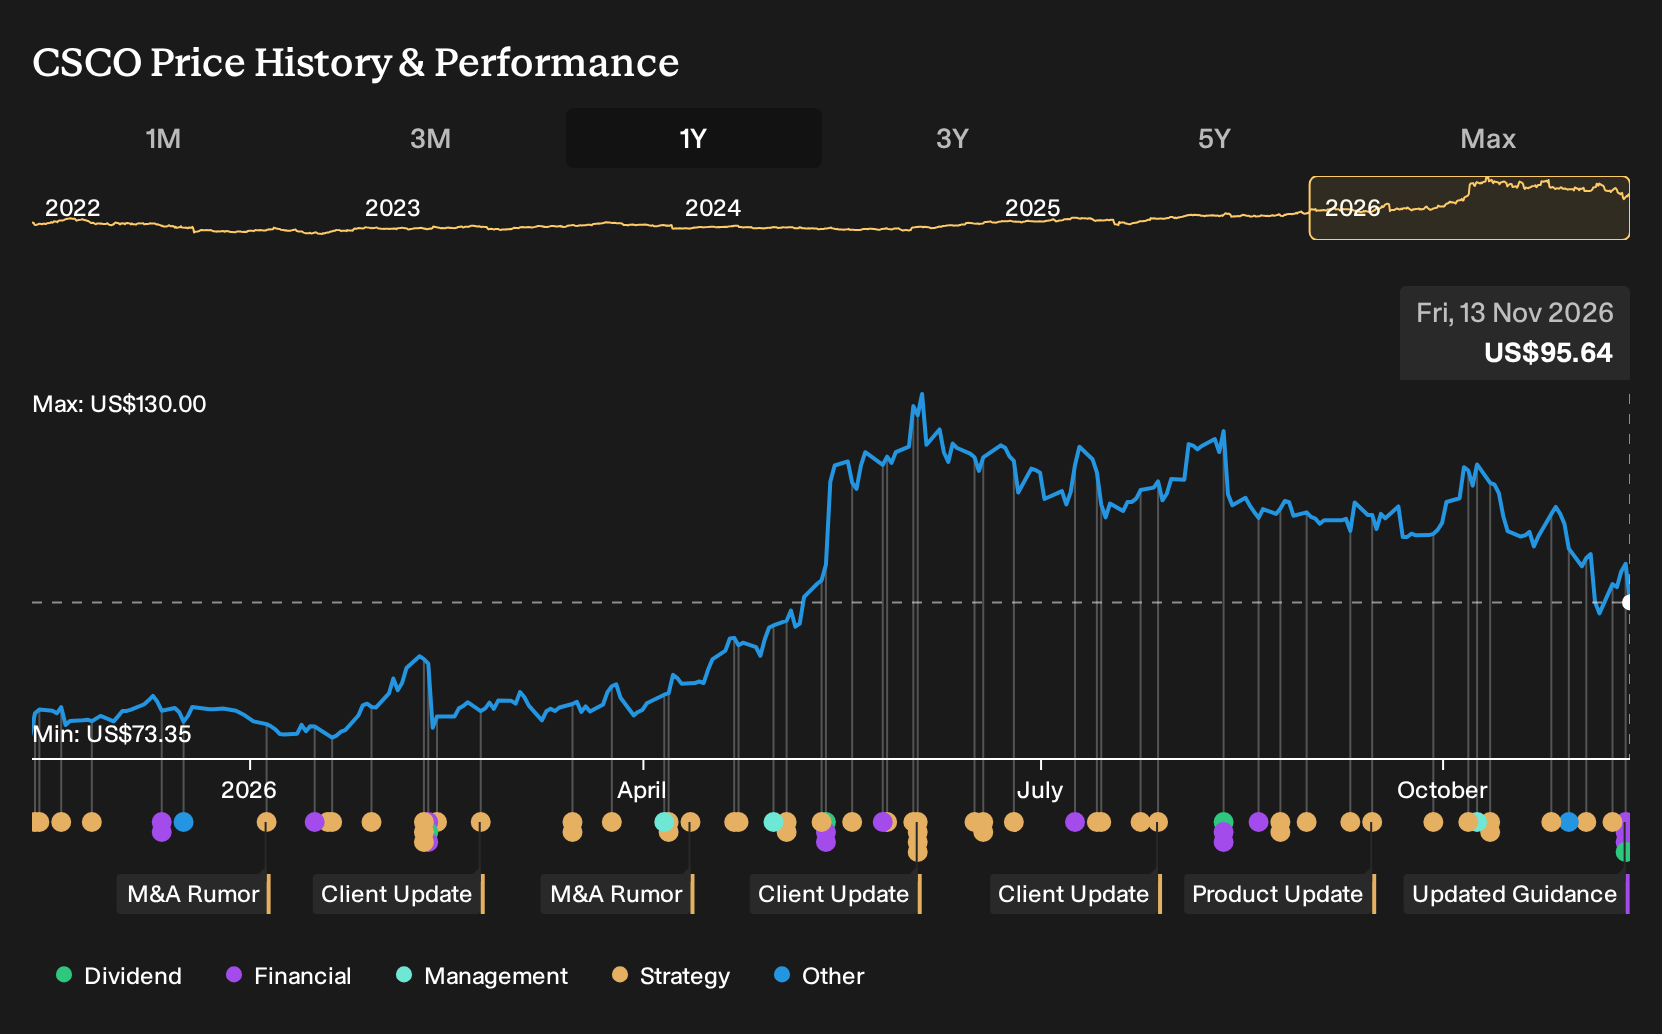
- Cisco Systems reported fiscal Q1 2027 results with revenue of US$18.52b and net income of US$4.55b, raised full year 2027 guidance, and issued Q2 targets alongside an affirmed US$0.42 quarterly dividend.
- The updated outlook includes projected fiscal 2027 revenue of US$74.8b to US$75.8b and a GAAP EPS range of US$4.38 to US$4.44, while management highlighted rising AI infrastructure demand along with pressure on gross margins.
- We will now look at how Cisco Systems' raised 2027 revenue guidance and margin pressure may influence the longer term investment narrative.
Scan Cisco Systems' AI driven print against a hand picked group of infrastructure peers by checking which companies are powering the same build out in our 53 AI infrastructure stocks
.Cisco Systems Investment Narrative Recap
Cisco Systems is still a story about whether the shift from classic networking hardware into AI infrastructure, security and software can support steady, high quality earnings. The raised fiscal 2027 guidance, including projected revenue of US$74.8b to US$75.8b and GAAP EPS of US$4.38 to US$4.44, points to management confidence in current demand. The near term swing factor is execution on hyperscaler AI build outs as product mix tilts toward AI hardware while gross margin pressure remains front of mind.
The largest operational risk right now sits exactly where kapirey, a Simply Wall St Community investor who wrote the Narrative, puts it for mega caps. Cisco is already very large, is seeing capex intensity rise with AI investments and faces tough rivals in cloud and AI networking. That combination means any stumble on AI orders, deployment timing or pricing could matter more for the share price than a single quarter of strong results.
The most relevant fresh datapoint is Cisco’s decision to lift its fiscal 2027 hyperscaler AI infrastructure revenue target to US$9b while keeping Q2 revenue guidance at US$18.0b to US$18.2b and GAAP EPS at US$1.07 to US$1.09. That pairing anchors the current AI build out as the key operational catalyst, even as near term guidance still reflects sequential revenue moderation.
For anyone watching catalysts and risks, this tighter AI focus cuts both ways. Higher AI revenue concentration sharpens Cisco Systems’ exposure to a small set of very large customers, exactly the customer risk kapirey highlights. At the same time, reaffirming a US$0.42 quarterly dividend signals management’s willingness to keep returning cash while investing heavily in AI hardware and security, which keeps the income and execution stories running side by side.
Using revenue rising 7.2% a year and a future profit margin of 20.0%, kapirey frames Cisco Systems’ own fair value at US$110.56, arguing that this earnings power, if sustained through the AI, security and software transition, can justify that valuation for patient holders.
Discover why Cisco Systems' fair value indicates a 16% potential upside to its current price. This reflects a discount that could narrow faster than many investors expect.
Exploring Other Perspectives
Not everyone reads Cisco Systems’ raised guidance as a simple win. The most pessimistic analysts focus on the risk that AI networking demand was front loaded, with their pre earnings models still pointing to revenue of about US$78.0b and earnings of roughly US$19.3b by 2029. Those figures underpin a much more cautious story around how durable today’s AI orders really are. You can treat this updated guidance as a chance to compare that darker scenario with more upbeat views and decide which assumptions feel closer to your own.
Explore 5 other Cisco Systems fair value estimates, including one that suggests it could be worth just $110.56.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Cisco Systems research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Cisco Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cisco Systems' overall financial health at a glance.
Looking For More Ideas Beyond Cisco Systems?
If Cisco Systems has sharpened your interest in where capital might work hardest next, cast the net wider with a few focused screens that filter for different strengths across the market.
- For investors who want potential upside without ignoring financial resilience, consider a 20 high quality undiscovered gems that pair strong fundamentals with lower visibility.
- If capital protection ranks high on your list, filter for resilience using a 31 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Income focused readers can zero in on cash returns by scanning a 6 dividend fortresses that combine higher yields with fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com