


- Orkla reported third quarter 2026 results with sales of NOK 17,541 million and net income of NOK 1,737 million. The nine month figures showed lower sales and earnings compared with the prior year.
- The earnings mix shows Orkla generating higher quarterly net profit despite weaker sales, yet reporting sharply lower nine month earnings per share. This highlights pressure on profitability over the broader period.
- We will look at how Orkla's mixed nine month earnings profile reshapes the investment narrative built around acquisitions and efficiency measures.
Orkla Investment Narrative Recap
To own Orkla, you need to be comfortable with a story built on steady branded consumption, bolt on deals and cost programmes that take time to show through. The third quarter shows that picture is intact on a shorter view, with NOK 17,541 million in revenue and NOK 1,737 million in net income, even as earnings per share from continuing operations softened.
The bigger swing factor right now is execution on restructuring at Orkla Health and Orkla Food Ingredients while input costs remain sensitive. The nine month drop in net income to NOK 5,094 million underlines that risk. If anything, the latest results keep the spotlight firmly on margins rather than creating a new near term catalyst.
The analyst consensus Narrative on Simply Wall St highlights bolt on acquisitions in core food and snack categories as a key driver over time, including Go Tan, The European Candy Group and Phoenix Brands. The latest earnings make it easier to track how these deals contribute against a backdrop of softer Orkla Food Ingredients volumes and weaker profitability in Orkla Health.
Those acquisitions are intended to broaden Orkla Snacks and sauces, while factory closures and other efficiency measures aim to lower overheads by 2027. With nine month earnings per share at NOK 5.22, well below the prior year, your focus as a shareholder is likely to be on whether integration and cost measures progress quickly enough to offset operational pressure in the more challenged segments.
On these Simply Wall St assumptions, Orkla's narrative projects NOK 75.3b revenue and NOK 6.8b earnings by 2029, anchored on 2.1% yearly revenue growth and an earnings increase of about NOK 0.3b from NOK 6.5b today.
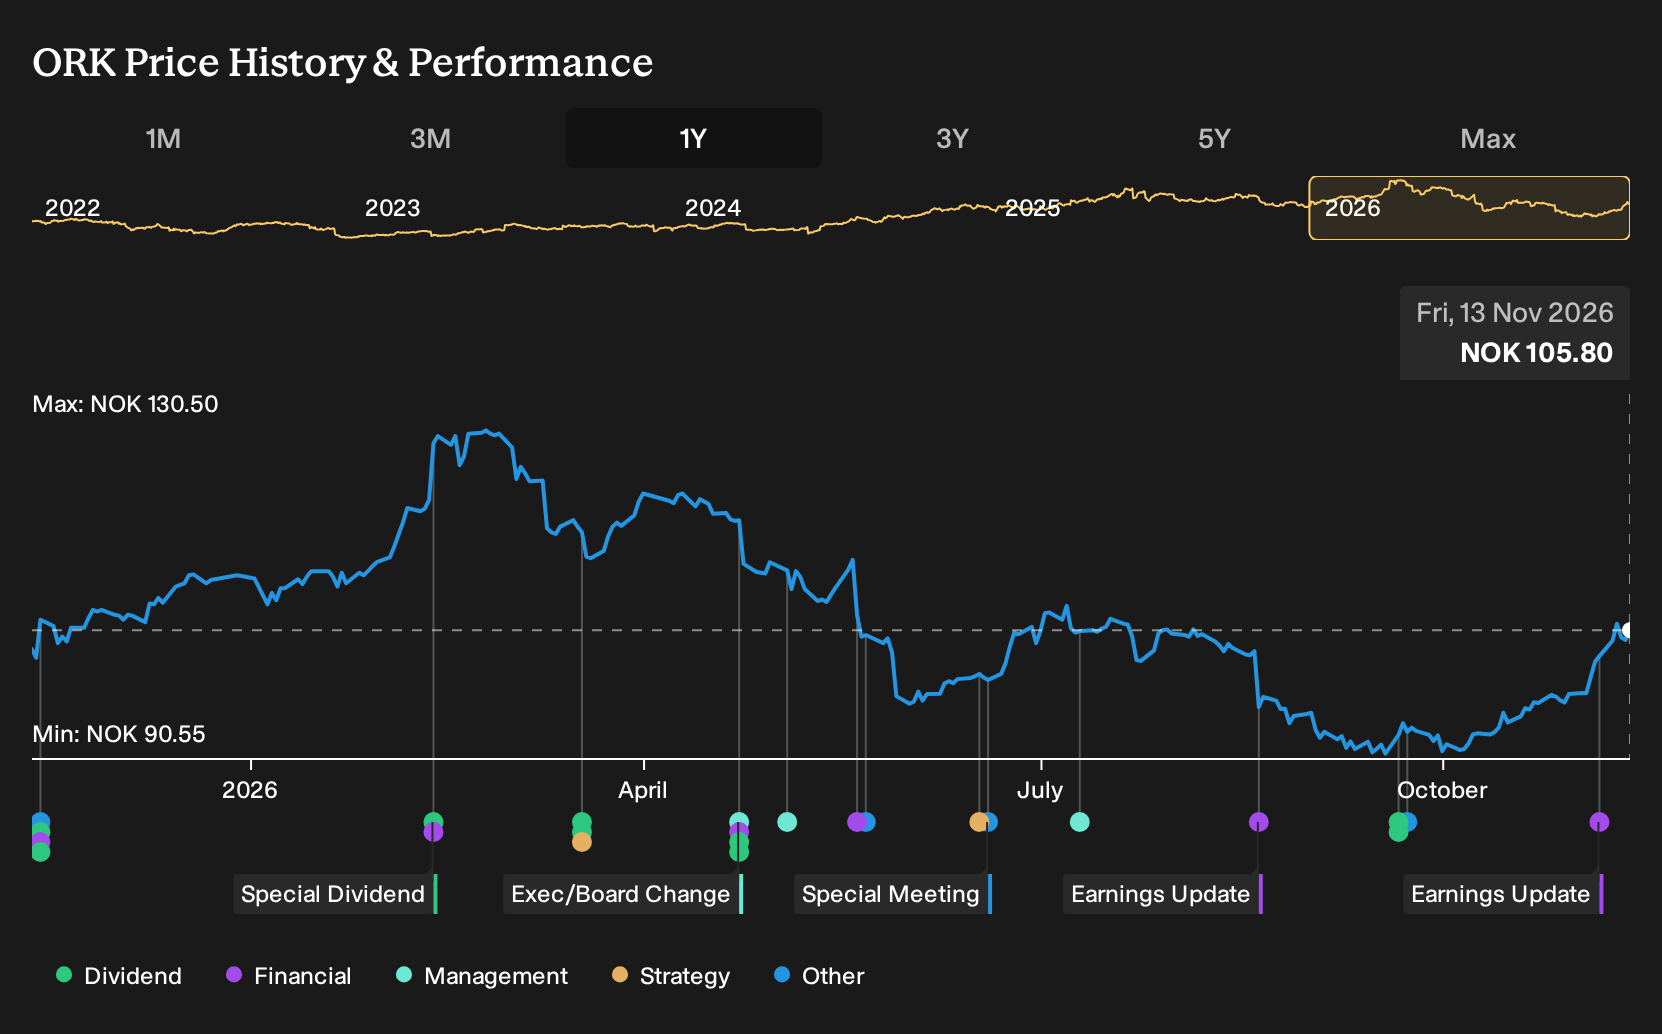
Uncover why Orkla's fair value indicates a valuation gap that appears to be broadly consistent with its current price.
Exploring Other Perspectives
One alternate view puts factory closures and cost cuts at Orkla front and centre as a potential catalyst rather than just a headache. The most optimistic analysts were pencilling in NOK 82.0b of revenue and NOK 7.7b of earnings by 2029 before this earnings release. Use this quarter as a chance to test whether you agree and to explore how your own expectations differ from theirs.
Explore 2 other Orkla fair value estimates, including one that suggests there could be as much as 88% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Orkla research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Orkla. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Orkla's overall financial health at a glance.
Looking for more investment ideas beyond Orkla?
If Orkla's latest update has you rethinking where earnings resilience really comes from, it can help to line it up against other companies with different strengths. The Simply Wall St Screener lets you filter for traits that matter to you, whether that is income stability, balance sheet strength or overlooked quality.
- If you want income to do more of the heavy lifting, scan for companies built around reliable payouts and strong coverage using our 218 dividend fortresses.
- If balance sheet durability is your first test for any investment, narrow the field to businesses with low leverage and solid fundamentals through the list of solid balance sheet and fundamentals (200 results).
- If you prefer to hunt for underappreciated quality, focus on stocks that pair healthier cash flows with valuations that still look restrained via the 566 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com