


- Northern Oil and Gas reported third quarter 2026 revenue of US$345.91 million and a net loss of US$111.81 million, while full year production guidance and a quarterly dividend of US$0.45 per share were both reaffirmed or raised.
- The mix of declining revenue and continued losses, alongside higher projected volumes, highlights a business leaning on operational throughput even as reported earnings remain under pressure.
- This article will examine how Northern Oil and Gas's raised 2026 production guidance influences the broader investment narrative around volume-led execution.
Scan beyond Northern Oil and Gas and compare its volume-led story with a hand picked list of solid balance sheet and fundamentals (24 results) for context on different ways energy producers are managing risk and cash returns.
Northern Oil and Gas Investment Narrative Recap
To own Northern Oil and Gas, you need to be comfortable with a volume first story where higher production is a key lever while reported earnings remain under pressure. The analyst consensus narrative on Simply Wall St already hinges on execution in a non operated, multi basin model. The raised 2026 production guidance supports that operational angle but does not change the reality of current GAAP losses.
The near term swing factor is whether higher output and portfolio breadth translate into steadier cash generation without further erosion in costs or impairments. Ongoing net losses, rising expenses as a share of revenue, and interest costs on higher coupon debt remain the biggest operational and financial risk.
The production guidance update is the most relevant development for that thesis. Management now expects 147,000 to 150,000 Boe per day for 2026, with a slightly higher midpoint for oil volumes as well. That speaks directly to the volume led execution story that underpins the multi basin acquisition and ground game approach.
For catalysts, higher projected production and a steady outlook for wells turned in line provide a clearer view on potential throughput against those fixed interest obligations and dividend commitments. The unchanged US$0.45 per share quarterly dividend signals confidence in the current cash return framework, although the identified risks around dividend coverage and interest expense mean you still need to watch how that interacts with ongoing reported losses.
Northern Oil and Gas' narrative projects US$2.5b revenue and US$498.5 million earnings by 2029. This aligns with analyst assumptions of 8.2% yearly revenue growth and an earnings change of roughly US$985 million from the current earnings of a US$486.0 million loss.
Uncover why Northern Oil and Gas' fair value indicates a 21% potential upside to its current price, which could narrow quickly.
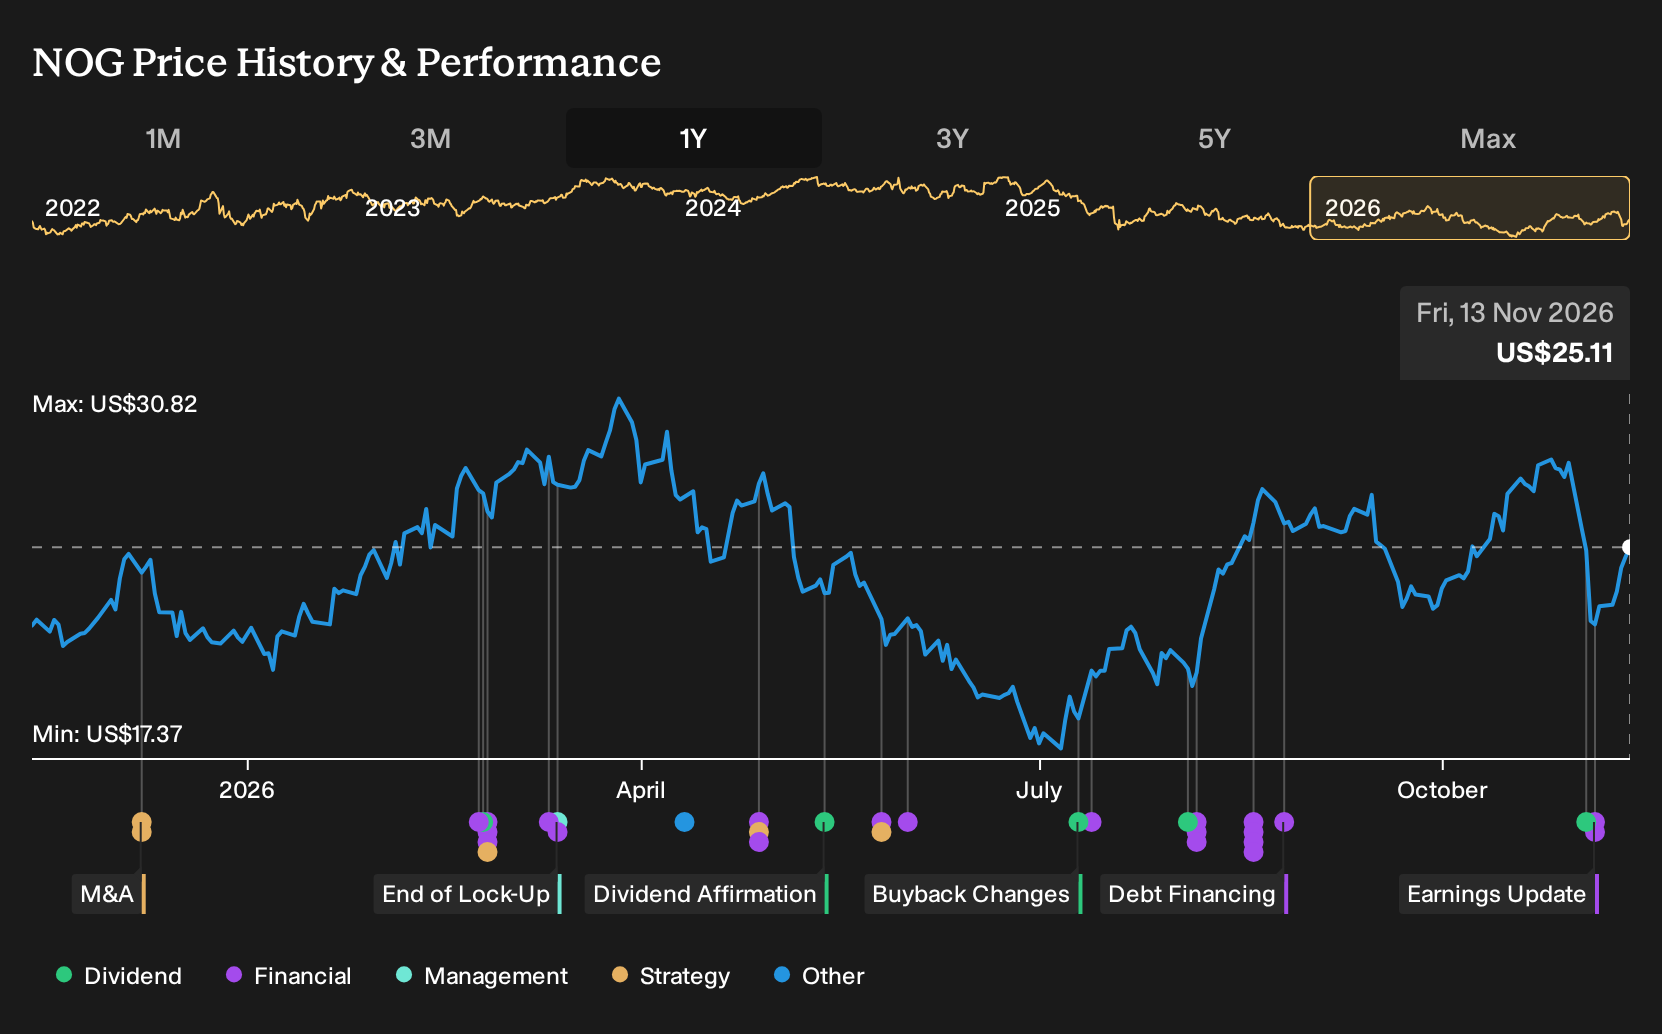
Exploring Other Perspectives
For a very different angle on Northern Oil and Gas, look at the bullish catalyst around higher margin potential. The most optimistic analysts were pencilling in about US$2.8b of 2029 revenue and US$780.3 million of earnings before this report. You can treat today’s higher production guidance and fresh loss figures as a test of that optimism and explore how your own expectations line up.
Explore 4 other Northern Oil and Gas fair value estimates, including one that suggests as much as 162% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Northern Oil and Gas research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Northern Oil and Gas. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Oil and Gas' overall financial health at a glance.
Looking for more investment ideas beyond Northern Oil and Gas?
If Northern Oil and Gas has sharpened your focus on volume, balance sheets, and cash returns, it can help to line that thinking up against a broader watchlist built with the Simply Wall St Screener.
- If you care most about valuation and quality together, start with a 32 high quality undervalued stocks that already combine solid finances with pricing that may appeal to value focused investors.
- If capital preservation ranks high for you, compare Northern Oil and Gas with a 31 resilient stocks with low risk scores that score well on balance sheet strength and business risk.
- If you prefer to fish where fewer investors are looking, scan through a 20 high quality undiscovered gems that pair healthier fundamentals with lower current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com