


Charter Communications has staged a sharp short-term rebound, yet its longer track record is deeply negative. This raises a straightforward question for you as an investor: Is the current share price really aligned with what the company is earning today and what those earnings may support over time?
- The stock has fallen 79.7% over the past 5 years, putting the focus squarely on whether the earnings profile now justifies even the lower valuation implied by that decline.
- A recent net loss tied to a large impairment charge and ongoing customer churn, alongside heavy capital spending plans and debt tenders, can reshape expectations for future profitability and the timing of cash flows that underpin any earnings-based valuation.
- There is a second opinion on Charter Communications worth weighing. See what analysts think Charter Communications's shares could be worth.
The issue now is whether Charter Communications' current market price is adequately supported by its earnings when set against the Fair Ratio benchmark.
If you are weighing Charter Communications against similar opportunities tied to earnings power and capital intensity, it helps to see how other businesses stack up in our 34 high quality undervalued stocks
Is Charter Communications a Bargain on Earnings?
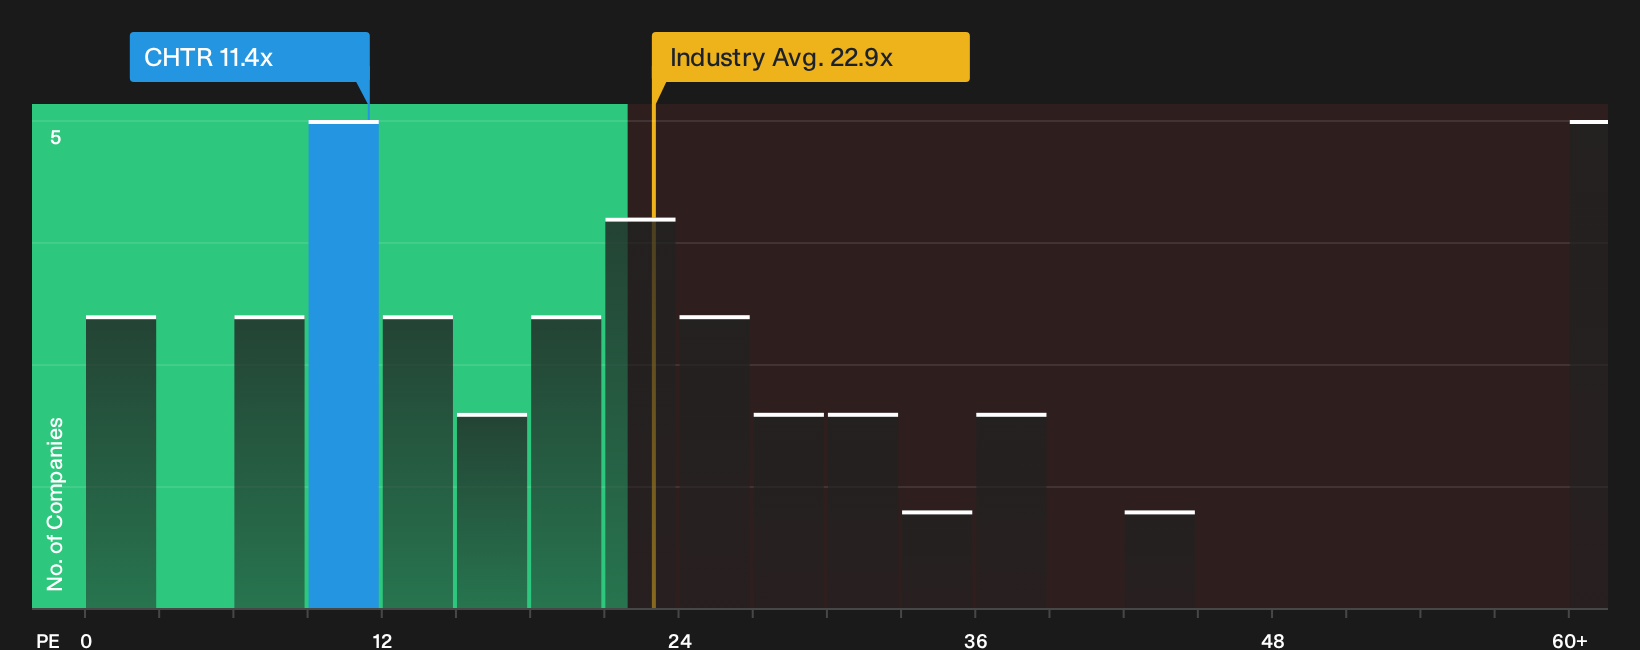
The P/E ratio fits Charter Communications because earnings are still the main yardstick investors use for mature telecom and media hybrids. On that basis, the stock trades on a P/E of about 11.4x, which is close to both the direct peer average near 11.2x and well below the broader media sector on roughly 22.9x. That mix of a peer-level earnings multiple and a discount to the wider industry indicates that the market is pricing Charter more like a utility-style cash generator rather than a high-growth content or advertising play.
Fair Ratio analysis, which adjusts the P/E you might expect for Charter Communications given its specific growth profile, margins, capital needs and risk, points to a higher earnings multiple than the market is currently assigning. Because of that, the stock screens as undervalued on this measure despite the recent Q3 2026 loss and franchise impairment charge, which likely weigh on sentiment after the Cox acquisition and heavy capex guidance. For you as an investor, the question is whether those headwinds justify a lower P/E than the Fair Ratio suggests. Explore the numbers behind Charter Communications's P/E valuation.
The Charter Communications Narrative: What Would Justify Today's Price?
Narratives for Charter Communications pick up where the valuation puzzle leaves off by spelling out which assumptions about growth, margins and earnings would need to play out for the shares to look meaningfully cheaper or more expensive than they do today on Simply Wall St's Community page. Each scenario treats fair value as a clear thesis about Charter Communications' business that you can track over time, rather than a one-off number on a chart.
Views on Charter Communications could hardly be more split, with one side arguing the business is deeply mispriced and the other warning risks already match the current tag.
Bull case: 53% undervalued
According to david_6nroa, an investor in the Simply Wall St Community, the optimistic angle leans heavily on cash generation and the capital plan.
"CHTR is nearing the end of a large multi-year network upgrade, Capex, which has been coming in at roughly 11.5B for three years, will decline to 9.5B in 2027 and 7.5B in 2028 generating a 4B increase in annual FCF..."
Discover why this Narrative puts Charter Communications at 53% undervalued.
Bear case: 104% overvalued
The bearish analyst Narrative on Simply Wall St leans on broadband pressure and execution risk around Cox and lower capital spending.
"Although Charter Communications is promoting converged connectivity with mobile and video bundles that reduce churn, the company’s own expectation for around a 1% decline in standalone 2026 EBITDA shows that broadband subscriber and ARPU pressure plus rising controllable costs could prevent the bundle strategy from translating into healthier earnings or margin trends..."
Explore why this Narrative puts Charter Communications at 104% overvalued.
One more Charter Communications check before you move on
Price comparisons and community Narratives tell you how the market feels today, but professional models that map out where this business could be in a few years offer a different lens on what you are really paying for. Explore where analysts expect Charter Communications to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com