


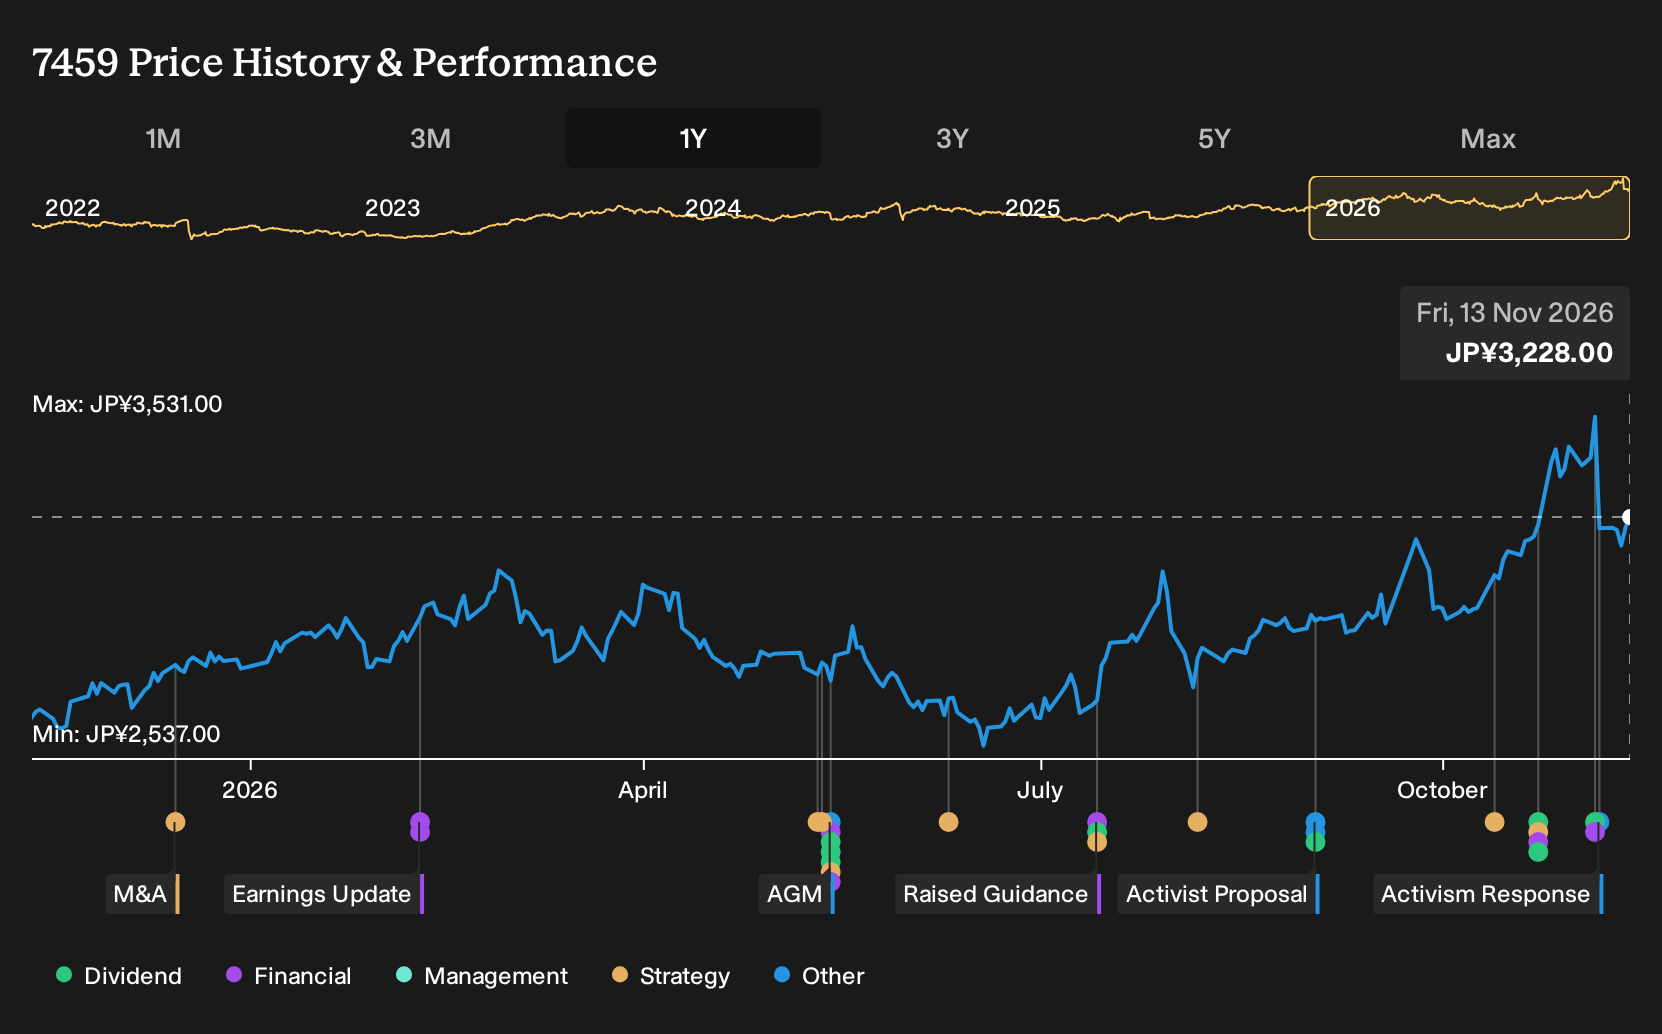
- MediPal Holdings reported half year sales of JPY 1,969,620 million and net income of JPY 23,027 million. The company raised its interim dividend to JPY 44 per share and earlier this month called an extraordinary shareholders meeting after a major investor sought a director dismissal, a special dividend, and a large share buyback that the board opposes.
- The clash between Silchester’s capital return proposals and MediPal Holdings' board, which cites growth funding and financial soundness, highlights a live debate over how much cash should stay inside the business versus being handed back to investors.
- This article examines how MediPal Holdings' investment narrative is shaped by this shareholder push for a special dividend and buyback.
What Is MediPal Holdings' Investment Narrative?
The big picture for a MediPal Holdings shareholder is simple. You need to believe this healthcare distributor can keep turning a low margin, high volume model into steady earnings, while using its balance sheet in a disciplined way. The latest half year numbers point to incremental progress in sales and profit, and the higher interim dividend suggests confidence in cash generation. Investor activism now adds a new layer. The extraordinary meeting called for December puts capital allocation and leadership squarely on the table, which keeps the focus on how every yen of cash is used.
In the short term, the main catalysts sit in execution on pharmaceutical distribution, pricing with suppliers and clients, and the capital intensity of its logistics network. Earnings quality is described as high, return on equity is low, and revenue growth is expected to be slower than the wider Japan market, so how management reinvests versus returns capital really matters. The Silchester proposals for a special dividend and large buyback directly challenge that balance. If the board holds its line, the story remains about gradual growth and stable dividends. If activists gain more influence, the near term narrative shifts toward cash returns and balance sheet shape.
Yet there is a less obvious risk sitting underneath that capital return debate that you will want to think about before...
There's only one way to know the right time to buy, sell or hold MediPal Holdings. Head to Simply Wall St's company report for the latest analysis of MediPal Holdings's Fair Value.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MediPal Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for MediPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MediPal Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond MediPal Holdings?
If this MediPal Holdings story has you thinking about balance sheets, dividends, and how much cash companies should keep versus return, it can help to line it up against other opportunities using the Simply Wall St Screener.
- For investors who want income to feel sturdier through different market conditions, check out companies we flag as potential income anchors through the 29 dividend fortresses.
- If capital protection and a steadier ride matter most to you, start with businesses that our models classify as more resilient by heading to the 19 resilient stocks with low risk scores.
- When you want quality fundamentals without the usual crowding effect, focus on underfollowed opportunities surfaced through the 72 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com