


- Colowide Ltd reported half-year earnings for the period ended September 30, 2026, with sales of ¥173,623 million, net income of ¥888 million, and basic and diluted EPS from continuing operations of ¥2.79, all compared with the prior year period.
- Higher sales alongside weaker net income and lower earnings per share highlight rising cost or mix pressures that could be reshaping Colowide Ltd’s profitability profile.
- The focus will now move to how Colowide Ltd's weaker earnings per share might reshape the broader investment narrative around the business.
What Is ColowideLtd's Investment Narrative?
To own ColowideLtd, you need to buy into a story built on scale, multi brand reach and the ability to turn heavy restaurant and food operations into reliable cash generation. The latest half year print, with ¥173,623 million in sales but softer net income and earnings per share, flags that execution on costs and store level profitability matters more than ever. With profit margins at 0.4% compared with 0.6% last year and earnings affected by large one off items, the near term question is whether everyday operations can offset that drag.
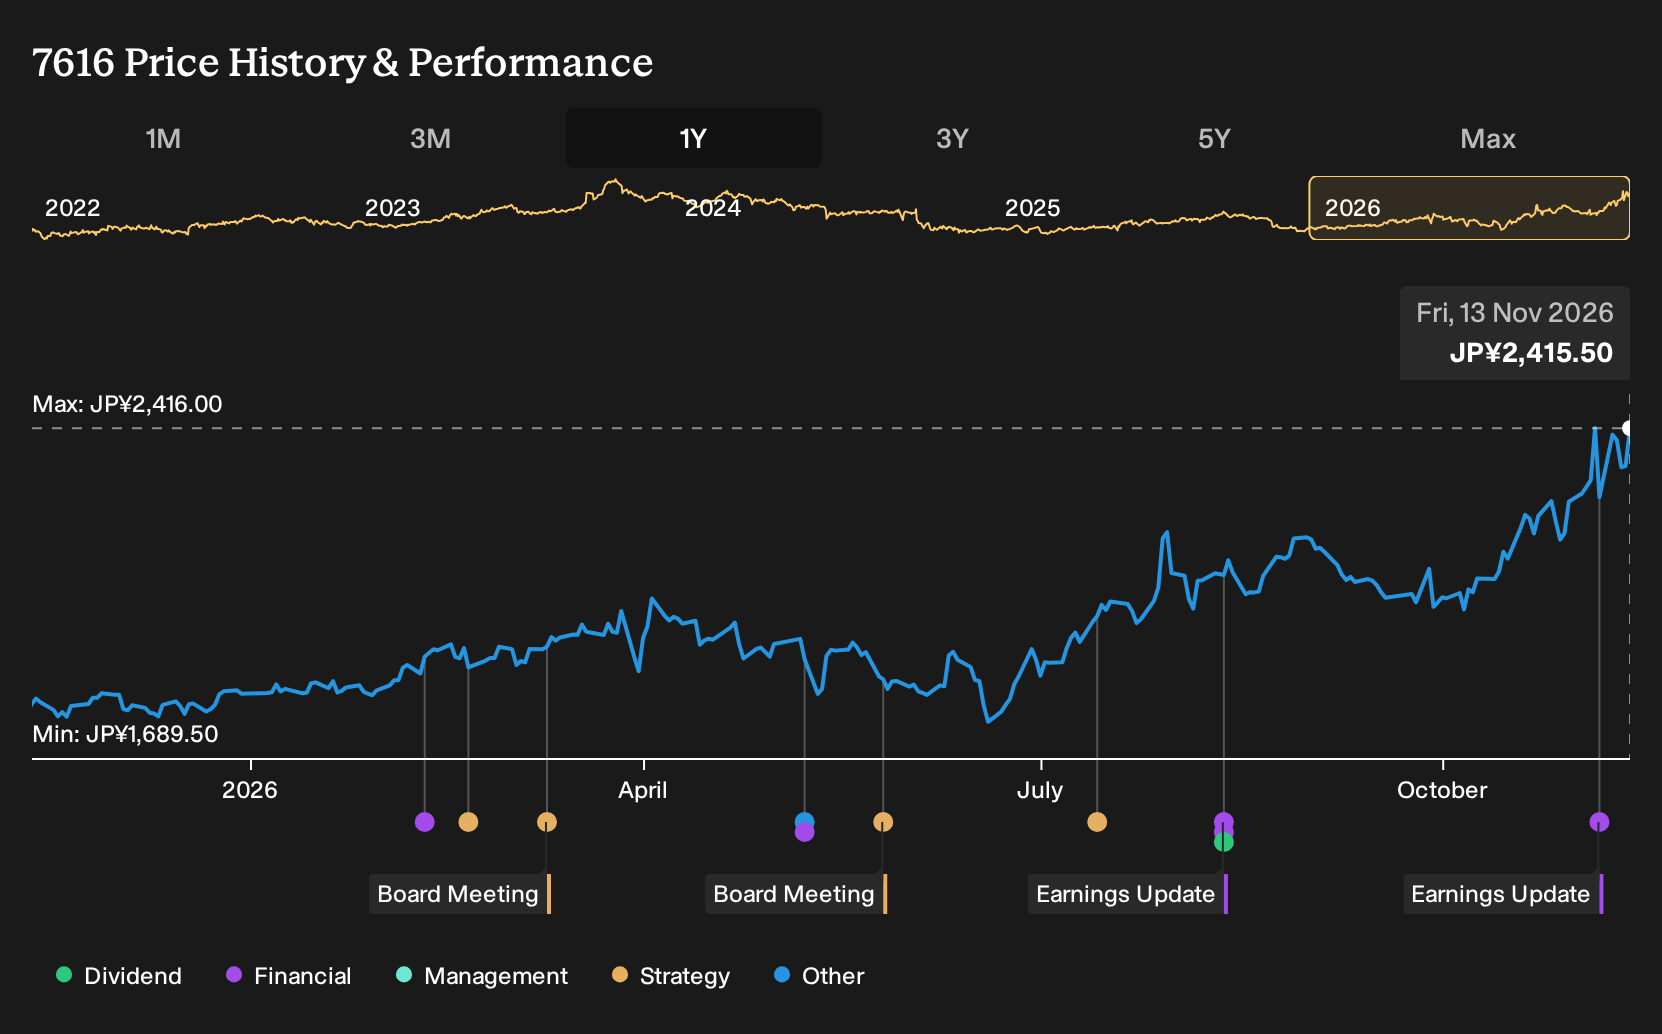
In the short term, the key swing factors look very practical. Pricing power across formats such as Gyu Kaku, Shabu Shabu On Yasai and OOTOYA, the efficiency of centralised procurement and logistics, and how aggressively ColowideLtd wants to reinvest in its footprint all feed directly into returns. A high debt load and low 0.9% return on equity leave less room for mistakes, so the latest earnings miss on the bottom line sits uncomfortably beside a share price that has risen 39.3% over the past year.
Even so, there is a less obvious pressure point in the ColowideLtd story that could matter far more if ...
There's only one way to know the right time to buy, sell or hold ColowideLtd. Head to Simply Wall St's company report for the latest analysis of ColowideLtd's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ColowideLtd research is our analysis highlighting 3 important warning signs that could impact your investment decision.
- See our latest analysis for ColowideLtd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ColowideLtd's overall financial health at a glance.
Looking For More Investment Ideas Beyond ColowideLtd?
If ColowideLtd's latest figures have sharpened your focus on quality and risk, it can help to line it up against a wider bench of businesses with different profiles and income characteristics.
- For readers who care most about balance sheet strength and durability, start with a list of solid balance sheet and fundamentals (24 results) that can help you stress test your standards against a wider universe.
- If value is your priority and you want to see where fundamentals and pricing may be out of sync, scan through 18 high quality undervalued stocks to find candidates worth a closer look.
- For those who like their returns paid in cash, use 29 dividend fortresses to spot income ideas that match your yield and stability preferences.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com