


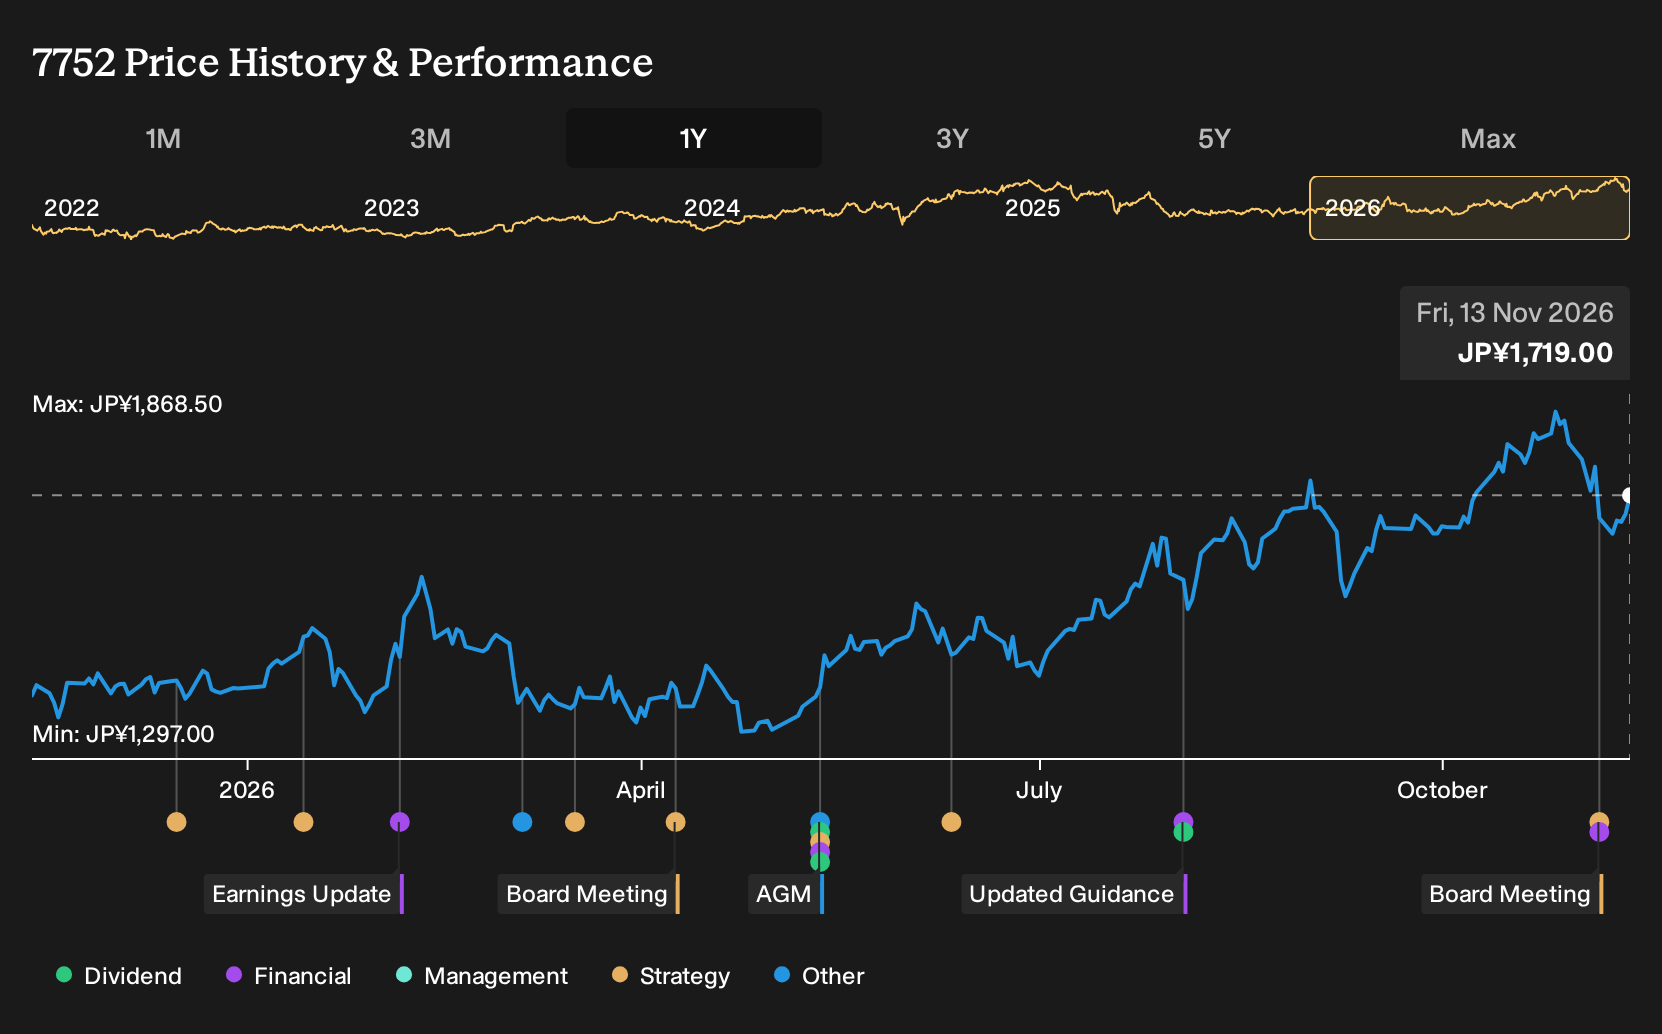
- Ricoh Company reported half-year results for the period ended September 30, 2026, with sales of ¥1,294,427 million and net income of ¥55,755 million, alongside basic earnings per share from continuing operations of ¥98.77.
- The board also approved the transfer of Ricoh's Thermal business into a newly created wholly owned subsidiary through a simplified absorption type split, indicating a clearer separation of that segment's operations within the wider group structure.
- The focus now turns to how Ricoh Company's investment narrative could evolve as the Thermal business is carved into a standalone subsidiary.
What Is Ricoh Company's Investment Narrative?
To own Ricoh Company, you need to be comfortable with a mature, capital intensive hardware and services group that is working to tidy up its portfolio rather than chase rapid expansion. The Thermal business transfer into a wholly owned subsidiary fits that pattern. It tidies reporting lines and could make returns on that unit easier to judge, but it does not suddenly change demand for printers, document services or industrial components.
The half year numbers, with ¥1,294,427 million in sales and ¥55,755 million in net income, underline a business that still relies on consistent execution and cost control more than aggressive top line growth. Forecasts pointing to modest revenue progress and declining earnings keep pressure on management to sustain margins and cash generation. The simplified split does not remove the bigger questions around capital intensity, slower expected growth and an unstable dividend record. It simply makes them a little clearer to see.
That said, there is one structural issue around Ricoh Company that tends to get less attention than it should...
There's only one way to know the right time to buy, sell or hold Ricoh Company. Head to Simply Wall St's company report for the latest analysis of Ricoh Company's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ricoh Company research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Ricoh Company. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ricoh Company's overall financial health at a glance.
Looking for more investment ideas beyond Ricoh Company?
Once you understand where Ricoh Company fits in your portfolio, it can help to scan a wider field of opportunities so you are not relying on a single story or sector.
- If you care most about quality at a sensible entry point, review a curated 20 high quality undervalued stocks that filters for companies combining stronger fundamentals with more reasonable pricing.
- If stability matters more than excitement, check out a 18 resilient stocks with low risk scores that highlights businesses with healthier balance sheets and fewer red flags in their risk profiles.
- If you want firms that can shoulder tougher conditions, focus on a list of solid balance sheet and fundamentals (24 results) so you can see which stocks have the financial strength to keep options open.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com