


[Editor-in-chief Guan Shi]
The Huang Renxun incident caused a huge shock to the global capital market. A series of negative shocks led to a sharp adjustment in the Hang Seng Index last week.
Flights across the US have been suspended, and Trump has listened to the briefing; this is the second time since the “9/11” attacks in 2001 that all flights have been banned across the US.
Technology stocks will face another test this week. The market focuses on Hwang In-hoon's first report card after his resignation and interim CEO Colette Kress's latest statement on future company strategy; there is also the IPO of tech giant Anthropic, which is priced on the 18th and listed on the NASDAQ on the 19th. There is usually an impact in the early stages, and the pressure may ease after landing.
In a situation where external supply is being tightened, the country may speed up the verification of domestic substitution, bringing opportunities to the domestic-related computing power industry chain.
Domestically, Chairman Wu Qing of the Securities Regulatory Commission: Deepen research on long-term mechanisms for market stability and effectively prevent abnormal market fluctuations. Whether the market can stabilize is mainly to observe whether there is relevant incremental market entry funding.
In terms of the incident, the APEC Business Leaders Summit will be held at the Shenzhen Qianhai International Convention Center from November 17 to 18. During the APEC meeting, the Qianhai Real Estate Intelligent Exhibition Center will showcase various robots. Observe whether it can ferment.
A weak market generally chooses the direction of domestic demand. Trump: Promoting the “Film, Television, and Entertainment Industry Revitalization Act”; Douyin Group's Short Drama Copyright Center is open to partners with the ability to produce interactive content, skits, comics, or games to cooperate with interactive movies and games.
[This week's gold stocks]
Shangmei Co., Ltd. (02145)
On January 12, Star Map data was released. The total e-commerce product transactions of the entire network during the 2026 Double Eleven Shopping Festival statistics cycle reached 1776.40 billion yuan, an increase of 4.8% over the previous year, in line with institutional expectations.
A number of brands under Shangmei Co., Ltd. handed over impressive report cards. The main brand, Han Shuqi, steadily rebounded and built a strong basic market. Second-tier brands continued their rapid growth trend, and new brands were growing at the same time as high-potential brands.
The seven major brands Han Shu, Newpage Yipage, An Minyou, Ji Fang, Red Elephant, Cui Yutao, and Kebangda simultaneously released big promotion reports, showing that the total sales volume of the main brand Han Shu's multi-channel sales increased by 42.4% month-on-month, and sales of the two major nursing and men series both exceeded 100 million yuan; Newpage sold 1.23 million popular products; and An Minyou's sales reached 120 million yuan, an increase of 92% over the previous year. The new brand, Cui Yutao, which was launched in January, surpassed 32 million yuan in sales in its first battle; in addition, when several new effective products were launched, it reached the top of the segmented track list.
[Industry Watch]
The National Health Insurance Administration held a conference on high-quality development of innovative drugs in Suzhou. At the conference, the results of the 2026 medical insurance catalogue adjustment were announced.
In terms of entry, 107 new types were added, including 51 Class 1 innovative drugs, a record high. 368 varieties were reviewed by experts, 127 passed, and the review pass rate was 34.5%. This is the main screening process.
In terms of price, out of 107 new varieties, there are only 22 public payment standards; the median decline of 50.9% of the newly included varieties was 50.9%.
The payment limits for 60 types have changed. Of these, 92% have been relaxed, and the original rigid payment threshold has been changed to the manual threshold.
Volume: For the first time, the procurement status of Guozhang Pharmaceutical was systematically disclosed. In 2025, it was 172.5 billion yuan, +48% over the same period, which is 9.6 times the growth rate of drug procurement across all platforms during the same period.
Some points worth paying special attention to: (1) CAR-T is included in basic medical insurance for the first time: Pharmaceutical Junuo's Rickie Orense injection became the first CAR-T product to enter the national health insurance list. The original price was over one million yuan, and patients' out-of-pocket expenses are expected to drop to less than 100,000 yuan after reimbursement. (2) Domestic innovative drugs have outstanding performance: Cinda Biotech's Mashidu Peptide (the first domestically produced dual-target weight-loss and hypoglycemic drug), Bailey Tianheng Yizekang (included in the first year of marketing), and Fuhong Hanlin Hans have all been included in the products. (3) Medication for assisted reproduction was introduced for the first time.
Recommended key enterprises to focus on: Yao Ming Junuo, Baili Tianheng, Cinda Biotech, Colun Botai Biology, Fuhong Hanlin, and Rongchang Biotech.
[Data View]
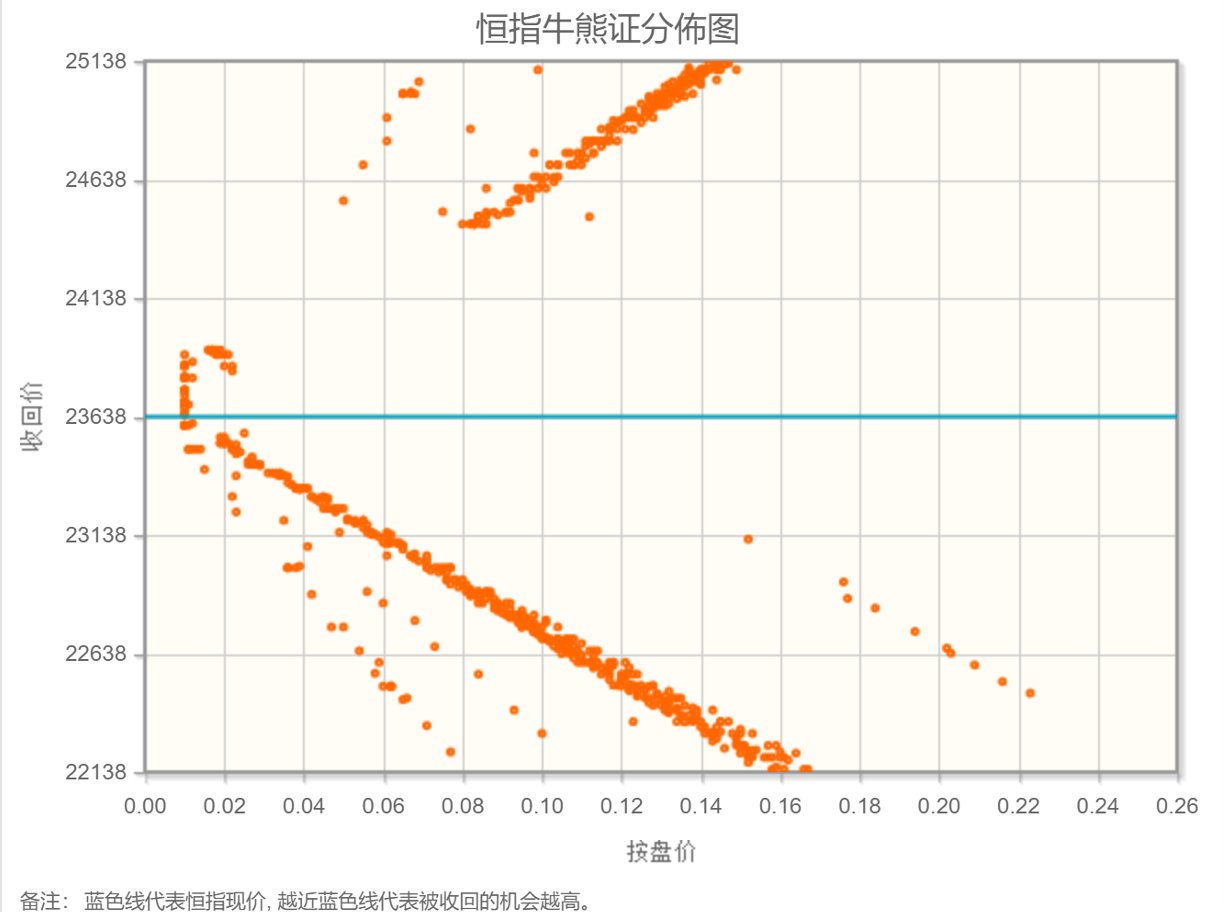
According to data released by the Hong Kong Stock Exchange, the total number of outstanding contracts in the Hang Seng Futures Index (November) was 121,050, and the net number of outstanding positions was 36,524. Hang Seng Futures refers to the settlement date of November 27, 2026.
The Hang Seng Index is at 23,638 points. Bears generally deviate from the central axis, bullish stocks are close to the central axis, and Hong Kong stocks are motivated to go short. US Treasury bonds experienced a sharp sell-off, and the ten-year yield rushed to 5.14%. Market expectations that the Federal Reserve will continue to raise interest rates have heated up rapidly, and discussions have even begun on the possibility of raising interest rates by 50 basis points. The Hang Seng Index is bearish this week.
[Editor's Testimonial]
As stated in the previous issue, “the rain is about to fill the house,” at the valuation level, as of November 13, the Hang Seng Technology Index NTM PE was 17.2 times, continuing to decline 18.6 times the previous week. There are good signals at the capital level. The cumulative net inflow of southbound capital in January was -23.8 billion yuan, and the outflow trend has slowed; in terms of short selling, Hong Kong stock short sales accounted for 17.94% of total market turnover last week, which also declined from month to month.
The market is still structured, and defensive capital seeking stability may prefer the energy chain (coal/electricity/energy storage) and financial dividends (banking/insurance); offensive capital may also seek opportunities to play domestic alternatives (chips/computing power/robotics/space photovoltaics, etc.), and there are still quite a few short-term opportunities.