


- M&T Bank has expanded its M&T Visa Credit Card with Rewards, offering 3 points per US$1 on eligible grocery purchases up to US$15,000 a year, 2 points on eligible gas purchases, and 1 point on other eligible spend, with flexible redemption options and no annual fee.
- The richer grocery and gas rewards structure, alongside digital wallet compatibility and fraud protections, is pushing M&T Bank further toward deeper everyday payment relationships that can influence long term fee income trends.
- We will now look at how M&T Bank's richer grocery rewards structure interacts with its fee growth focused investment narrative overall.
Compare M&T Bank's card push with other issuers by reviewing list of solid balance sheet and fundamentals (24 results), which may also be emphasizing fee driven payment activity as part of their future growth narratives.
M&T Bank Investment Narrative Recap
To own M&T Bank, you need to be comfortable with a regional lender that leans on fee income, capital discipline and ongoing tech spending rather than rapid top line expansion. The analyst consensus Narrative on Simply Wall St sees the core debate around whether that US$1.2b a year tech and process spend can support efficiency and fee growth without eroding profitability.
In the short term, the key swing factor is still deposit mix and funding cost, where any decline in noninterest bearing balances could pressure net interest margin. Credit card rewards richer than before matter more at the margin. They support the fee income story, but do not change the main risk around expenses and regulation.
The refreshed M&T Visa Credit Card with Rewards fits cleanly into the fee growth angle that analysts are watching. Higher earning rates on groceries and gas, plus flexible redemption, give M&T Bank another way to deepen everyday payment usage, which ties back to its focus on top tier deposit share and cross selling in core markets.
In terms of catalysts, the card program connects directly to management’s higher 2026 fee guidance of US$2.8b to US$2.85b and its push to rely less on net interest margin. Execution risk is real. Richer rewards add cost and can pressure economics if spend mix skews heavily to bonus categories or if deposit and regulatory pressures intensify at the same time.
M&T Bank’s current analyst narrative points to revenue of US$11.0b and earnings of US$3.2b by 2029, built on a forecast 5.1% yearly revenue growth rate and an increase in earnings from US$2.9b today to that US$3.2b level, which is a move of about US$0.3b.
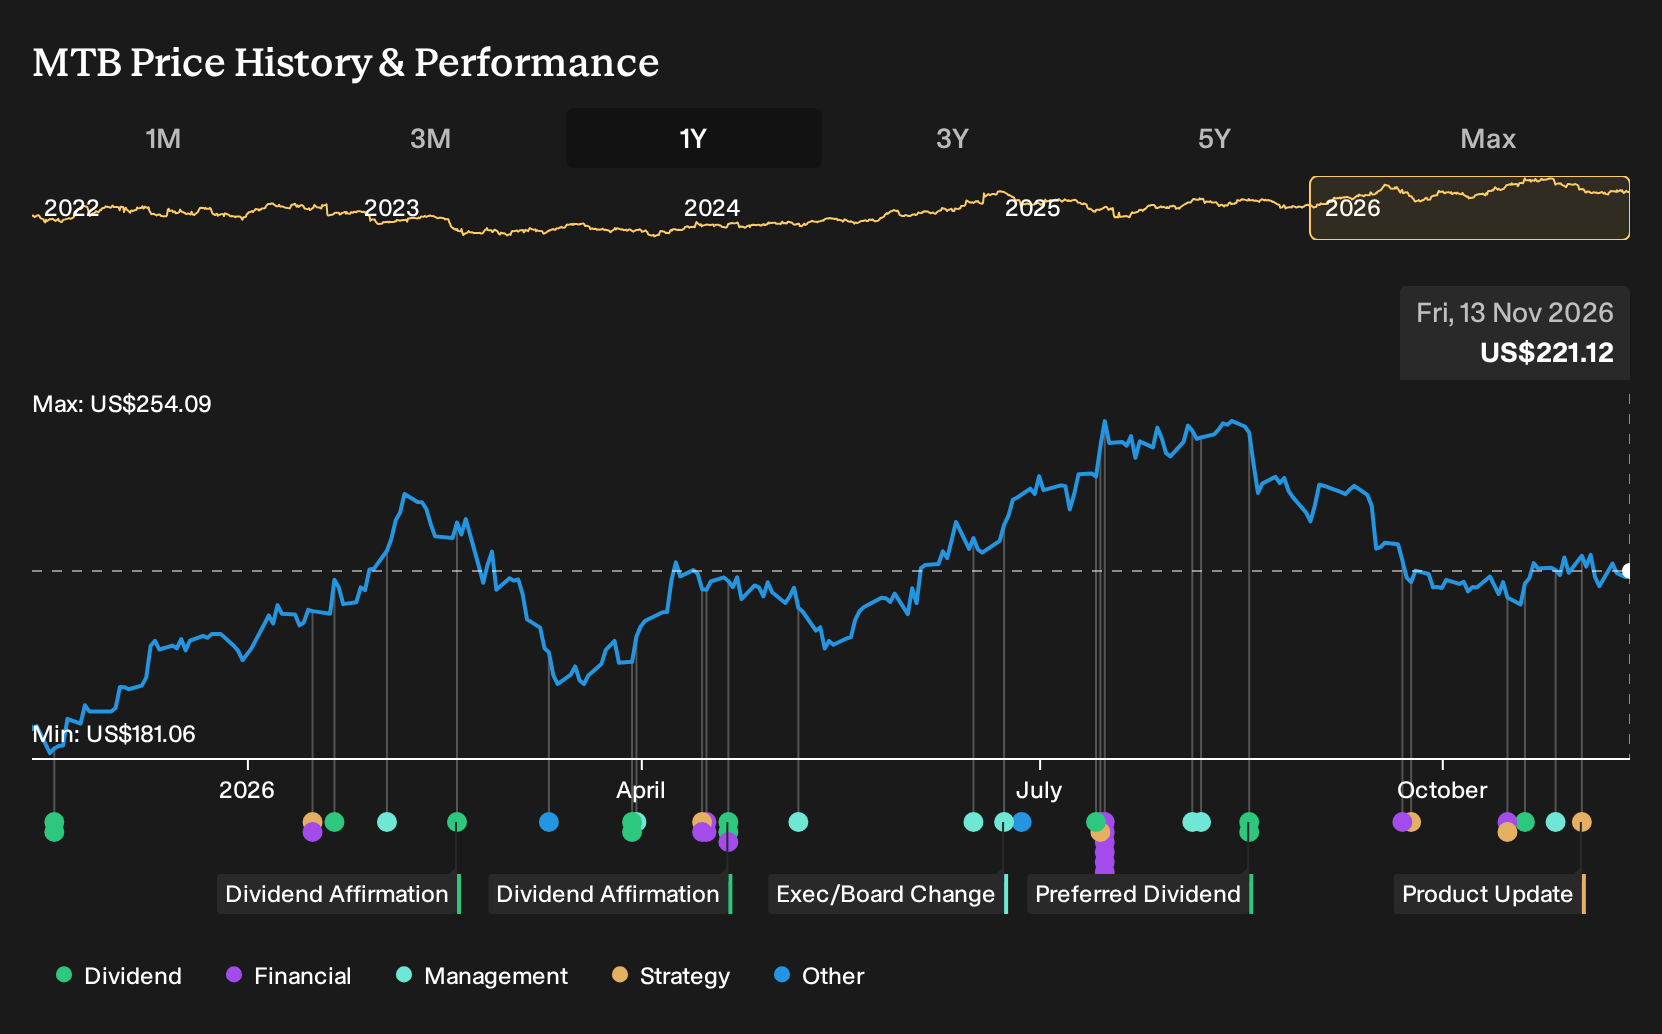
Uncover how M&T Bank's fair value indicates an 11% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span a wide band, from about US$246 per share up to roughly US$414, which shows how far opinions on M&T Bank can stretch. Before you lean on any single estimate, weigh that dispersion against risks around deposits, expenses and regulation, and then explore several contrasting Community viewpoints.
Explore another M&T Bank fair value estimate, including one that suggests potential upside of up to 87% from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your M&T Bank research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for M&T Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate M&T Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond M&T Bank?
Once you have a view on M&T Bank, it can help to line that up against other companies with different risk and income profiles, using the Simply Wall St Screener to see how alternatives compare on quality, balance sheet strength and income potential.
- If you want potential income plus resilience, check out a curated set of income plays built around 6 dividend fortresses that may suit a yield focused approach.
- For investors who care most about financial strength and staying power, start with a 29 resilient stocks with low risk scores that keeps the focus on resilience rather than excitement.
- If you are hunting for mispriced quality, weigh M&T Bank against a 19 high quality undiscovered gems that screens for strong fundamentals that are not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com