


Public Service Enterprise Group Incorporated (PEG) is a diversified energy company headquartered in Newark, New Jersey. Valued at $37.8 billion by market cap, the company provides transmission and distribution of electricity and natural gas, as well as supplies energy that integrates the operations of its merchant nuclear generating assets.
Shares of this regulated infrastructure company have underperformed the broader market over the past year. PEG has declined 7.9% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. Over the past six months, PEG stock has dropped 1.7%, compared to the SPX’s 1.6% rise.
Narrowing the focus, PEG has also lagged behind the State Street Utilities Select Sector SPDR ETF (XLU). The exchange-traded fund has dropped marginally over the past year and has declined 1.4% over the past six months.
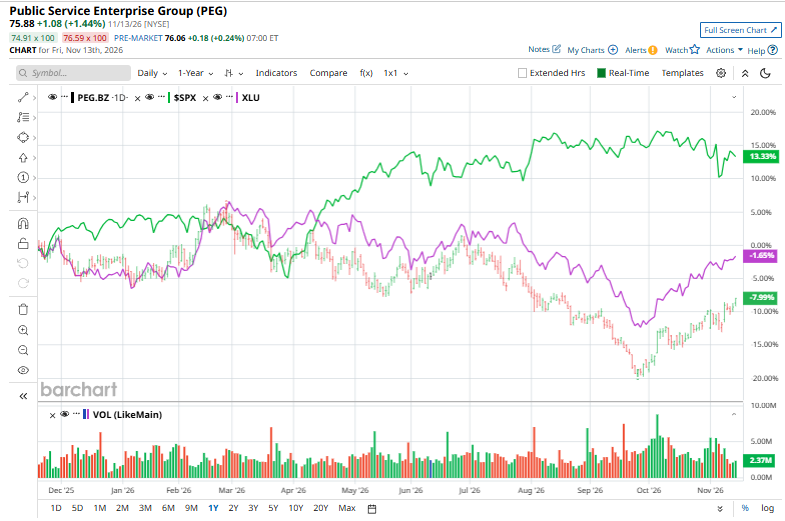
PEG released its FY2026 Q3 earnings on Nov. 2, and its shares dipped 2.1% in the next trading session. Despite the share price weakness, adjusted profitability improved, with non-GAAP operating earnings rising 1.8% year over year to $1.15 per share. However, operating revenues declined 6.4% to $3.02 billion, reflecting softer top-line performance. Meanwhile, PSEG invested approximately $1.1 billion in regulated infrastructure during the quarter and remained on track to meet its full-year capital spending target of $4.2 billion.
Looking ahead, management reaffirmed its FY2026 adjusted earnings guidance of $4.28–$4.40 per share and maintained its longer-term target of 6%–8% annual growth in non-GAAP operating earnings through 2030.
For the current fiscal year, ending in December, analysts expect PEG’s EPS to grow 7.7% to $4.36 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in three of the last four quarters, while missing on another quarter.
Among the 22 analysts covering PEG stock, the consensus is a “Moderate Buy.” That’s based on eight “Strong Buy” ratings, and 14 “Holds.”
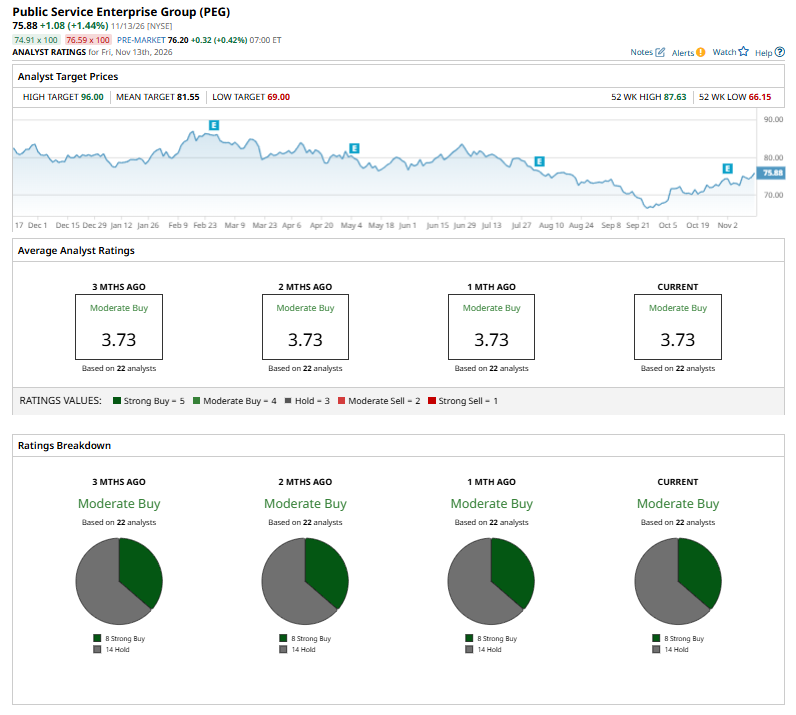
The configuration has been relatively stable over the past three months.
On October 22, HSBC initiated coverage on Public Service Enterprise Group with a “Hold” rating and a $72.50 price target. The firm expects the company's rate base to grow at a CAGR of 7% between 2026 and 2030, slowing to 5% through 2035. Earnings per share are projected to increase by 7% annually through 2030 before decelerating to 4% between 2030 and 2035, with both growth rates below industry peers. HSBC also highlighted PSEG's planned $24 billion–$28 billion investment program for 2026–2030, including $22.5 billion–$24.5 billion earmarked for regulated electricity and natural gas networks.
The mean price target of $81.55 represents a 7.5% premium to PEG’s current price levels. The Street-high price target of $96 suggests a notable upside potential of 26.5%.
On the date of publication, Kritika Sarmah did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.