


Neocloud provider CoreWeave (CRWV) reported better-than-expected third-quarter results and raised its outlook last week. That boosted the stocks of other neocloud providers, as the market saw huge artificial intelligence (AI) demand in the company's quarterly results.
Nebius Group (NBIS) saw shares rise 15% on Nov. 11. However, this tailwind was wiped out when NBIS stock dropped almost 17% the next day after reporting its own results on Nov. 12, posting a weaker outlook. Nebius shares have been in the red for every trading session since then. Let's take a closer look.
About Nebius Stock
Nebius is an AI cloud company headquartered in Amsterdam, the Netherlands. The company provides powerful computing systems, mainly GPUs, that businesses use to build and run AI. The company helps customers train AI models, process data, and deploy AI applications, operating data centers and technology teams in several countries and offering cloud services, software, and support. Nebius currently has a market capitalization of $29.3 billion.
NBIS stock has climbed 31% over the past 52 weeks on strong AI-driven demand, rapid revenue growth, expanding GPU capacity, financing support, and positive results from similar AI cloud companies. Over the past month, however, the stock has dropped 34%, while it is has also dropped 23% over the past five days. NBIS stock reached a 52-week high of $299.86 on June 22, 2026, but is down 64% from that level.
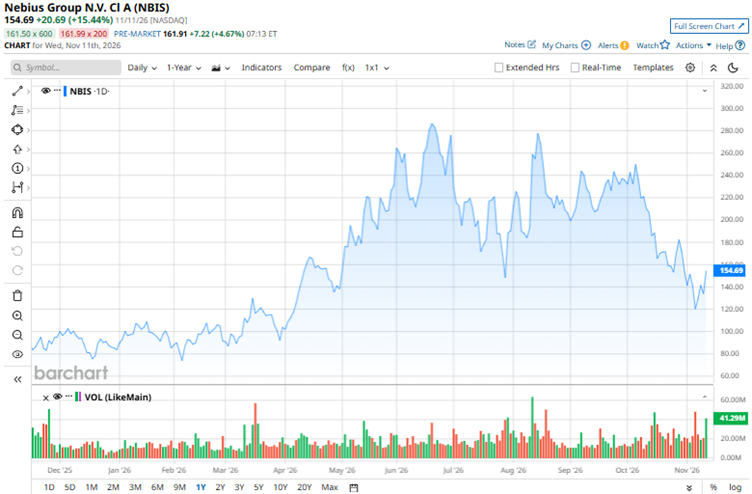
Nebius stock is trading at a stretched valuation compared to its peers. For example, its price-to-sales ratio (P/S) of 61.4 times is significantly higher than the industry average.
Nebius Reports Q3 Results: Rapid AI Cloud Growth Meets Investor Concerns Over Outlook
Wiping out the gains from the boost that CoreWeave’s earnings release provided, Nebius’ Q3 results led to a selloff in NBIS stock. That was despite the top line growing 571% year-over-year (YOY) to $981 million and surpassing analyst estimates of roughly $917 million.
This tailwind was driven by new capacity coming online, but it also included approximately $325 million of non-recurring revenue as part of the firm's asset-light model. Most of the company's top line was driven by cloud demand; AI cloud revenue grew 643% YOY of $973.8 million in the quarter. Meanwhile, adjusted EBITDA grew from a loss of $5.2 million a year ago to $465.8 million in Q3 2026.
Nebius’ demand is not in question, based on the blockbuster revenue growth. However, what put NBIS stock under pressure was its outlook. This is because some third-party capacity expected to come online this year has been pushed back to the first half of 2027. Nebius now expects 2026 revenue at the lower end of its $3 billion to $3.4 billion guidance range.
For fiscal 2027, revenue is expected to be $12 billion to $13 billion. However, this projected figure pales in comparison to the $40 billion to $45 billion in capital expenditures the company plans to take on. Nebius plans to cover 75% to 85% of its capex “through advanced prepayments and asset-backed financing investment-grade customers,” in addition to its balance sheet.
Wall Street analysts have a mixed outlook on Nebius’ bottom-line trajectory. For fiscal 2026, loss per share is expected to deepen 48% YOY to $2.62, followed by a 40% YOY improvement to a loss of $1.57 per share in fiscal 2027.
What Do Analysts Think About Nebius Stock?
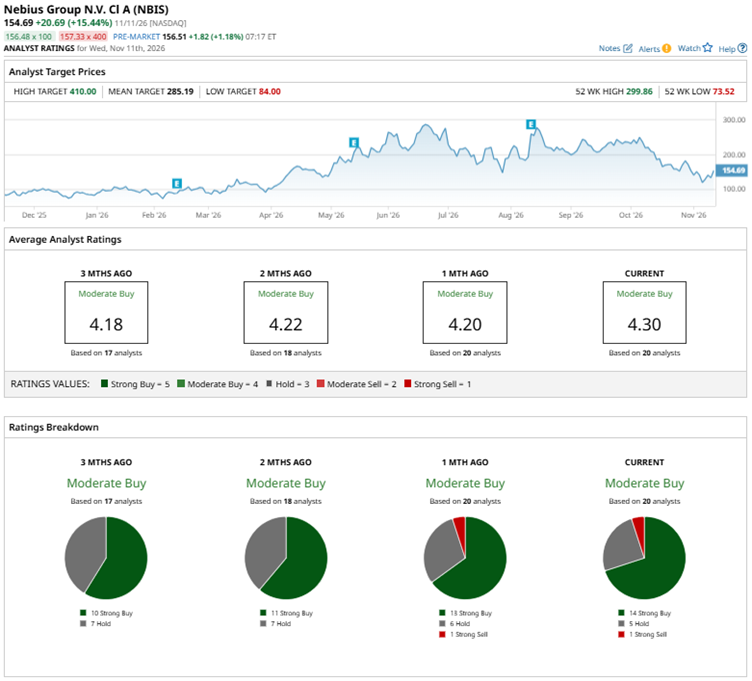
Citi analyst Tyler Radke recently maintained a “Buy” rating on NBIS stock but lowered the price target from $265 to $215. Piper Sandler also maintained a “Neutral” rating on Nebius while lowering the price target from $185 to $148. On the other hand, Rosenblatt kept a “Buy” rating and a $304 price target on the stock following the Q3 results.
Despite the selloff, Nebius remains a popular name on Wall Street, with analysts awarding it a consensus “Moderate Buy” rating overall. Of the 20 analysts covering the stock, 14 have a “Strong Buy” rating, five analysts have a “Hold” rating, and one analyst suggests a “Strong Sell.” The average price target of $259.12 represents potential upside of 140% from current levels. Moreover, the Street-high price target of $399 reflects a possible climb of 269% from here.
On the date of publication, Anushka Dutta did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.