


General merchandise retailer Target (NYSE:TGT) will be announcing earnings results this Wednesday before market hours. Here’s what to expect.
Target beat analysts’ revenue expectations last quarter, reporting revenues of $26.54 billion, up 5.3% year on year. It was a very strong quarter for the company, with a beat of analysts’ EPS estimates and full-year EPS guidance exceeding analysts’ expectations.
Is Target a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Target’s revenue to grow 5% year on year, a reversal from the 1.6% decrease it recorded in the same quarter last year.
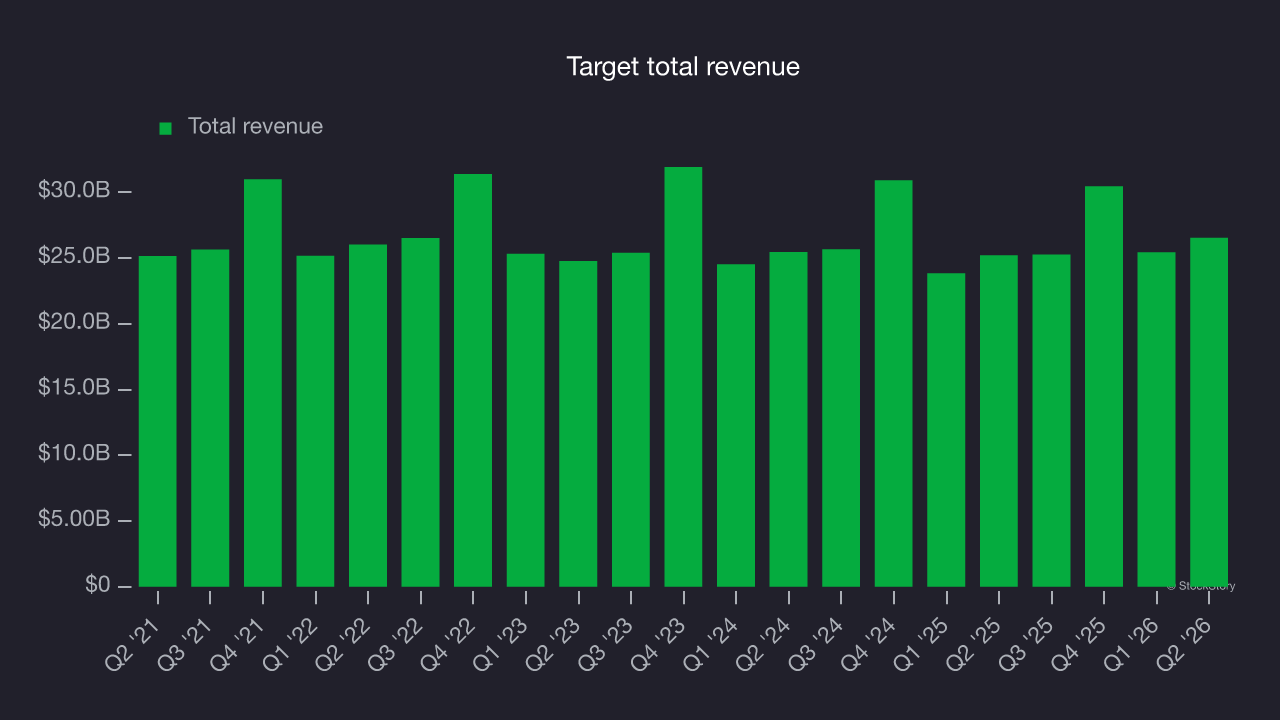
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Target has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Target’s peers in the non-discretionary retail segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Albertsons posted flat year-on-year revenue, meeting analysts’ expectations, and Grocery Outlet reported flat revenue, topping estimates by 1.1%. Albertsons traded up 4.3% following the results while Grocery Outlet was down 6.4%.
Read our full analysis of Albertsons’s results here and Grocery Outlet’s results here.
There has been positive sentiment among investors in the non-discretionary retail segment, with share prices up 3.8% on average over the last month. Target is up 4.5% during the same time and is heading into earnings with an average analyst price target of $166.29 (compared to the current share price of $160.15).
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.