


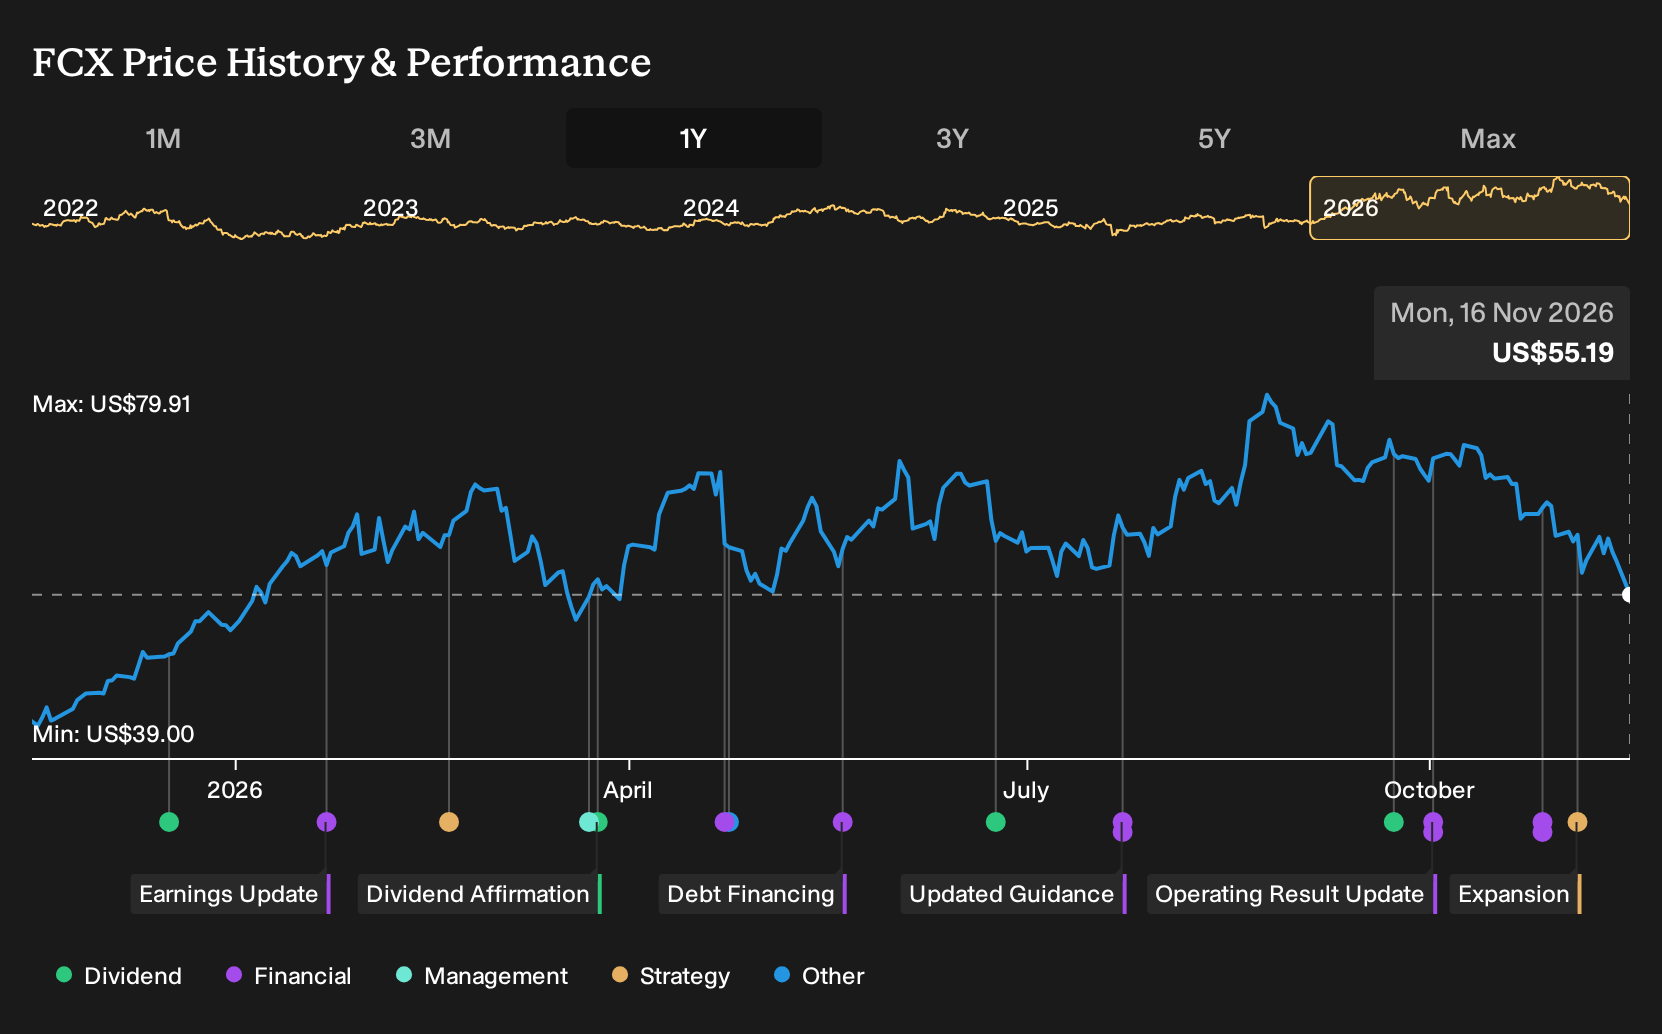
The story in this period starts with a concrete decision at Freeport-McMoRan: the approval of a US$4.5b plan to more than double output at the Bagdad copper mine in Arizona and cut unit net cash costs by roughly 20%. Investors who held Freeport-McMoRan over the past year are up 42.8%, including dividends. If you were choosing back on 2025-11-16, what needed to be true about future copper demand, U.S. policy support, and execution risk at projects like Bagdad to make that bet feel reasonable?
Freeport-McMoRan is not the only name tied to this theme. Zero in on 17 top copper producer stocks and compare how each one is priced.
The Two Stories Investors Were Weighing On Freeport-McMoRan
The shares cost US$40.16 at the start of the period. Anyone backing Freeport-McMoRan then was really choosing between two very different stories about copper, politics, and project execution.
On the optimistic side, one narrative pointed to a Fair Value of US$50.06, a rough guide to what supporters thought the stock should be worth if things played out as hoped. That view leaned on assumptions such as revenue growth of 6.5% and profit margins reaching 10.8% as new smelting capacity and U.S. policy support helped.
The cautious camp anchored on a Fair Value of US$27, implying the shares were already pricing in too much. This argument focused on risks such as technological substitution, tighter environmental rules, and geopolitical pressure in countries like Indonesia and Chile putting long term pressure on costs and demand for Freeport-McMoRan.
What The Results Changed For The Freeport-McMoRan Story
The clearest datapoint for Freeport-McMoRan is Q3 2026. Revenue reached US$7.546b versus US$6.972b in Q3 2025, and net income rose from US$667m to US$1.166b. Net margin moved from 9.6% to 15.5%. That combination leaned toward the optimistic case that assumed stronger profitability, even as Grasberg execution issues kept the cautious scenario alive.
The takeaway for other miners is simple. When a thesis hangs on higher margins, do not just track tonnes and prices. Watch the reported net margin and ask whether each new project or policy shift is actually lifting that percentage over time.
What Freeport-McMoRan’s Rally Now Asks You To Believe
Freeport-McMoRan trades at US$55.19 today after a 42.8% gain over the past year. The bullish analyst Narrative on Simply Wall St places its Fair Value above that level, based on a view that current projects and copper exposure support stronger future cash generation.
The Narrative leans heavily on leaching, brownfield expansions, Indonesian integration, and cost control. It argues today’s price still does not fully credit sustained delivery on these projects while keeping consolidated unit net cash costs near guidance despite higher capital and input spending.
"Bullish analysts expect Freeport-McMoRan to compound low-capex copper production growth from leaching, brownfield expansions, and Indonesian integration into higher cash generation over the next several years. The main thing that has to go right is sustained delivery on U.S. and Indonesian growth projects while holding consolidated unit net cash costs near current guidance despite rising capital and input cost pressures."
One Narrative disagrees with today's price. → See where this Narrative says Freeport-McMoRan should trade
Looking Past Freeport-McMoRan
Freeport-McMoRan tells one version of the copper story. Your watchlist does not have to stop there.
Big projects at Freeport-McMoRan highlight a simple need. Large mines still rely on fresh ore sources that can support long production runs.
Another producer is trying to answer that need differently. It is expanding a single mining hub, adding new plant capacity and underground infrastructure to reach more ore.
Deep drilling, new access tunnels and higher development rates aim to convert high grade zones into steady output.
The unresolved piece is how that move from building to harvesting could reshape its future options.
The case is written up, with the assumptions it depends on. → Discover the gold company one Narrative values 48% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com