


Richfield, Minnesota-based Best Buy Co., Inc. (BBY) offers technology products and solutions in the United States and internationally. The company has a market cap of $21.7 billion and provides computing and mobile phone products, such as desktops, notebooks, and peripherals; mobile phones, with related mobile network carrier commissions; networking products; and more.
BBY shares have rallied the broader market over the past year, surging 36.5% versus the S&P 500 Index’s ($SPX) 10.1% surge. Moreover, in 2026, the stock has grown by nearly 54.4%, outperforming the SPX’s 8.3% rise.
Zooming in, the State Street Consumer Discretionary Select Sector SPDR ETF (XLY) has grown 3.1% over the past year, underperforming the stock. In 2026, XLY has declined 1.3% and has also lagged behind the stock.
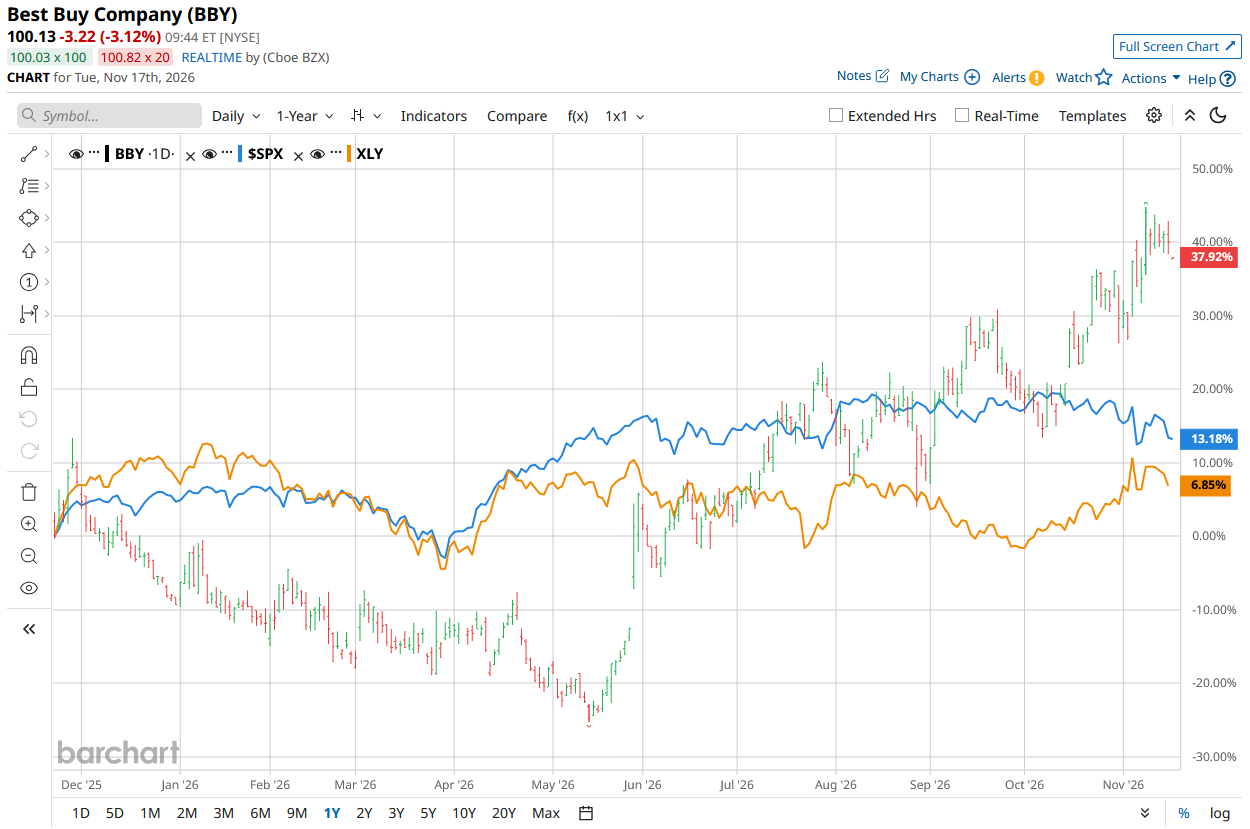
On Aug. 27, BBY released its Q2 2027 earnings, which topped Wall Street’s estimates. The company’s revenue for the quarter amounted to $9.8 billion, surpassing the Street’s forecasts. Additionally, its adjusted EPS came in at $1.47, also topping the consensus estimates. Best Buy expects full-year earnings in the range of $6.70 to $6.90 per share, with revenue in the range of $42.3 billion to $42.8 billion.
For the current year, which ends in January 2027, analysts expect BBY’s EPS to rise 5.9% to $6.81 on a diluted basis. The company surpassed the consensus estimate in each of the last four quarters, which is impressive.
Among the 24 analysts covering BBY stock, the consensus is a “Hold.” That’s based on four “Strong Buy” ratings, 18 “Holds,” one “Moderate Sell,” and one “Strong Sell.”
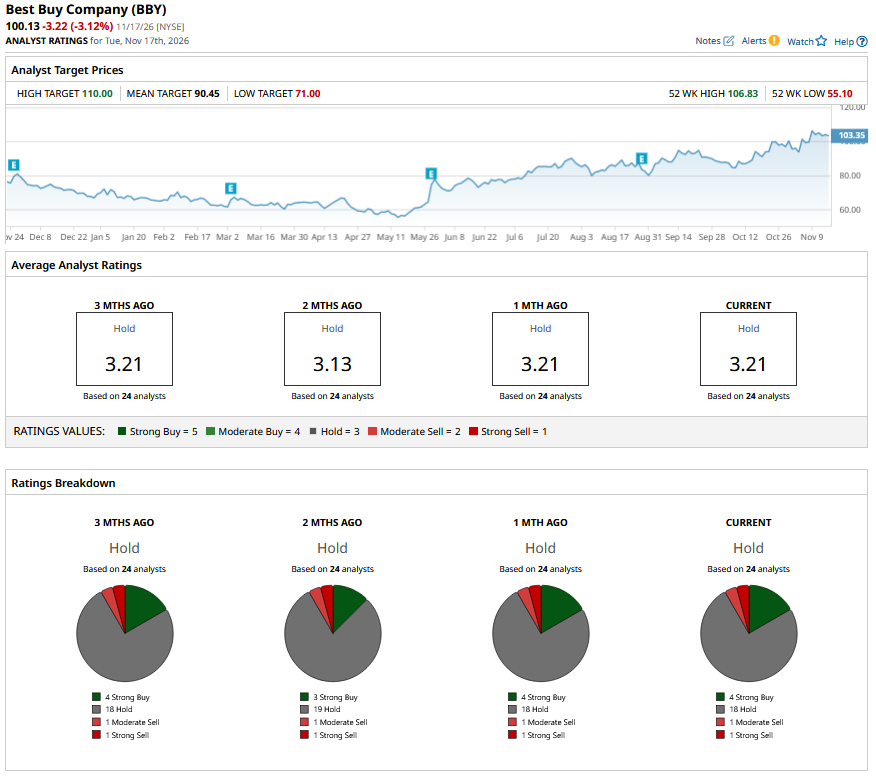
The configuration has remained largely unchanged over the past months.
On Nov. 17, Morgan Stanley analyst Simeon Gutman maintained a “Hold” rating on Best Buy and set a price target of $90.
BBY’s mean price target of $90.45 is below the current market price. Its Street-high target of $110 implies a 9.7% upside from current levels.
On the date of publication, Aritra Gangopadhyay did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.