


IperionX has delivered a very large 110.0% share price gain over the past five years, yet recent weakness raises a sharper issue for you as an investor. Is the current A$1.89 share price still in line with what the company’s book value can reasonably support compared with the wider industry?
- Over five years the stock has climbed 110.0%, which puts long term holders in profit and makes the link between that journey and the underlying net assets a live question.
- The business model and capital needs in materials and technology can be asset heavy, so the amount and quality of equity on the balance sheet may influence how comfortable you feel paying today’s price.
- There is a second opinion on IperionX worth weighing. See what analysts think IperionX's shares could be worth.
The issue now is whether IperionX’s recent market value lines up with what its book value suggests the shares are worth.
If you want context for IperionX’s valuation compared with other opportunities that focus on balance sheet strength, it can help to line it up beside solid balance sheet and fundamentals stocks screener (12 results).
Is IperionX Getting Expensive on Book Value?
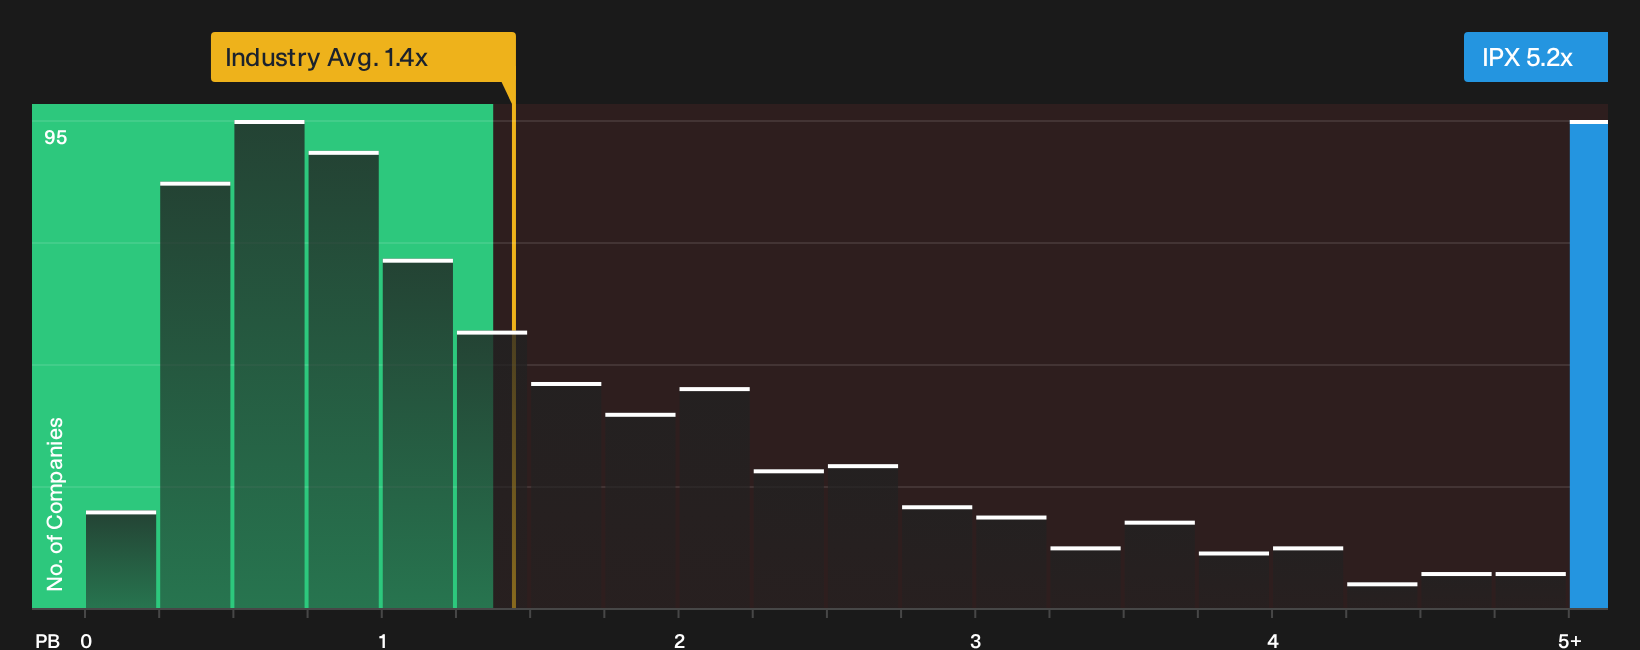
P/B suits IperionX because it is still building its earnings profile and investors are often anchoring on the balance sheet. On this yardstick, the stock trades on a P/B of about 5.2x, compared with a Metals and Mining sector average near 1.4x and a peer group closer to 2.3x. That is a steep premium to both the wider industry and more directly comparable businesses.
The size of that gap suggests the market is paying up heavily for IperionX’s future potential relative to its current equity base, and the model flags the shares as overvalued on this framework. Since the model is heavily penalising the company’s current losses and risk profile, the signal is better read as a warning that the stock screens very expensively on book value multiples rather than a precise estimate of where the price should land. Explore the numbers behind IperionX's P/B valuation.
The IperionX Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where that P/B puzzle for IperionX leaves off by spelling out which paths for future growth, profitability and earnings would need to play out for the share price to look meaningfully higher or lower than today. Each view links its number to a clear stance on how IperionX's growth, margins and risk profile might shift, giving you a reference point you can revisit as new information comes through on the Community page.
One of the top narratives on IperionX: 74% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The main factor that has to go right is the successful execution of the planned capacity expansions and mineral-to-metal integration, while managing funding needs and operational setbacks such as furnace downtime…"
Discover why this Narrative puts IperionX at 74% undervalued.
The unresolved question for IperionX, beyond price and book value
IperionX’s valuation story is only one side of the decision, because separate checks have already picked up specific areas of concern that deserve your attention before you rely on the current market pricing. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com