


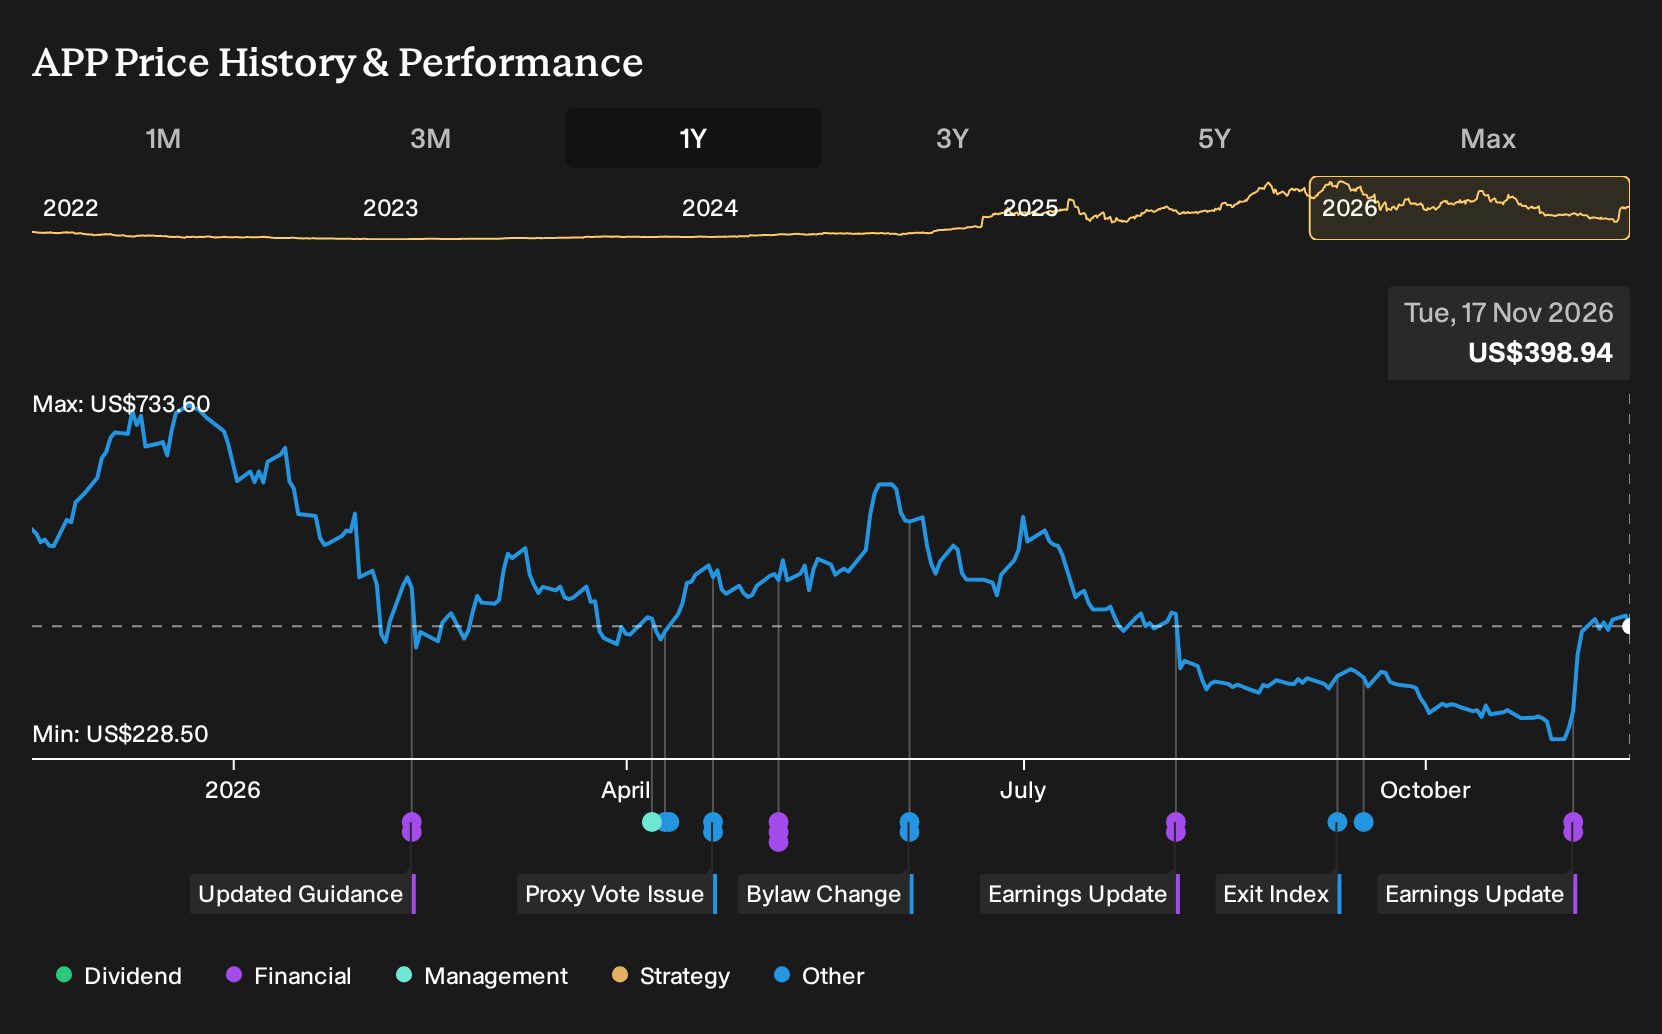
If you backed the bullish pitch that AXON would power a global mobile ad revolution and that AppLovin’s self-serve rollout plus e-commerce push would re-rate the stock, the past year has been rough. Investors who held AppLovin over the past year are down 24.2%, including dividends. If you made that call in November 2025, what did the original investment case fail to allow for in those specific growth, margin, and P/E assumptions?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
AppLovin is not the only name tied to this theme. Zero in on 41 AI small caps and compare how each one is priced.
The Two AppLovin Stories Investors Were Weighing
The shares cost US$539 at the start of the period, and anyone buying AppLovin then had to choose between two very different stories that both sounded reasonable.
The bullish narrative saw fair value at US$650, about 21% above the start price. It rested on AXON and self-serve tools helping revenue grow 28.5% a year and profit margins rising from 43.8% to 67.7%, with the stock eventually on a 34.8x P/E.
The bearish view put fair value at US$250, or 54% below the start price. That scenario assumed tighter privacy rules, slower expansion and a softer shift outside gaming, with earnings rising to US$4.9b, margins at 58.6% and a 28.8x P/E.
What The Evidence Did To The AppLovin Argument
AppLovin’s Q3 2026 report showed revenue at US$2.18b and net income at US$1.44b, with net margin at 65.9%, above the 59.5% level a year earlier. That profitability picture leaned toward the bull case on margins. Yet slowing growth worries, e-commerce execution questions, legal action and analyst downgrades gave the cautious camp fresh support. Overall the evidence cut both ways.
The clear hinge here was not hype about AXON but rather how fast high margins arrived and how reliably they were kept. For any similar stock, test claims about future profitability and scale against the reported net margin, revenue mix and updated growth guidance each quarter.
What The Drop In AppLovin’s Price Leaves You Weighing
AppLovin now trades at US$399, down 24.2% over the past year. The current Narrative’s Fair Value sits above that level, which reflects the author’s view rather than a settled verdict on where the stock should trade.
According to RedCandleRx, an investor in the Simply Wall St Community, the crux is whether you believe AppLovin’s outcome-based ad model and data asset can keep compounding. A buyer today has to judge that this data advantage and margin profile outlast the recent share price drop.
"AppLovin holds an enormous store of consumer behavior data, accumulated over years, much of it from the app portfolio it used to own and all of it added to every single time an ad runs through the network. The model learns from every impression."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
Passing on this one could have spared you a loss. Where might you find the opposite surprise? Start looking for companies whose prices leave room for a better outcome than investors expect. These three trade below our estimated value.
- Company 1 - 33% below our estimate - runs contracted offshore vessels into energy projects as older fleets retire and retool.
- Company 2 - 43% below our estimate - shifts capital from a divested label into higher margin performance-focused apparel and footwear lines.
- Company 3 - 29% below our estimate - assembles a full connectivity stack spanning SerDes IP, active cables, optics and integrated photonics.
That is three of the list. See the full list of 37 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com