


A repurchase plan of up to 60 million US dollars, equivalent to HK$471 million, compounded by intensive investment banks' optimism, and shareholders' holdings increased many times. Has Nexteer (01316) reversed?
The Zhitong Finance App learned that as a leader in auto parts, Nexteer's performance has maintained steady growth. However, in 2026, the valuation retracted by nearly 30%, and the net market ratio once fell below 0.7 times, which is in a historically low range. In order to boost market confidence, the company approved a share repurchase plan of up to US$60 million, or HK$4.71, on November 12. Since then, it has repurchased a total of 4.585,000 shares in four consecutive transactions.
The company showed signs of a steady rebound. After increasing volume on November 5, the company continued to shrink, and its stock price rose by more than 10% in the last three weeks. For Nexteer, there is performance support. A series of recent actions, including buybacks, holdings increases, and investment bank endorsements, etc., may signal the bottom of the valuation.
Congruence and deviation. The bottom of the valuation is already there
Referring to Nexteer's historical valuations and performance trends, there are consistent and deviations, but they can often be corrected after deviating from the trajectory. The company landed on the Hong Kong Stock Exchange in October 2013. Five years before listing, the market capitalization continued to rise and break new highs year after year. The increase was as high as 5.24 times during the period, and the performance also maintained double-digit compound growth. The compound revenue growth rate for the period was 12.9%, and the compound growth rate of shareholders' net profit was 34.1%.
In 2018-2020, the company entered a double adjustment of performance and valuation. During this period, market capitalization fell back, and revenue resumed double-digit growth. However, profit recovery was slow, and revenue growth suppressed the room for valuation growth. From 2022 to 2024, due to double market and sector adjustments, valuation continued to decline from fundamentals. It was quickly repaired in 2025, and the market value increased by more than 100%. The market value declined in 2026, but performance remained at a growth level, and profitability continued to improve.
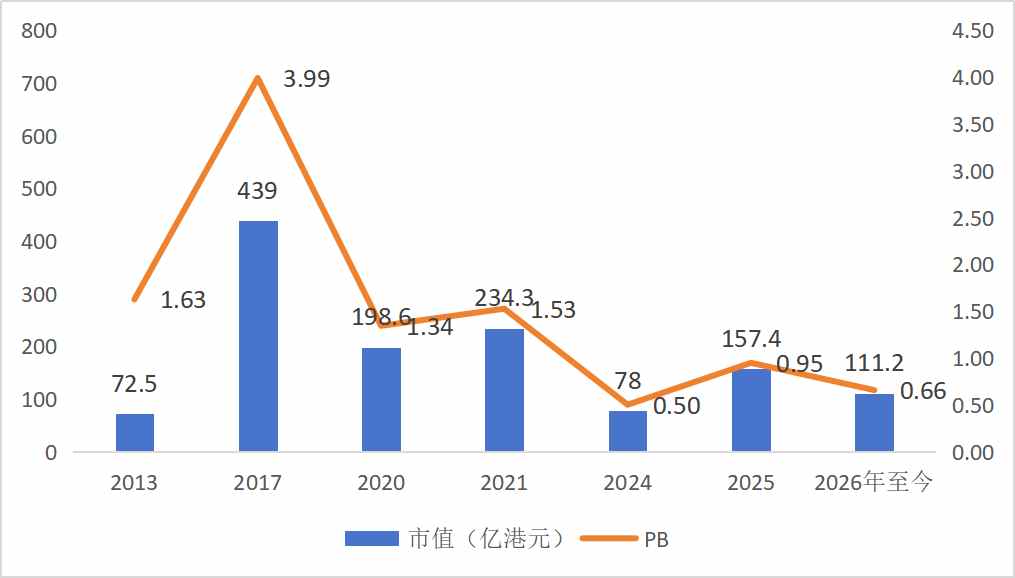
Data source: Nexteer public data processing (exchange rate is real-time exchange rate)
As can be seen, the degree of compatibility between Nexteer's valuation and performance depends on the general market environment, but even if it deviates, performance still supports growth and drives valuation to return as the market improves.
In fact, Nexteer's trend is not isolated. Most high-quality tickets are affected by a lot of noise in the market. Performance and valuations are not linear. Geographic conflicts such as the 2026 Middle East war are frequent, the Fed's interest rate hike affects asset flows, and global macroeconomic weakness has caused pessimism. Coupled with AI high valuations squeezing the bubble, all of these events have dragged down the market to weaken. For example, high-quality technology leaders such as Tencent and SMIC have withdrawn sharply.
As far as auto parts are concerned, 2026 will not be easy. Sales of new energy vehicles are slowing down. Although exports have become an engine of growth, overall sales expectations are weaker than in previous years, putting further pressure on the entire sector. However, as mentioned above, valuations have returned nonlinearly, and the iron still needs to be hardened. Whether Nexteer has the sustainability of performance growth and a new growth story is the key to later valuation repair.
Performance has increased steadily, and new business is the highlight of growth
NexteX has strong business and a global market. The company's business includes electric steering assistance (EPS), power transmission systems (DL), steering columns and intermediate shafts (CIS), and hydraulic power steering (HPS). The core markets cover China, the United States, Mexico and Poland. EPS is the company's core revenue source, accounting for nearly 70% of revenue. However, the company's market distribution is balanced, and the top three markets all have more than 20% revenue.
Leaving aside the short-term noise of stock prices, looking at the results of the last two years, Nexteer's financial data for the full year of 2025 and the first half of 2026 showed a clear upward curve.
Throughout 2025, the company's revenue reached a record US$4.58 billion, up 7.2% year on year. Excluding the impact of exchange rates and commodity recycling, the organic growth rate was 6.9%, outperforming the market by 320 basis points, and the annual gross margin increased 0.9 percentage points to 11.4%, while net profit to the mother increased 65.3% year over year to US$102 million, and adjusted EBITDA increased 11.2% to US$472 million; entering 2026, this trend continued. Revenue for the first half of the year was US$2.33 billion, up 4% year on year, and net profit to mother of 0.86 million yuan The dollar increased 35% year over year.
In the research report, Cathay Pacific Haitong attributed this to “the continuous implementation of efficiency mining over the past few years.” In the subregion, the three core markets, including the US, China, and Mexico, grew steadily. In addition, profit recovery in Europe and other regions was particularly significant. EBITDA profit margins increased 3.5 percentage points year over year, thanks to the dual drivers of revenue growth and internal efficiency optimization in the region. What the company has expectations is the full commercialization of new businesses such as wire control technology.
Nexteer is a global leader in steering systems and has card position advantages in online control technology. Wire-controlled steering is widely regarded as the ultimate form of steering system. It removes the mechanical connection between the steering wheel and steering gear, and is essential hardware for autonomous driving L3 and above. Nexteer has been in this field for many years, and the first half of 2026 finally reached a milestone: two wire-controlled steering projects entered mass production, supporting Ideal L9 and an L4 autonomous taxi application in North America, respectively.
As of the first half of 2026, the company has targeted 7 wire-controlled mass production projects, covering three major regions. Customers include many leading NEV companies in China. Total order demand was strong. During this period, the company's backlog of orders reached 3.3 billion US dollars, an increase of 1.2 times over the previous year, and it is expected to reach the order target of 6 billion US dollars for the whole year. Driven by orders, performance growth can be expected to continue, and the strong performance of new businesses will also be an accelerator for valuation return.
Multiple signs of confidence, valuation repair can be expected
Supported by performance expectations, Nexteer's recent actions at the capital allocation level have also formed a dense set of confidence signals, consolidating the tough logic behind the company's valuation base.
In November 2026, the company launched a repurchase plan of over HK$400 million and began continuous share repurchases on the Hong Kong Stock Exchange. It repurchased HK$7.809 million, HK$4.254 million, HK$4.377,800 and HK$4,587,900 for four consecutive trading days from the 12th to the 17th of that month, with a cumulative repurchase amount of HK$21 million, for a total of 4,585,000 shares. Buybacks have only just begun and account for a relatively low share, but as the intensity intensified, they provided support for valuations and investor confidence.
Furthermore, the company insisted on paying dividends every year, and the final dividend for 2023-2025 continued to increase to HK$0.023, HK$0.068 and HK$0.143 respectively, doubling fivefold over three years, with a compound increase of 147.7%. At current market capitalization, the dividend ratio is 3.23%. The company's free cash flow in the first half of 2026 reached US$109 million, nearly three times that of the same period last year, to guarantee the implementation of the company's dividends and repurchases.
Notably, the company received a continuous increase in shareholders' holdings. According to the Stock Exchange equity disclosure, BlackRock increased its holdings of Nexteer by 2.483 million shares in August 2026, increasing its shareholding ratio from 5.98% to 6.08%. Later, at the end of September, BlackRock once again increased its holdings through OTC methods, and the good position ratio further rose to 7.01%. The average price of BlackRock's holdings increase is higher than the current stock price, which means that its increase in holdings is based on the left-hand layout of value judgments.
Investment banks are also optimistic about the company's development. For example, Cathay Pacific Haitong's latest research report suggests that the shift to wire control and mass production is expected to reach 6 billion US dollars, and that annual orders are expected to reach 6 billion US dollars, and that repurchases and high dividends show confidence and maintain Nexteer's “increase” rating. The target price is HK$11.48, which has more than 150% room for growth compared to the current price. Previously, in the August interim report, the agency had raised the target price to HK$10.40. Another increase this time shows that it is highly optimistic about the company.
Taken together, a typical valuation deviation scenario in the Nexteer Hong Kong stock market fully reflects the general market and industry environment, but what the performance data reveals is a company with continuous record highs in revenue, continuous restoration of profit margins, and a shift from concept to mass production. The company attaches importance to shareholder returns, buybacks, dividends+shareholders' holdings. Furthermore, the investment bank is optimistic, giving a high premium to the target price, and there is plenty of room for valuation repair.